
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Consumer Staples Remains Leading: Consumer Staples (XSJ) continues to occupy the Leading quadrant, maintaining the strongest combination of relative strength and momentum.
- Consumer Discretionary Enters Improving: Consumer Discretionary (XDJ) has moved into Improving, representing a notable recovery in relative momentum.
- Financials Continue Improving: Financials (XFJ) remain in Improving and are positioned strongly within the quadrant.
- Real Estate and Industrials Remain Improving: Real Estate (XPJ) and Industrials (XNJ) continue to show improving relative momentum.
- Communication Services Moves into Improving: Communication Services (XTJ) has entered Improving, indicating a recovery from its previous Lagging position.
- Resource Sectors Remain Weakening: Energy (XEJ), Resources (XJR) and Materials (XMJ) remain in Weakening despite their recent relative strength.
- Health Care Remains Weakening: Health Care (XHJ) continues to occupy the Weakening quadrant and remains relatively deep within it.
- Technology Remains Lagging: Information Technology (XIJ) is the only sector positioned in Lagging, indicating continued weakness in relative strength and momentum.
The latest Relative Rotation Graph for 10 September 2026 shows a gradual improvement across several previously weaker ASX sectors. Consumer Staples (XSJ) remains in Leading, while Financials (XFJ), Real Estate (XPJ), Industrials (XNJ), Communication Services (XTJ) and Consumer Discretionary (XDJ) are positioned in Improving. Energy (XEJ), Utilities (XUJ), Resources (XJR), Materials (XMJ) and Health Care (XHJ) remain in Weakening, while Information Technology (XIJ) is the only sector in Lagging. The latest daily performance data also shows that all twelve sectors declined, highlighting the difference between short-term price performance and broader relative momentum.
Momentum Breakdown by Quadrant
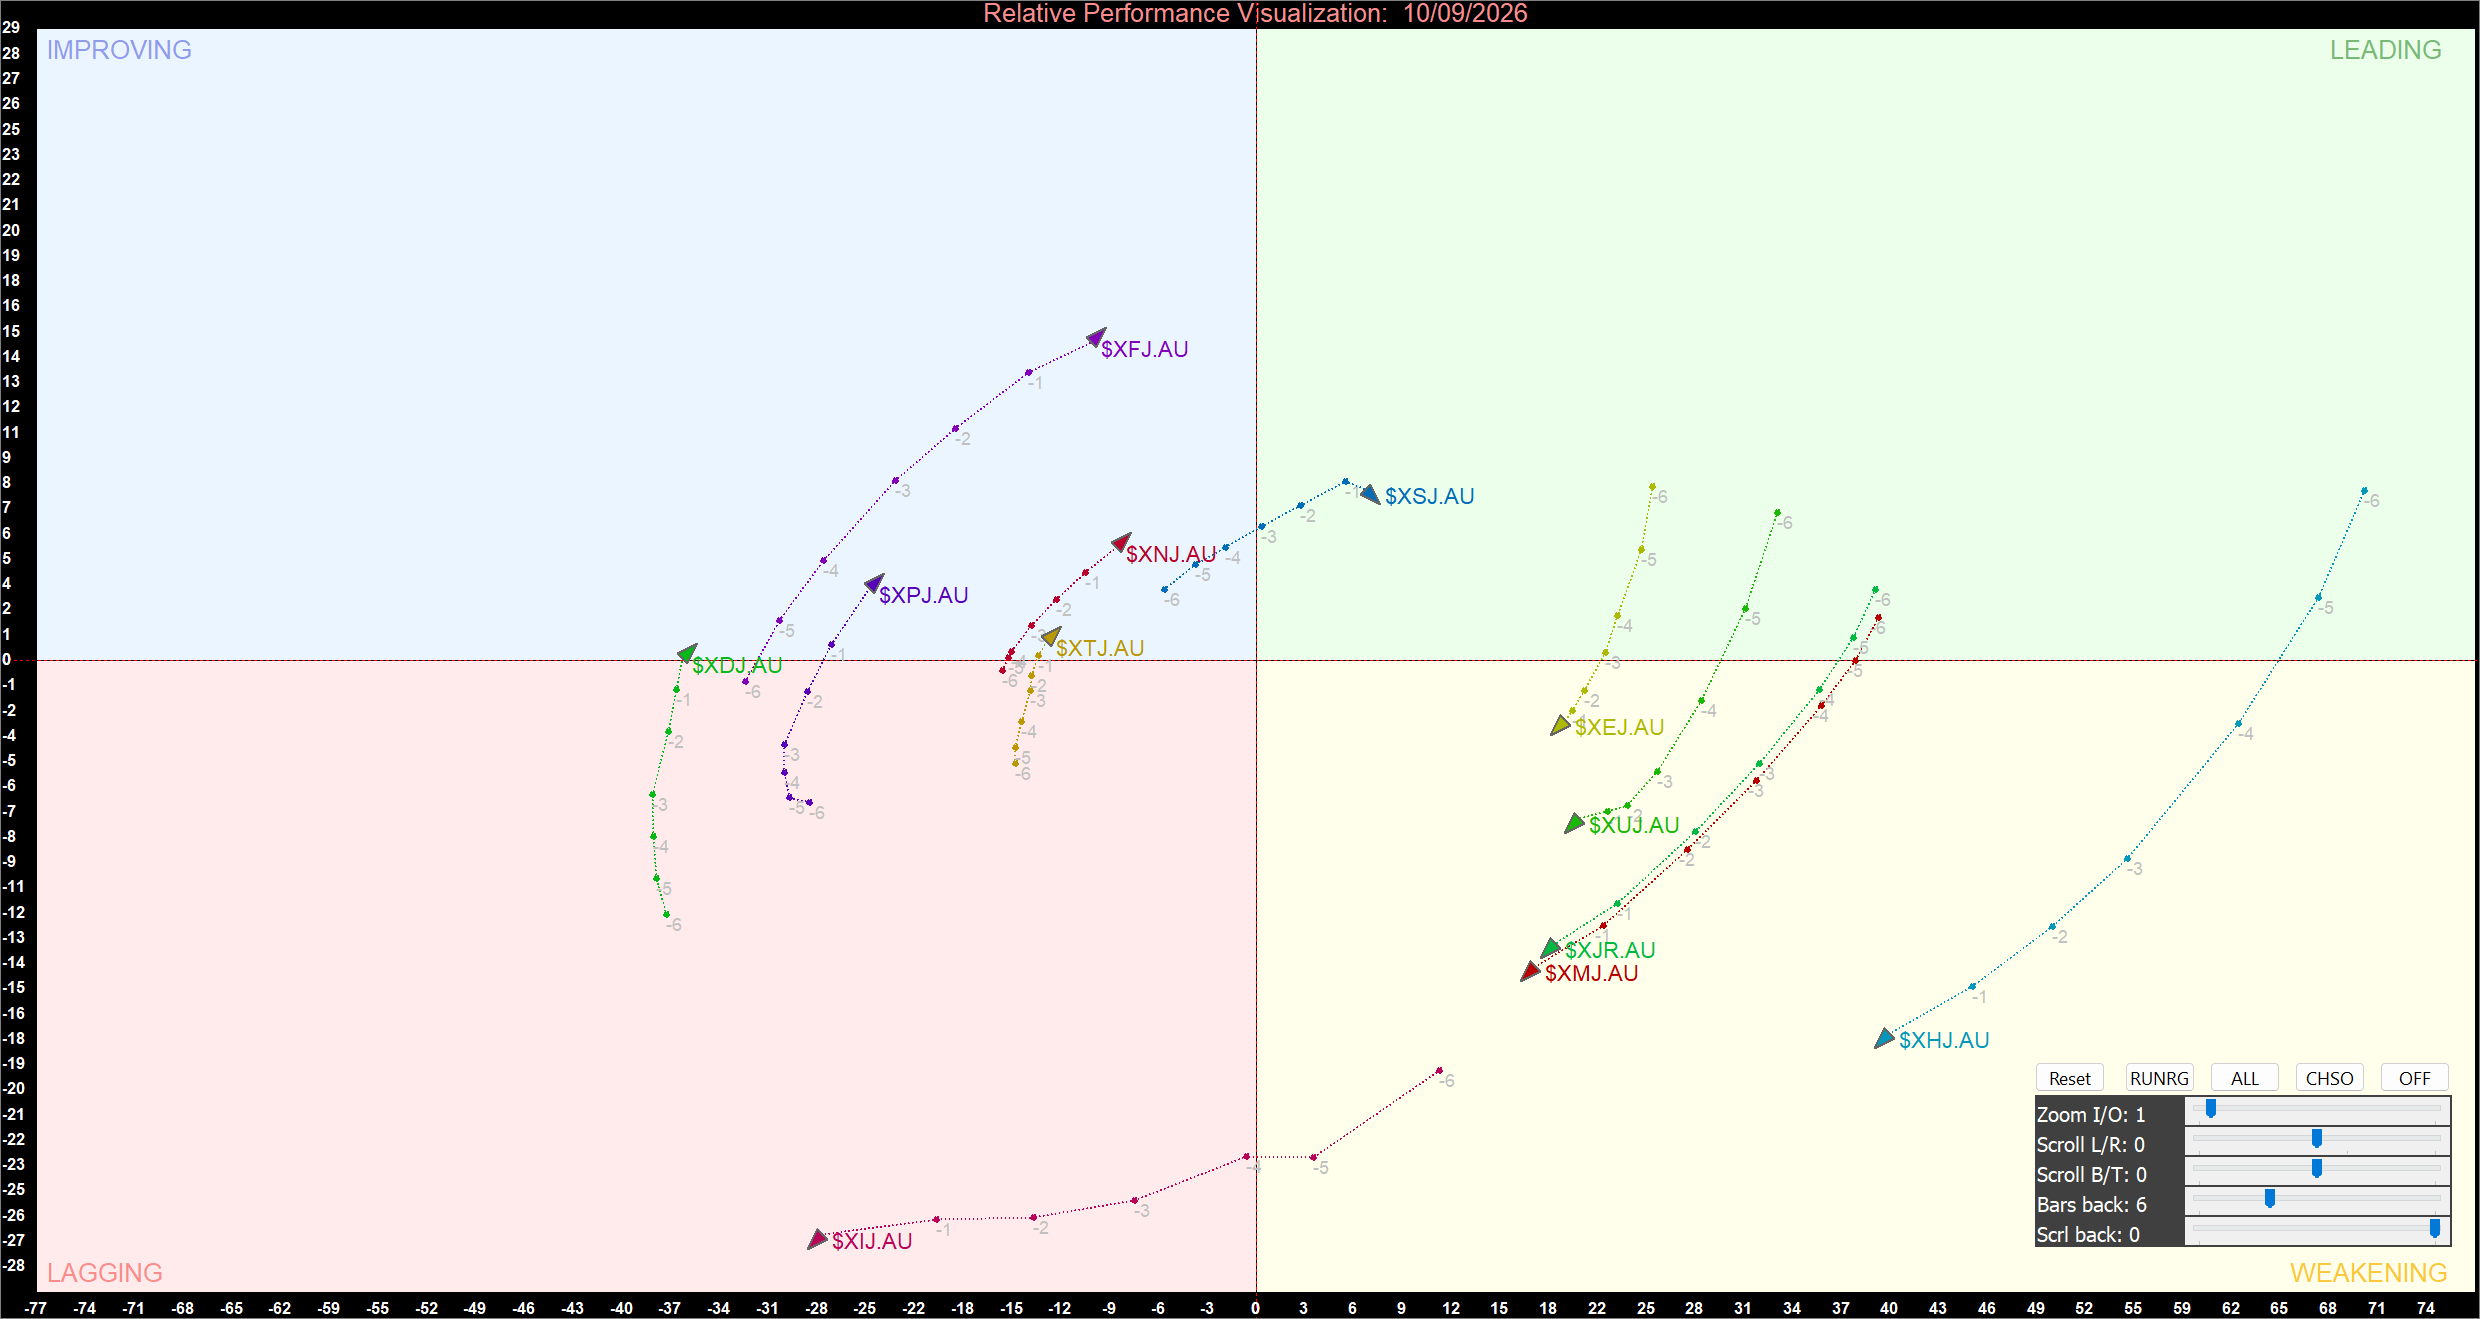
ASX Sector Relative Momentum Chart (at the closing price of 10/09/2026). Powered by: amibroker.com.
Leading Quadrant
Consumer Staples (XSJ) remains the only sector positioned in the Leading quadrant, giving it the strongest combination of relative strength and momentum on the latest RRG.
The continued position of XSJ in Leading is particularly notable because the sector declined 0.75% on 10 September. Despite this negative daily performance, its RRG position indicates that its broader relative momentum remains stronger than that of most other ASX sectors.
This demonstrates that a sector can experience a short-term decline while maintaining a favourable position within the relative momentum cycle. Continued movement in the upper-right area would reinforce Consumer Staples' leadership.
Improving Quadrant
Financials (XFJ), Real Estate (XPJ), Industrials (XNJ), Communication Services (XTJ) and Consumer Discretionary (XDJ) are positioned in Improving.
The most notable development is Consumer Discretionary's movement into Improving. XDJ had previously been positioned in Lagging, and its latest location above the horizontal midpoint indicates an improvement in relative momentum. Although Consumer Discretionary declined 0.63% on 10 September, its RRG trajectory suggests that the sector's broader momentum is recovering.
Financials remains one of the more strongly positioned sectors within Improving. The sector declined 0.90% during the session, but its RRG trajectory continues to indicate improving relative momentum.
Real Estate declined 0.60%, while Industrials fell 1.04%. Both remain in Improving, suggesting that their relative momentum is recovering despite recent price weakness.
Communication Services also moved into Improving. XTJ recorded the smallest decline among all twelve sectors at just 0.13%, providing additional support for its improving relative position. A continued move toward the upper-right would strengthen the possibility of a transition into Leading.
Weakening Quadrant
Energy (XEJ), Utilities (XUJ), Resources (XJR), Materials (XMJ) and Health Care (XHJ) remain in Weakening.
The positioning of the resource-related sectors is particularly important. Energy declined 0.67% on 10 September, while Resources fell 1.50% and Materials declined 1.63%. These sectors had previously shown stronger relative performance, but their current RRG positions indicate that their broader momentum remains under pressure.
Resources and Materials are particularly notable because they experienced some of the largest daily declines in the latest session. Their continued position in Weakening suggests that the previous strength in commodity-related areas has not yet translated into a sustained improvement in relative momentum.
Utilities declined only 0.33%, making it one of the strongest performers on a daily basis, but its RRG position remains in Weakening. This again highlights the distinction between one-day price performance and the broader momentum cycle.
Health Care (XHJ) declined 0.71% and remains positioned in Weakening. Its location indicates that the sector continues to experience deterioration in relative momentum and has yet to establish a convincing recovery.
Lagging Quadrant
Information Technology (XIJ) is the only sector positioned in Lagging, reflecting weak relative strength and subdued momentum.
XIJ declined 1.74% on 10 September, recording the largest loss among all twelve ASX sectors. The combination of the weakest daily performance and its position in Lagging makes Information Technology the clearest area of weakness in the current sector momentum structure.
The RRG trajectory indicates that the sector would need to move back toward the centre of the chart before a meaningful recovery could be confirmed. A sustained move into Improving would provide stronger evidence that technology's relative momentum is beginning to recover.
Bottom Line
The 10 September 2026 ASX RRG shows a gradual improvement in the number of sectors positioned in Improving. Consumer Staples remains the sole sector in Leading, while Financials, Real Estate, Industrials, Communication Services and Consumer Discretionary occupy Improving.
The movement of Consumer Discretionary into Improving is the most significant positive shift. Communication Services has also strengthened, while Financials remains well positioned within the improving quadrant.
Meanwhile, Energy, Utilities, Resources, Materials and Health Care remain in Weakening. The continued weakness of Resources and Materials is particularly notable following their strong relative performance in the previous session.
Information Technology remains the only sector in Lagging and also recorded the largest daily decline of 1.74%. Overall, the latest RRG suggests that momentum is beginning to improve across several sectors, but the market has not yet established broad-based leadership. Continued movement by the Improving sectors toward Leading, together with a recovery in Technology, would provide stronger evidence of improving ASX sector momentum.


 Nov 12, 2026





 Please wait processing your request...