
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Consumer Discretionary Extends Leadership: Consumer Discretionary (XDJ) continues advancing deeper into the Leading quadrant, displaying one of the strongest combinations of improving relative strength and momentum across the ASX sectors.
- Healthcare and Consumer Staples Maintain Market Leadership: Health Care (XHJ) and Consumer Staples (XSJ) remain firmly positioned within the Leading quadrant, although both sectors are showing modest easing in momentum while preserving superior relative strength.
- Utilities and Financials Continue Building Momentum: Utilities (XUJ), Financials (XFJ), and Information Technology (XTJ) remain in the Improving quadrant, suggesting these sectors are strengthening and could become future market leaders if current trends persist.
- Industrials, Energy, Materials, and Real Estate Remain Structural Laggards: Industrials (XIJ), Energy (XEJ), Materials (XMJ), and Real Estate (XJR) continue to occupy the Lagging quadrant, reflecting persistent weakness in their relative performance despite occasional short-term price rebounds.
The Relative Rotation Graph (RRG) for 25 June 2026 continues to highlight a highly selective Australian equity market where institutional investors remain concentrated in sectors demonstrating superior relative strength and sustainable earnings characteristics. Defensive and consumer-oriented industries continue to dominate leadership, while commodity-related and economically sensitive sectors remain under pressure. The latest rotation also suggests investors are rewarding sectors benefiting from resilient domestic demand rather than those dependent on global commodity cycles.
ASX Sector Momentum Summary
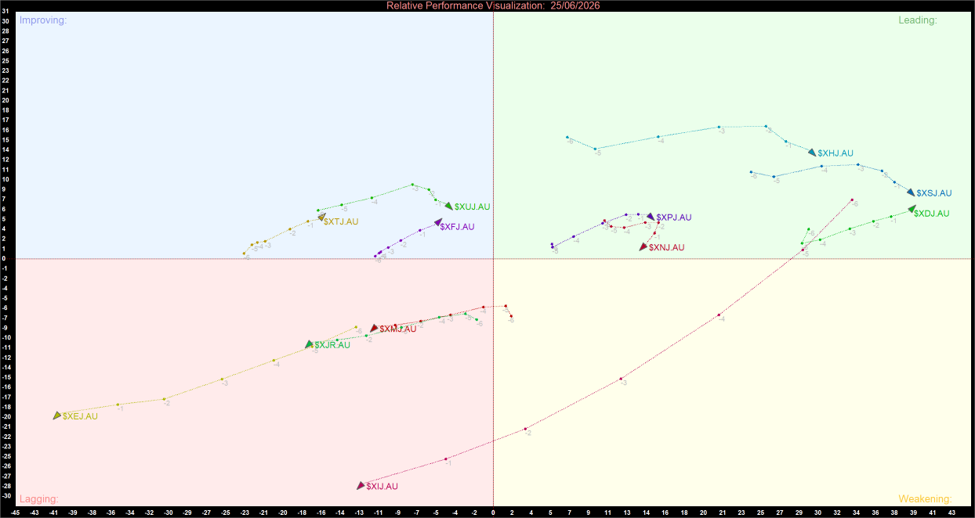
ASX Sector Relative Momentum Chart (at the closing price of 25/06/2026). Powered by: amibroker.com
Momentum Breakdown by Quadrant
The Leading Quadrant (The Market Leaders)
- Consumer Discretionary (XDJ) continues to strengthen within the Leading quadrant and is one of the most constructive sectors on the Relative Rotation Graph. Its trajectory remains firmly northeast, indicating simultaneous improvements in both relative strength and relative momentum. The sector's continued advance reflects growing investor confidence in consumer spending, improving economic activity, and stronger earnings prospects among consumer-focused companies.
- Health Care (XHJ) remains firmly established within the Leading quadrant. Although relative momentum has moderated modestly from earlier peaks, the sector continues to exhibit exceptional relative strength versus the broader market. Investors continue to favour Healthcare for its resilient earnings profile, defensive characteristics, and long-term structural growth outlook.
- Consumer Staples (XSJ) maintains a solid leadership position despite a gradual decline in momentum. Relative strength remains among the strongest across all ASX sectors, indicating that investors continue to seek businesses capable of delivering stable earnings and predictable cash flows during periods of market uncertainty.
- Communication Services (XPJ) remains comfortably positioned within the Leading quadrant. While recent momentum has stabilised, the sector continues to outperform the broader market, supported by ongoing demand for digital media, telecommunications, and communication-related businesses.
- Clean Energy (XNJ) continues to hold its position inside the Leading quadrant, although it is situated close to the momentum threshold. Relative strength remains positive, suggesting the sector continues to benefit from favourable long-term renewable energy investment themes despite short-term fluctuations in investor sentiment.
The Improving Quadrant (The Emerging Leadership Candidates)
- Utilities (XUJ) remains one of the strongest sectors within the Improving quadrant. Its trajectory continues moving steadily toward the Leading quadrant, indicating strengthening relative momentum. The sector continues to attract investors seeking defensive earnings, reliable dividend income, and lower volatility.
- Financials (XFJ) continue progressing higher within the Improving quadrant despite recent price weakness. The improving momentum profile suggests banking and financial stocks are gradually rebuilding relative strength and could challenge for market leadership if the current trend continues.
- Information Technology (XTJ) maintains its steady recovery trajectory. Relative momentum continues to improve while relative strength gradually catches up, suggesting technology stocks remain in the early stages of rebuilding investor confidence following previous underperformance.
The Lagging Quadrant (The Structural Underperformers)
- Industrials (XIJ) remains firmly positioned within the Lagging quadrant following its sharp deterioration in relative strength during recent sessions. Despite delivering one of the strongest price performances earlier in the week, the sector has been unable to translate those gains into sustained relative outperformance. This divergence suggests institutional investors continue allocating capital toward sectors with more durable leadership characteristics.
- Materials (XMJ) continues to underperform the broader market. Although relative momentum has stabilised modestly, the sector remains trapped in the Lagging quadrant as investors remain cautious toward mining companies amid uncertainty surrounding global commodity demand and resource prices.
- Real Estate (XJR) remains firmly positioned within the Lagging quadrant despite showing some gradual improvement in momentum. Ongoing concerns surrounding interest rates, borrowing costs, and commercial property valuations continue to weigh on investor sentiment toward property-related companies.
- Energy (XEJ) continues to occupy the weakest position on the Relative Rotation Graph. While its trajectory has begun to rotate modestly toward improving momentum, the sector remains deeply embedded within the Lagging quadrant, indicating that any recovery remains tentative and lacks confirmation. Commodity price weakness and cautious investor sentiment continue to limit the sector's relative performance.
Strategic Summary
The latest Relative Rotation Graph continues to reinforce the market's preference for defensive growth and consumer-oriented sectors. Consumer Discretionary (XDJ) has emerged as one of the strongest momentum leaders, while Healthcare (XHJ), Consumer Staples (XSJ), Communication Services (XPJ), and Clean Energy (XNJ) continue to demonstrate superior relative strength and sustained institutional support.
Meanwhile, Utilities (XUJ), Financials (XFJ), and Information Technology (XTJ) remain the leading candidates to transition into the Leading quadrant as their relative momentum continues to improve. In contrast, Industrials (XIJ), Materials (XMJ), Real Estate (XJR), and Energy (XEJ) remain structural underperformers, suggesting investors are still avoiding sectors heavily exposed to commodity prices, cyclical earnings, and interest-rate sensitivity.
Unless these lagging sectors begin to exhibit sustained improvements in both relative strength and momentum, market leadership is likely to remain concentrated in Healthcare, consumer-related industries, and other defensive growth sectors that continue to display the strongest momentum characteristics.


 Nov 12, 2026





 Please wait processing your request...