
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Information Technology (XIJ), Consumer Discretionary (XDJ) and Consumer Staples (XSJ) are positioned in the Leading quadrant.
- Materials (XMJ), Resources (XJR) and Real Estate (XPJ) remain in Improving, indicating strengthening relative momentum.
- Health Care (XHJ), Industrials (XNJ) and Financials (XFJ) are positioned in Weakening.
- Communication Services (XTJ), Energy (XEJ) and Utilities (XUJ) remain in Lagging.
- Information Technology maintains the strongest relative momentum position, although its trajectory has turned downward in the latest observations.
- Materials, Resources and Real Estate are attempting to strengthen their momentum and potentially transition toward Leading.
- The three sectors in Weakening require a recovery in momentum to avoid further deterioration in their relative positions.
- The distribution across all four quadrants indicates continued sector rotation rather than a broad-based improvement in relative momentum.
The ASX sector momentum structure on 9 October 2026 remained mixed, with Information Technology, Consumer Discretionary and Consumer Staples positioned in Leading, while Materials, Resources and Real Estate occupied Improving. Health Care, Industrials and Financials remained in Weakening, whereas Communication Services, Energy and Utilities were positioned in Lagging. The configuration indicates that relative momentum continues to favour selected sectors, while others are either attempting to recover or experiencing further deterioration.
ASX Sector Momentum Quadrants
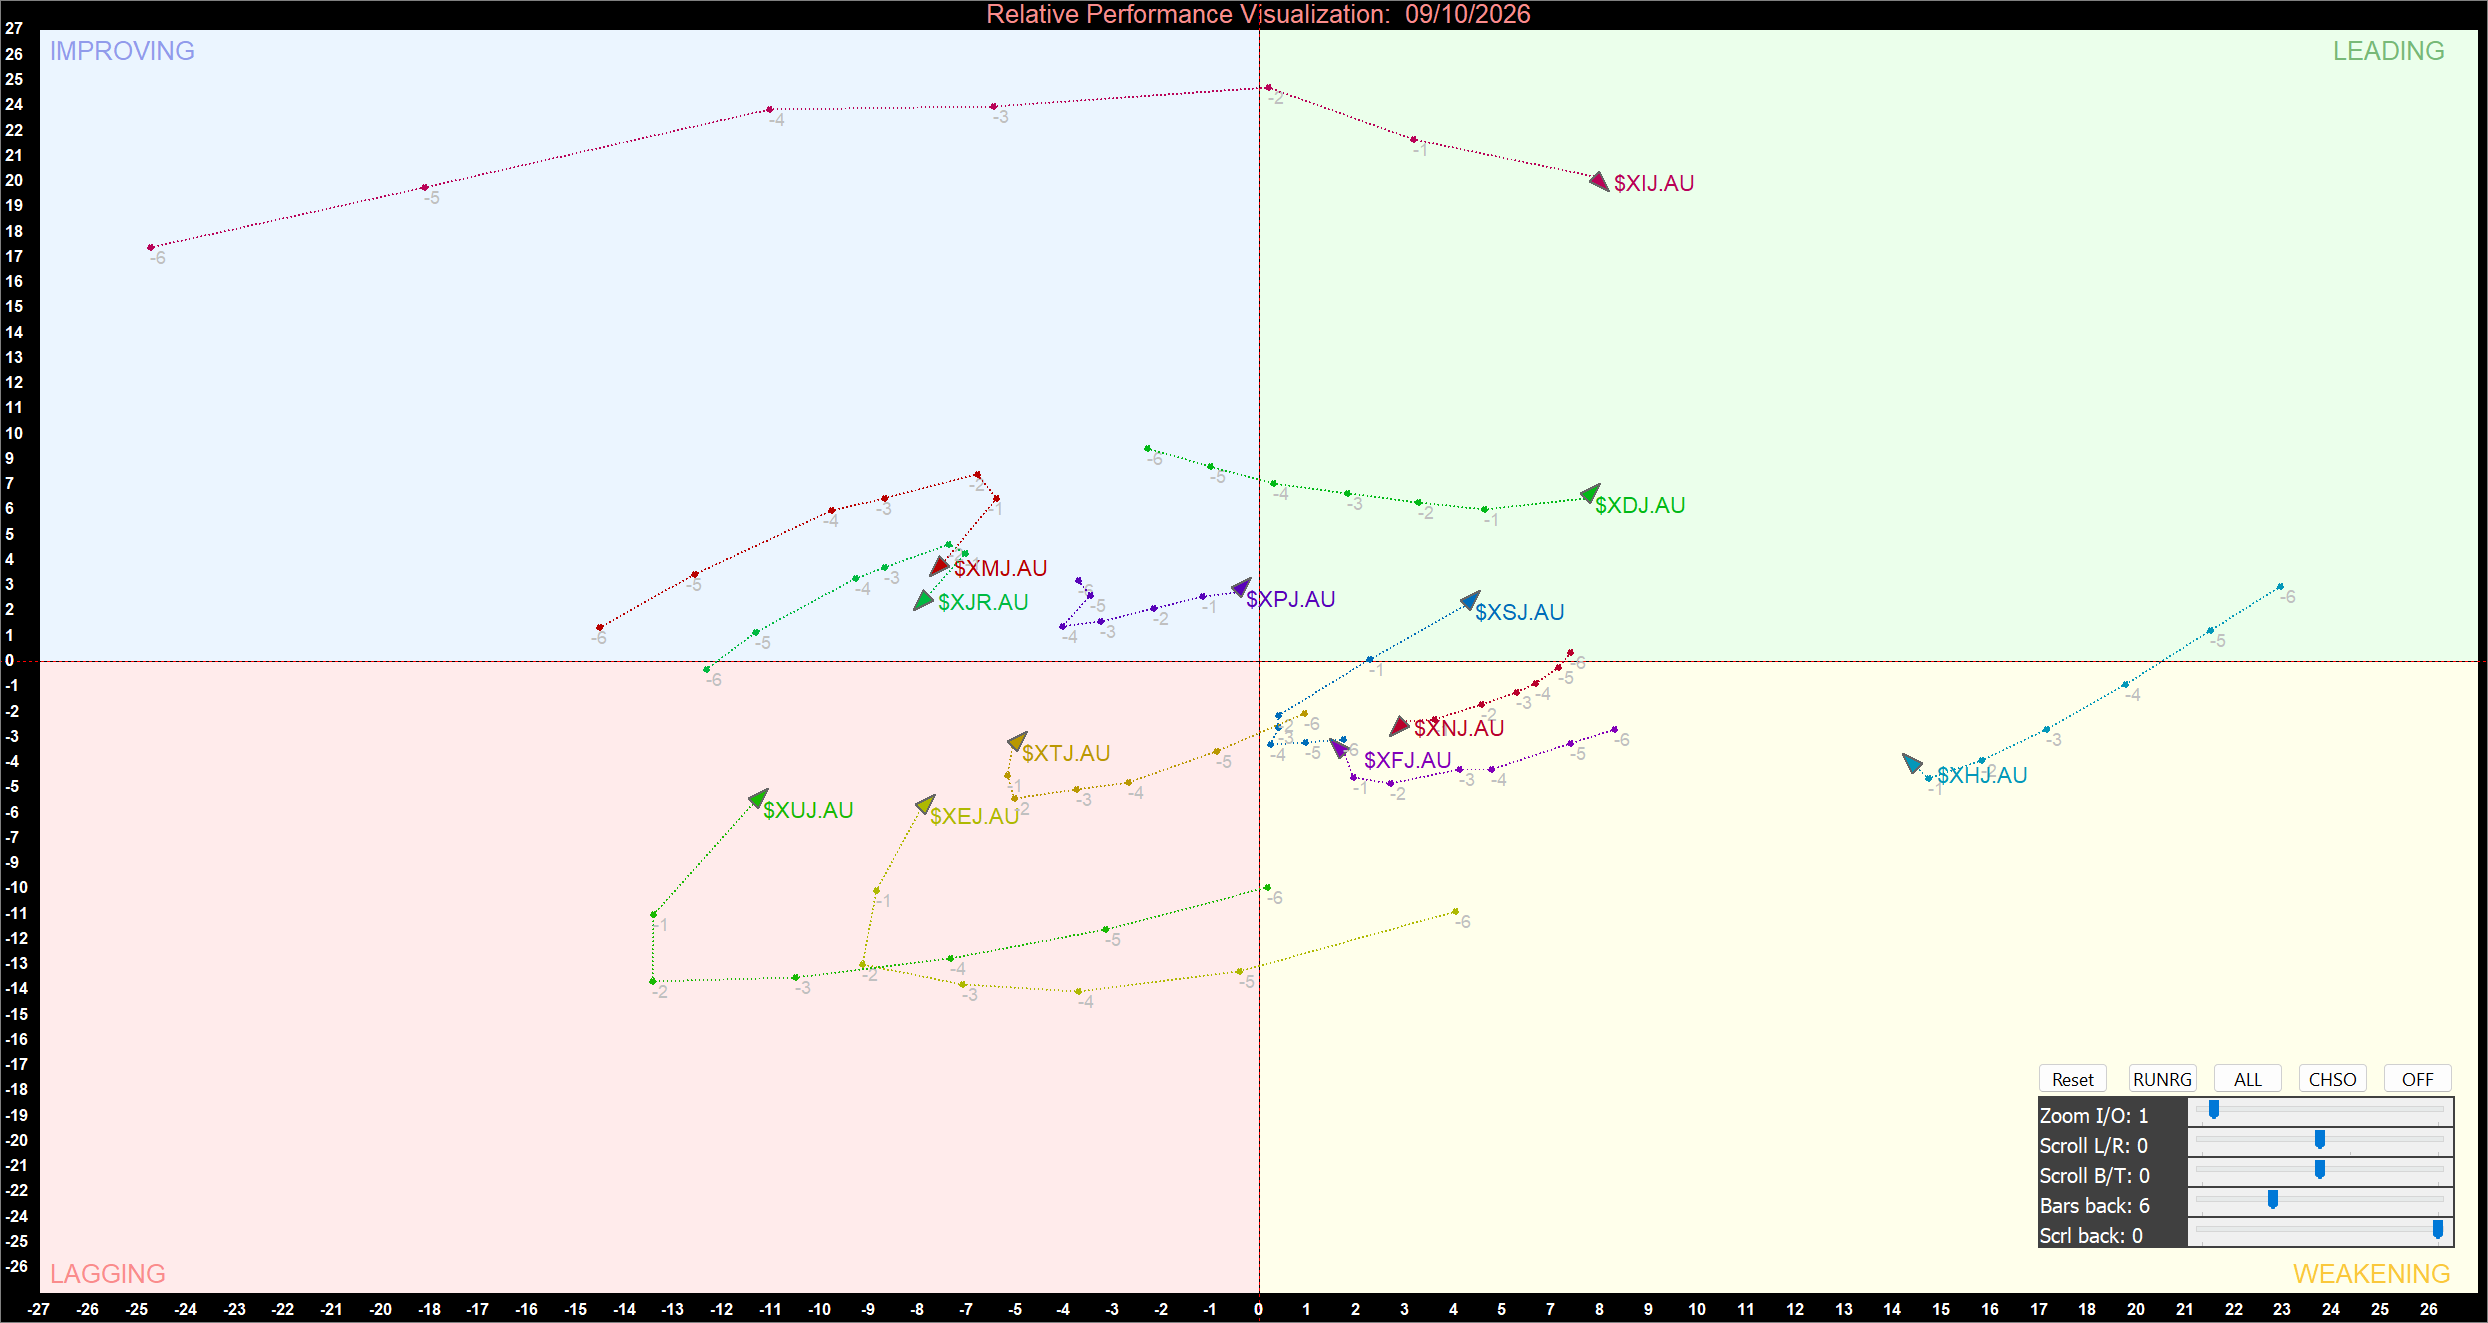
ASX Sector Relative Momentum Chart at the closing price of 09/10/2026. Powered by: amibroker.com
Technology, Consumer Discretionary and Consumer Staples Remain in Leading
Information Technology (XIJ), Consumer Discretionary (XDJ) and Consumer Staples (XSJ) were positioned in the Leading quadrant on the latest relative momentum chart. Their locations above the horizontal axis and to the right of the vertical axis indicate comparatively strong relative positioning and positive momentum.
Information Technology remained the strongest position on the chart, although its recent trajectory moved downward and to the right. This indicates that the sector continues to maintain a strong relative position, but its momentum has moderated from earlier observations. Continued downward movement would Warrant attention because a sustained deterioration could eventually lead to a transition into Weakening.
Consumer Discretionary also remained firmly in Leading, although its position was substantially closer to the horizontal centre line than that of Information Technology. Its recent trajectory indicates easing momentum, making the direction of subsequent observations important for determining whether its Leadership can be sustained.
Consumer Staples occupied the Leading quadrant with positive momentum and relative strength. Its position indicates that the sector retains a constructive momentum profile. However, continued movement toward the horizontal axis would suggest that its momentum advantage is diminishing.
The presence of three sectors in Leading demonstrates that leadership extends beyond technology, although the downward trajectories of some leading sectors indicate that momentum conditions are not uniformly strengthening.
Materials, Resources and Real Estate Show Improving Momentum
Materials (XMJ), Resources (XJR) and Real Estate (XPJ) were positioned in the Improving quadrant. Their locations above the horizontal axis but to the left of the vertical centre line indicate positive momentum alongside comparatively weaker relative strength.
Materials was positioned relatively high within Improving, suggesting a more constructive momentum reading than several other sectors in the quadrant. Its trajectory has advanced considerably from earlier observations, although recent movement suggests that the recovery is not entirely uninterrupted. Continued movement toward the vertical centre line would strengthen the case for a transition into Leading.
Resources was also positioned in Improving, with its trajectory indicating a recovery in relative momentum. Although the sector remains below the relative-strength threshold required for Leading, further movement toward the upper-right quadrant would indicate a more substantial improvement in its momentum profile.
Real Estate remained relatively close to the vertical centre line while maintaining positive momentum. Its Improving classification indicates that relative momentum has become more constructive, although the sector still needs to establish stronger relative positioning before entering Leading.
Together, these three sectors represent the principal areas of improving momentum. Their subsequent trajectories will help determine whether the current recovery develops into stronger relative leadership or loses momentum before crossing into the Leading quadrant.
Health Care, Industrials and Financials Remain in Weakening
Health Care (XHJ), Industrials (XNJ) and Financials (XFJ) were positioned in Weakening. Their locations to the right of the vertical axis but below the horizontal centre line indicate relatively stronger horizontal positioning accompanied by deteriorating momentum.
Health Care was positioned substantially farther to the right than most other sectors, suggesting that its relative position remains comparatively strong despite negative momentum. A recovery above the horizontal axis would be required to restore a more constructive momentum classification. Continued downward movement could increase the risk of a transition into Lagging.
Industrials remained relatively close to the centre of the chart, indicating that its momentum position could change if the trajectory turns upward or downward. A sustained recovery toward the horizontal axis would provide an early indication of stabilisation.
Financials also remained below the horizontal axis. Its trajectory suggests that momentum has weakened, and a sustained recovery toward the centre line would be necessary to improve its classification. Until then, the sector remains vulnerable to further relative momentum deterioration.
The Weakening group therefore requires close monitoring because its sectors retain positive relative positioning but have yet to demonstrate a convincing recovery in momentum.
Communication Services, Energy and Utilities Remain in Lagging
Communication Services (XTJ), Energy (XEJ) and Utilities (XUJ) remained in Lagging, with negative relative strength and negative momentum. Their positions indicate that these sectors continue to underperform on both dimensions of the chart.
Utilities and Energy remained relatively deep within the lower-left area, although their trajectories show some recovery from earlier observations. Sustained upward movement would be necessary before either sector could transition into Improving.
Communication Services was positioned closer to the centre of the chart than the other two Lagging sectors. This suggests that a recovery in relative momentum could bring it closer to a quadrant transition, although its current position does not yet confirm such a change.
The Lagging group remains an important area to monitor. A sustained upward trajectory would signal an improvement in relative momentum, while renewed downward movement would reinforce the sectors' weaker classifications.
Momentum Rotation Remains Selective
The current quadrant structure demonstrates that sector momentum remains uneven across the Australian Equity market. Information Technology, Consumer Discretionary and Consumer Staples retain Leading classifications, while Materials, Resources and Real Estate are attempting to strengthen their relative momentum.
At the same time, the three sectors in Weakening indicate that relatively strong positioning does not necessarily guarantee sustained momentum. Communication Services, Energy and Utilities remain under pressure on both relative strength and momentum.
The distinction between momentum and daily price performance is important when interpreting the chart. A positive daily return does not automatically place a sector in Leading, just as a negative daily return does not necessarily prevent a sector from occupying Improving. The quadrant classification reflects the sector's relative momentum structure rather than its latest daily percentage change.
Bottom Line
The ASX sector momentum structure on 9 October 2026 continues to favour selective leadership rather than a broad-based improvement. Information Technology remains the strongest relative momentum position, while Consumer Discretionary and Consumer Staples also occupy Leading.
Materials, Resources and Real Estate are the principal sectors to monitor for further improvement, particularly if their trajectories continue toward the Leading quadrant. Conversely, Health Care, Industrials and Financials require momentum stabilisation, while Communication Services, Energy and Utilities need more sustained recovery signals to move out of Lagging.
Overall, the chart indicates ongoing sector rotation, with the direction of each sector's trajectory remaining more important than its current quadrant alone. Continued movement toward the upper-right area would strengthen the momentum outlook, whereas a sustained decline toward the lower half of the chart would signal further deterioration.


 Nov 12, 2026





 Please wait processing your request...