
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Information Technology (XIJ), Consumer Discretionary (XDJ) and Consumer Staples (XSJ) are positioned in the Leading quadrant.
- Materials (XMJ), Resources (XJR) and Real Estate (XPJ) are positioned in Improving.
- Industrials (XNJ), Financials (XFJ) and Health Care (XHJ) are positioned in Weakening.
- Communication Services (XTJ), Energy (XEJ) and Utilities (XUJ) remain in Lagging.
- The momentum structure shows a relatively balanced rotation, with three sectors positioned in each of the Improving, Weakening and Lagging quadrants.
- XIJ remains the strongest relative momentum position on the chart, while XDJ and XSJ also maintain positive momentum characteristics.
- XMJ, XJR and XPJ continue to show improving relative momentum and represent the main sectors attempting to transition toward stronger leadership.
- XHJ, XNJ and XFJ are experiencing momentum deterioration despite retaining varying degrees of relative positioning.
- The current configuration indicates selective sector Leadership rather than a broad-based improvement in momentum.
The ASX sector momentum structure on 8 October 2026 remained mixed, with Information Technology, Consumer Discretionary and Consumer Staples positioned in Leading while Materials, Resources and Real Estate remained in Improving. Industrials, Financials and Health Care were positioned in Weakening, while Communication Services, Energy and Utilities remained in Lagging. The configuration indicates that relative momentum continues to favour selected sectors, while several previously stronger areas are experiencing deterioration.
ASX Sector Momentum Quadrants
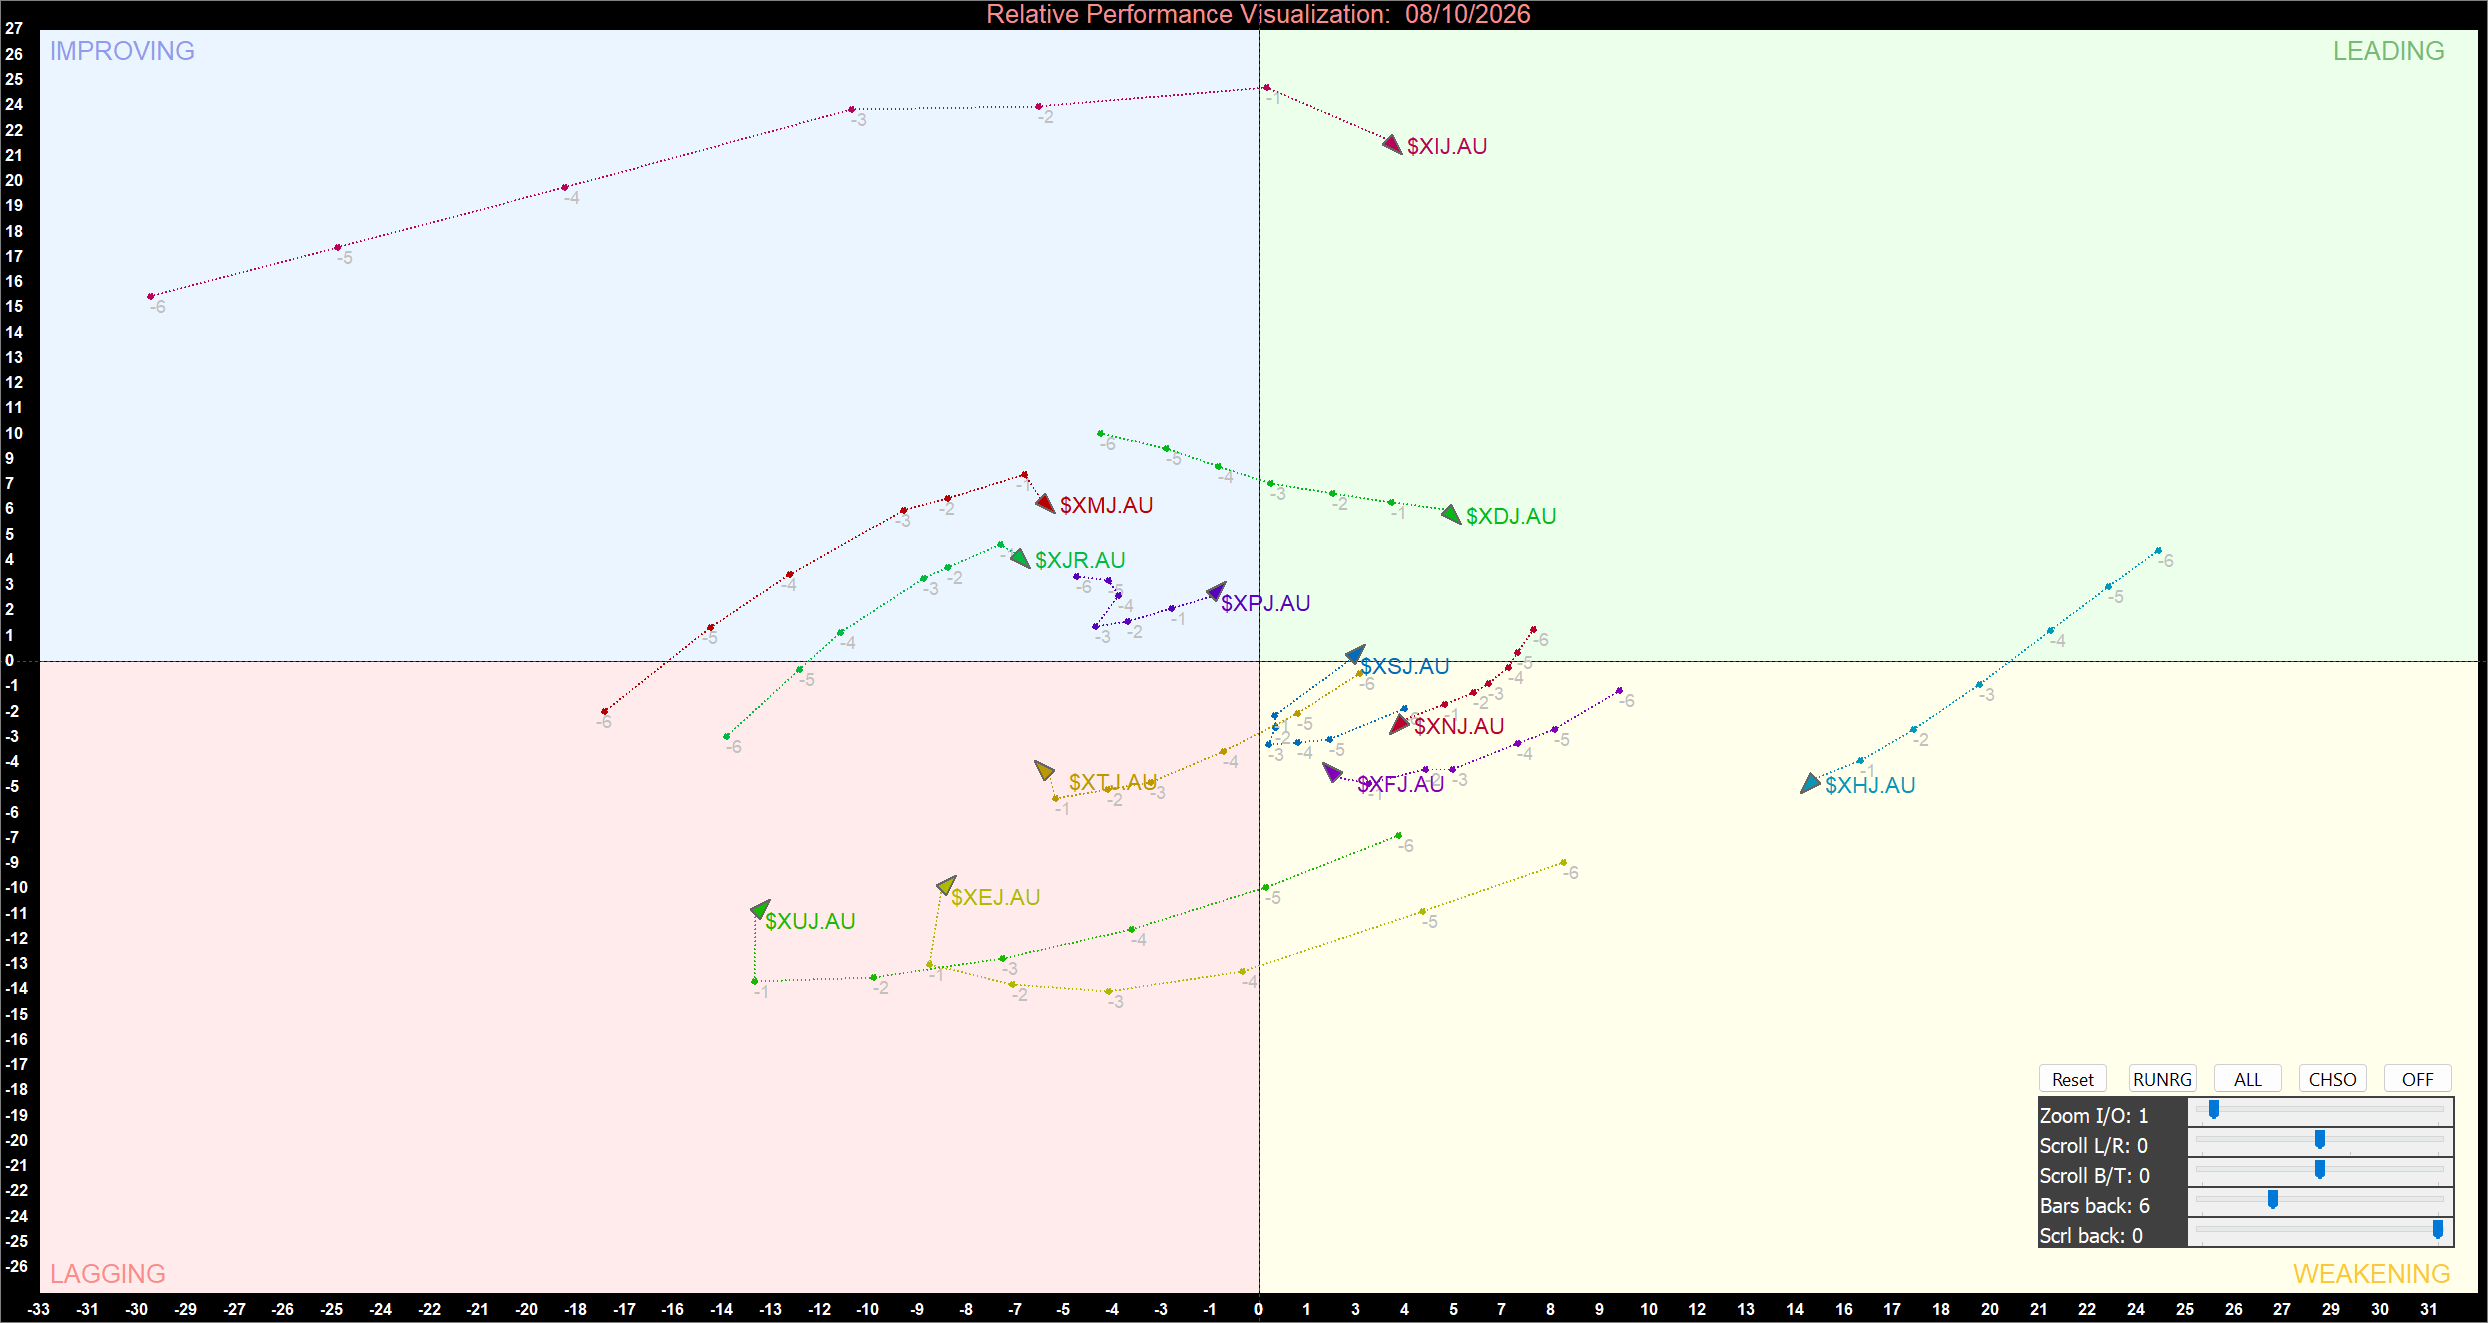 ASX Sector Relative Momentum Chart at the closing price of 08/10/2026. Powered by: amibroker.com
Technology, Consumer Discretionary and Consumer Staples Lead
Information Technology (XIJ), Consumer Discretionary (XDJ) and Consumer Staples (XSJ) were positioned in the Leading quadrant on the latest relative momentum chart. Their locations indicate that these sectors continue to combine relatively strong positioning with positive momentum characteristics.
XIJ remained the strongest position on the chart, sitting well inside the upper-right Leading area. Its trajectory shows sustained relative momentum and a clear separation from most other sectors. The position suggests that Information Technology continues to maintain the most constructive momentum structure within the current ASX sector configuration.
Consumer Discretionary was also positioned firmly within Leading, although considerably closer to the centre of the chart than XIJ. Its position continues to indicate positive momentum, with further movement toward the upper-right area likely to strengthen the confirmation of sustained leadership.
Consumer Staples moved into the Leading area near the horizontal centre line. Its position indicates that momentum has improved sufficiently to move above the Leading threshold, although its relatively central location means that continued upward movement would be required to establish stronger leadership.
The presence of three sectors in Leading indicates that momentum leadership has broadened slightly, although the strongest momentum remains concentrated in a limited number of sectors.
Materials, Resources and Real Estate Remain in Improving
Materials (XMJ), Resources (XJR) and Real Estate (XPJ) remained positioned in the Improving quadrant. Their locations indicate that relative momentum is strengthening, although these sectors have not yet established the combination of relative strength and momentum required for a Leading classification.
Materials was positioned relatively high within Improving, making it one of the more advanced sectors in this quadrant. Its trajectory suggests that momentum remains constructive, and continued movement toward the vertical centre line would increase the possibility of a transition into Leading.
Resources also remained in Improving, with its trajectory indicating a recovery in relative momentum. The sector is still below the Leading threshold, but continued upward movement would strengthen its momentum profile and increase the likelihood of further improvement.
Real Estate was positioned closer to the centre of the chart. Its Improving classification indicates that momentum is becoming more constructive, although a sustained move into the upper-right quadrant would be required to confirm a transition toward stronger leadership.
Health Care, Industrials and Financials Move Into Weakening
Health Care (XHJ), Industrials (XNJ) and Financials (XFJ) were positioned in the Weakening quadrant. Their locations indicate that these sectors retain varying degrees of relative positioning but are experiencing negative momentum.
Health Care was positioned significantly to the right while remaining below the horizontal centre line. This indicates relatively strong positioning on the horizontal dimension but deteriorating momentum. Its location suggests that continued downward movement could eventually result in a transition toward Lagging.
Industrials was positioned closer to the centre of the chart but remained below the horizontal axis. The negative vertical position indicates that momentum has weakened, and a recovery toward the centre line would be necessary to stabilise the sector's classification.
Financials remained in Weakening, with its position below the horizontal axis indicating persistent negative momentum. The sector would need to reverse its current trajectory and move back toward the centre line before a more constructive momentum signal could develop.
Communication Services, Energy and Utilities Remain in Lagging
Communication Services (XTJ), Energy (XEJ) and Utilities (XUJ) remained in the Lagging quadrant. Their positions indicate that both relative positioning and momentum remain comparatively weak.
Energy and Utilities were positioned relatively deep within the Lagging area, suggesting more persistent momentum pressure. Their trajectories would need to turn materially higher before a transition into Improving becomes likely.
Communication Services remained closer to the centre of the chart than Energy and Utilities. This gives the sector greater potential to improve if its trajectory turns upward, although it has not yet generated sufficient positive momentum to cross into Improving.
The Lagging group therefore remains an important part of the current momentum structure. A sustained upward movement from these sectors would provide evidence that broader sector rotation is becoming more constructive.
Momentum Rotation Remains Uneven
The latest quadrant structure demonstrates that momentum leadership remains selective across the ASX. Three sectors are positioned in Leading, three in Improving, three in Weakening and three in Lagging, creating a relatively balanced distribution across the four quadrants.
The most constructive configuration remains concentrated in Information Technology, Consumer Discretionary and Consumer Staples. Their Leading positions indicate that positive momentum is currently strongest within these sectors.
Conversely, Health Care, Industrials and Financials are losing momentum despite retaining varying degrees of relative positioning. Their trajectories will be important to monitor because continued deterioration could push these sectors further toward Lagging.
Materials, Resources and Real Estate remain the principal candidates for improving momentum. Their Improving classifications indicate that momentum is strengthening, although further movement toward Leading is required before they can be considered established leaders.
Bottom Line
The ASX sector momentum structure on 8 October 2026 remains characterised by selective leadership and uneven sector rotation. Information Technology (XIJ), Consumer Discretionary (XDJ) and Consumer Staples (XSJ) are positioned in Leading, while Materials (XMJ), Resources (XJR) and Real Estate (XPJ) form the Improving group.
Health Care (XHJ), Industrials (XNJ) and Financials (XFJ) are positioned in Weakening, while Communication Services (XTJ), Energy (XEJ) and Utilities (XUJ) remain in Lagging.
From a momentum perspective, Technology remains the clearest area of relative strength, while Consumer Discretionary and Consumer Staples have also established constructive positions. Materials, Resources and Real Estate remain the key sectors to monitor for further improvement, particularly if their trajectories continue toward the Leading quadrant.
Conversely, the three sectors in Weakening require momentum stabilisation before their outlook becomes more constructive. The overall configuration therefore continues to favour selective sector leadership rather than a broad-based momentum advance.


 Nov 12, 2026





 Please wait processing your request...