
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Consumer Discretionary (XDJ) remained the only sector in the Leading quadrant.
- Technology (XIJ), Materials (XMJ), Resources (XJR) and Real Estate (XPJ) were positioned in the Improving quadrant.
- Health Care (XHJ), Financials (XFJ), Industrials (XNJ) and Consumer Staples (XSJ) were positioned in the Weakening quadrant.
- Communication Services (XTJ), Utilities (XUJ) and Energy (XEJ) remained in the Lagging quadrant.
- Technology was positioned prominently in Improving despite recording the weakest daily performance among the sectors, falling 2.90%.
- Real Estate was also in Improving after gaining 1.14%, the strongest daily performance across the twelve sectors.
- Consumer Discretionary remained the strongest sector from a relative momentum perspective, while Technology, Materials, Resources and Real Estate showed improving trajectories.
- The momentum structure continues to indicate significant sector rotation rather than a uniform market trend.
The Australian Equity market displayed a strongly rotational sector structure on 6 October 2026, with the Relative Performance Visualization showing a clear separation between sectors maintaining relative strength and those experiencing deterioration. Consumer Discretionary remained the only sector in the Leading quadrant, while Technology, Materials, Resources and Real Estate were positioned in Improving. Health Care, Financials, Industrials and Consumer Staples were in Weakening, while Communication Services, Utilities and Energy remained in Lagging.
ASX Sector Momentum Quadrants
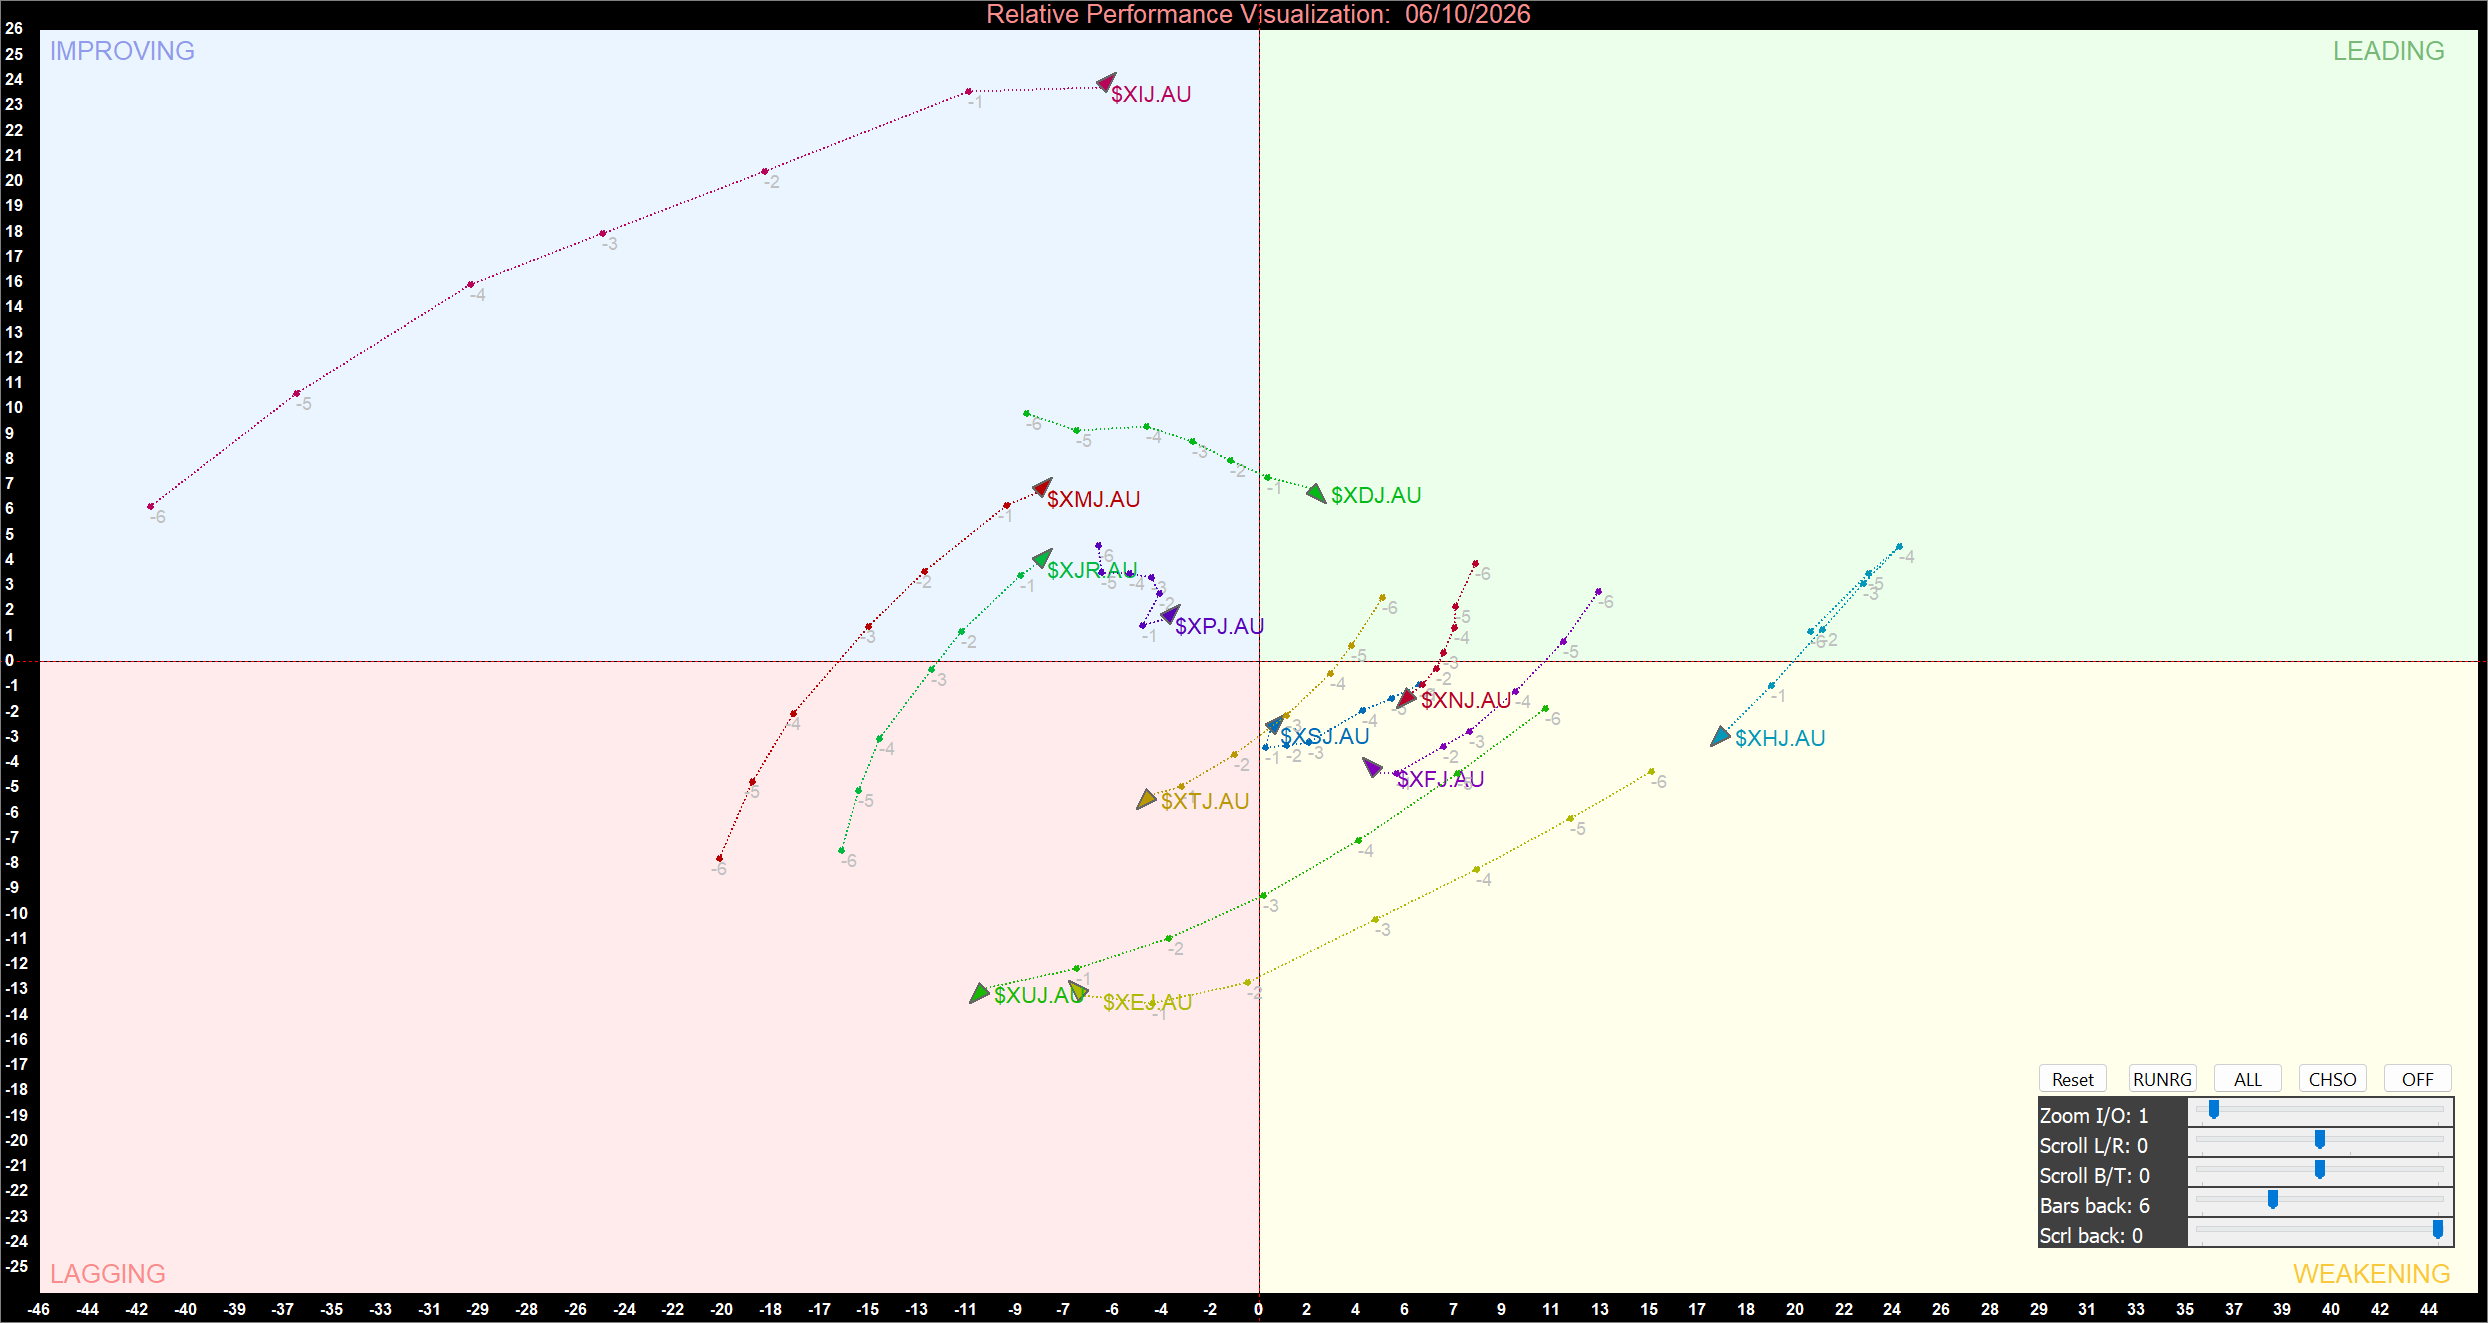
ASX Sector Relative Momentum Chart at the closing price of 06/10/2026. Powered by: amibroker.com
Consumer Discretionary Remains the Leading Sector
Consumer Discretionary was the only sector positioned in the Leading quadrant on the latest momentum chart. Its location indicates that the sector continues to maintain relatively strong performance and momentum compared with the broader sector universe.
The Leading classification is particularly important because it does not necessarily require a positive daily return. Instead, it reflects relative strength and momentum characteristics. Consumer Discretionary therefore remains the strongest sector from a momentum perspective, although the direction of its trajectory should continue to be monitored for signs of deterioration.
The sector gained 0.33% during the session, providing additional support for its Leading classification. Its position above the horizontal momentum boundary indicates that relative strength remains favourable.
Technology, Materials, Resources and Real Estate Show Improving Momentum
Technology, Materials, Resources and Real Estate were positioned in the Improving quadrant. Their trajectories indicate that relative momentum is strengthening compared with the broader sector universe, although they have not yet moved into the Leading area.
Technology was particularly notable because its momentum classification diverged sharply from its daily performance. The sector fell 2.90%, recording the weakest daily performance among all twelve sectors. Despite this substantial decline, Technology remained in Improving on the relative momentum chart.
This divergence highlights the importance of distinguishing daily returns from relative momentum. A sector can decline during a single session while still showing improving relative strength if its performance trajectory compares favourably with other sectors over the relevant momentum period.
Materials and Resources also remained in Improving, supported by daily gains of 0.91% and 0.84%, respectively. Their positions suggest that commodity-related sectors continue to develop stronger relative momentum and could become increasingly important if their trajectories continue towards the Leading quadrant.
Real Estate recorded the strongest daily performance at 1.14% and remained in Improving. Its position indicates that the sector's relative momentum has strengthened significantly, adding to the evidence of renewed interest in property-related stocks.
Health Care, Financials and Industrials Remain in Weakening
Health Care, Financials and Industrials were positioned in the Weakening quadrant. Their classification indicates that relative momentum has deteriorated even though some of these sectors recorded positive daily performances.
Health Care gained 0.63% during the session, while Financials advanced 0.73%. Industrials recorded a smaller gain of 0.05%. Nevertheless, all three remained below the horizontal axis separating Weakening from the more constructive Leading and Improving areas.
This contrast reinforces the distinction between short-term price performance and relative momentum. Positive daily returns do not automatically indicate improving momentum. The position and direction of the sector's trajectory provide additional information about whether its relative strength is improving or deteriorating.
Consumer Staples was also positioned in Weakening, despite its relatively small daily decline of 0.13%. Its location suggests that the sector remains vulnerable to further deterioration and could move deeper into Lagging if its relative momentum continues to weaken.
Communication Services, Utilities and Energy Remain Lagging
Communication Services, Utilities and Energy remained in the Lagging quadrant, making them the weakest group in the latest momentum structure.
Communication Services was positioned in the lower-left area of the chart, while Utilities and Energy were also below the horizontal boundary. Their positions indicate that relative strength remains weak and that these sectors have yet to demonstrate a convincing momentum recovery.
The three sectors also produced relatively modest daily movements. Communication Services gained 0.14%, Utilities rose 0.90% and Energy increased 0.15%. Utilities were particularly notable because the sector delivered one of the strongest daily gains but remained in Lagging.
This again demonstrates that a strong single-session performance does not necessarily mean that a sector's broader relative momentum has turned positive. A sustained improvement in trajectory would be required for these sectors to move first into Weakening and eventually into the more constructive quadrants.
Bottom Line
The ASX sector momentum structure on 6 October 2026 remained highly rotational rather than broadly bullish or bearish. Consumer Discretionary was the only sector in Leading, while Technology, Materials, Resources and Real Estate formed the Improving group.
The most notable feature was the divergence between daily performance and momentum classification. Technology fell 2.90% but remained in Improving, while Utilities gained 0.90% yet remained in Lagging. These differences demonstrate that the momentum chart captures relative performance over a broader period rather than simply ranking the latest daily returns.
Health Care, Financials, Industrials and Consumer Staples remained in Weakening, indicating that their relative momentum requires further improvement before their classifications become more constructive. Communication Services, Utilities and Energy remained the weakest sectors in Lagging.
From a momentum perspective, Technology, Materials, Resources and Real Estate are the key sectors to watch for further improvement, particularly if their trajectories continue moving towards the Leading quadrant. Consumer Discretionary remains the sector with the strongest relative momentum, while the Lagging group requires sustained improvement before a meaningful change in market leadership becomes evident.


 Nov 12, 2026





 Please wait processing your request...