
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Shifts
- Defensive Leaders Maintain Control: Health Care (XHJ) and Consumer Staples (XSJ) remain firmly positioned in the Leading quadrant, reflecting continued institutional preference for defensive sectors.
- Financials Enter Improving: Financials (XFJ) have crossed into the Improving quadrant, signaling strengthening relative momentum and the potential for a broader recovery.
- Real Estate Establishes Leadership: Real Estate (XPJ) has successfully entered the Leading quadrant, confirming a notable improvement in both relative strength and momentum.
- Resources Fall into Lagging: Resources (XJR) have deteriorated into the Lagging quadrant, highlighting persistent weakness across the mining and commodity complex.
The ASX sector rotation profile remained constructive on June 16, 2026, with leadership concentrated in a diverse mix of defensive and growth-oriented sectors. The latest Relative Rotation Graph (RRG) shows six sectors occupying the Leading quadrant, while Financials and Utilities continue to improve. At the same time, Resources have slipped into Lagging and Materials remain in Weakening, indicating ongoing challenges within the commodity space.
ASX Sector Momentum Summary
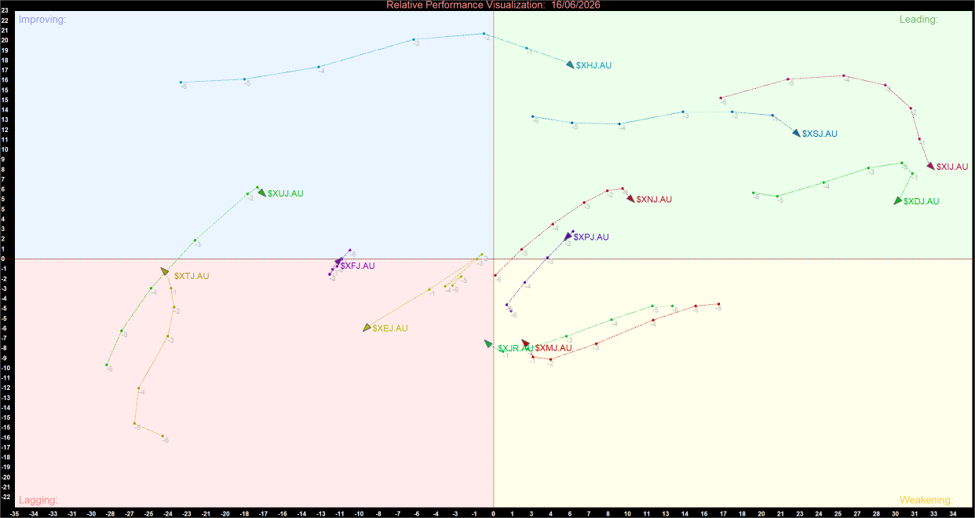
ASX Sector Relative Momentum Chart (at the closing price of 16/06/2026). Powered by: amibroker.com
Momentum Breakdown by Quadrant
The Leading Quadrant (Broadening Leadership)
- Health Care (XHJ) Remains the Strongest Leader: Health Care continues to occupy a commanding position within the Leading quadrant and remains one of the strongest sectors on the chart. Its combination of superior relative strength and positive momentum suggests ongoing institutional demand for defensive earnings stability.
- Consumer Staples (XSJ) Retains Defensive Leadership: Consumer Staples remain firmly established in the Leading quadrant. Although momentum has moderated slightly, the sector continues to outperform the broader market and remains a preferred destination for defensive capital.
- Technology and Consumer Discretionary Maintain Leadership: Information Technology (XIJ) and Consumer Discretionary (XDJ) continue to occupy Leading territory. Technology remains one of the market's strongest relative performers despite a recent loss of momentum, while Consumer Discretionary continues to build relative strength against the broader benchmark.
- Real Estate Joins the Leadership Group: One of the most important developments on the chart is the emergence of Real Estate (XPJ) as a Leading sector. Its transition from Improving into Leading reflects growing institutional confidence and broadens the market's leadership profile.
- Industrials Hold Their Ground: Industrials (XNJ) remain inside the Leading quadrant, although momentum has softened. Nevertheless, the sector continues to display superior relative strength and remains an important component of the market's leadership structure.
The Improving Quadrant (Emerging Opportunities)
- Financials Enter Recovery Mode: Financials (XFJ) have moved into the Improving quadrant, representing a significant positive rotational development. The sector's improving momentum suggests the recent period of underperformance may be ending, creating the potential for future leadership if relative strength continues to build.
- Utilities Continue Advancing: Utilities (XUJ) remain firmly positioned within Improving and continue to exhibit strengthening momentum. The sector appears to be moving steadily toward the Leading quadrant, reinforcing the defensive undertone evident across the broader market.
The Weakening Quadrant (Leadership Under Pressure)
- Materials Lose Momentum: Materials (XMJ) remain in the Weakening quadrant. Although relative strength is still above average, momentum has deteriorated noticeably. Continued weakness could eventually push the sector into Lagging if buyers fail to regain control.
The Lagging Quadrant (Persistent Underperformers)
- Resources Slip into Lagging: Resources (XJR) have entered the Lagging quadrant, marking one of the most significant deteriorations on the chart. The move indicates both weakening relative strength and negative momentum, confirming continued institutional selling pressure across the resource sector.
- Energy Remains Under Pressure: Despite leading daily sector performance, Energy (XEJ) remains in the Lagging quadrant. This divergence highlights the distinction between short-term price performance and longer-term relative momentum trends. The sector requires further improvement before it can challenge for leadership.
- Communication Services Continue to Struggle: Communication Services (XTJ) remain deeply embedded within the Lagging quadrant. Relative strength and momentum remain weak, indicating limited institutional interest compared with other sectors.
Strategic Summary
The June 16 RRG configuration presents a constructive but increasingly selective market environment. Leadership is concentrated among Health Care, Consumer Staples, Technology, Consumer Discretionary, Industrials, and Real Estate, while Utilities and Financials continue to improve.
Meanwhile, Resources have deteriorated into Lagging and Materials remain in Weakening, suggesting the commodity complex continues to face headwinds. Overall, the rotation profile supports a balanced market structure, with expanding leadership outside the resource sector and improving momentum emerging within Financials and Utilities.


 Nov 12, 2026





 Please wait processing your request...