
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Momentum Highlights
- Leadership Broadens Across Consumer and Industrial Sectors: Industrials (XIJ), Consumer Staples (XSJ), Consumer Discretionary (XDJ), Communication Services (XPJ), and Clean Energy (XNJ) remain firmly positioned in the Leading quadrant, reflecting strong relative strength and positive momentum.
- Health Care Emerges as the Strongest Improver: Health Care (XHJ) continues to advance within the Improving quadrant, displaying one of the strongest momentum profiles on the RRG and approaching leadership territory.
- Energy Re-Enters Recovery Mode: Energy (XEJ) has rotated into the Improving quadrant, indicating strengthening momentum and improving relative performance after a period of weakness.
- Financials and Technology Remain Structural Laggards: Financials (XFJ) and Information Technology (XTJ) continue to reside in the Lagging quadrant, suggesting institutional investors remain cautious toward both sectors despite recent stabilization attempts.
The Australian equity market continues to exhibit a rotation-driven structure, with leadership concentrated in consumer-oriented sectors and Industrials. The Relative Rotation Graph (RRG) for June 11, 2026, shows several sectors maintaining strong relative strength while a handful of lagging groups attempt to rebuild momentum.
At the same time, Health Care and Energy are showing increasingly constructive momentum characteristics, suggesting leadership breadth may continue to expand. The current market environment remains favourable for active sector allocation and selective positioning.
Sector Momentum and Trajectory Summary
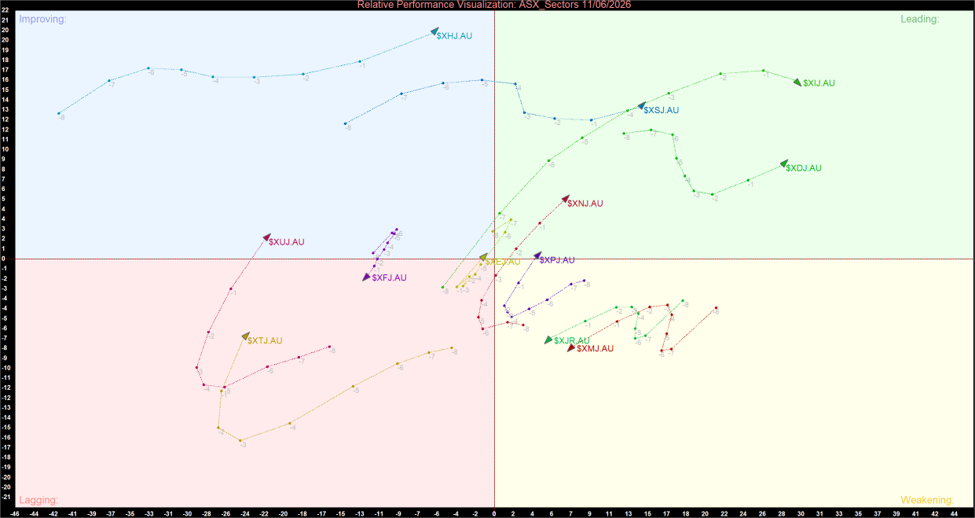
ASX Sector Relative Momentum Chart (at the closing price of 11/06/2026). Powered by: amibroker.com
Quantitative Momentum Themes
The Leading Quadrant (Institutional Leadership Zone)
Industrials (XIJ): Industrials remain one of the strongest sectors on the matrix, maintaining positive relative strength and momentum. Although momentum has moderated slightly, the sector continues to exhibit clear institutional sponsorship.
Consumer Staples (XSJ): Consumer Staples remain firmly positioned within the Leading quadrant. The sector continues to attract capital flows as investors favour earnings stability and defensive growth characteristics.
Consumer Discretionary (XDJ): Consumer Discretionary is maintaining a constructive North-East trajectory within the Leading quadrant, indicating strengthening momentum and continued investor confidence.
Communication Services (XPJ): Communication Services has successfully entered the Leading quadrant, signalling improving relative strength and growing institutional participation. The transition suggests the sector is becoming an increasingly important component of market leadership.
Clean Energy (XNJ): Clean Energy remains in the Leading quadrant and continues to display improving momentum. The sector's trajectory suggests investors are increasingly allocating capital toward renewable and energy-transition themes.
The Improving Quadrant (Emerging Recovery Candidates)
Health Care (XHJ): Health Care remains the strongest improving sector on the matrix. Its sharp North-East trajectory indicates accelerating momentum and increasing potential to rotate into the Leading quadrant in the near term.
Energy (XEJ): Energy has crossed into the Improving quadrant, suggesting relative momentum is strengthening. The sector appears to be recovering from previous weakness and may be developing into a future leadership candidate.
Utilities (XUJ): Utilities remain positioned within the Improving quadrant, reflecting improving momentum despite still exhibiting negative relative strength. The sector continues to attract selective institutional interest.
The Weakening Quadrant (Leadership Losing Momentum)
Materials (XMJ): Materials remain within the Weakening quadrant, indicating that positive relative strength is being accompanied by deteriorating momentum. Institutional buying interest appears to be moderating.
Real Estate (XJR): Real Estate also remains in the Weakening quadrant. While relative performance remains positive, weakening momentum suggests the sector may struggle to maintain its leadership characteristics without renewed buying interest.
The Lagging Quadrant (Structural Underperformers)
Financials (XFJ): Financials continue to reside within the Lagging quadrant despite showing modest momentum improvement. Relative strength remains weak, suggesting institutional conviction toward the sector remains limited.
Information Technology (XTJ): Technology remains one of the weakest sectors on the matrix. Although momentum has improved from deeply negative levels, the sector continues to lag the broader market on a relative basis.
Strategic Summary
The June 11 RRG structure confirms that the ASX remains in a selective, rotation-driven market environment. Leadership is concentrated in Industrials (XIJ), Consumer Staples (XSJ), Consumer Discretionary (XDJ), Communication Services (XPJ), and Clean Energy (XNJ), all of which continue to exhibit strong relative strength and positive momentum.
Meanwhile, Health Care (XHJ) and Energy (XEJ) are emerging as the most promising momentum improvers, suggesting leadership breadth may expand if current trends persist. In contrast, Financials (XFJ) and Technology (XTJ) remain the market's weakest sectors despite signs of stabilization.
Investors should continue focusing on established leaders and sectors exhibiting improving momentum while remaining cautious toward areas still trapped within the Lagging quadrant. The current market structure continues to favour active sector rotation and disciplined allocation strategies over broad market exposure.


 Nov 12, 2026





 Please wait processing your request...