
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Key Highlights
- Ampol is moving from a story of operational headwinds to one of strategic expansion and margin recovery.
- After a challenging 2024 defined by outages at the Lytton refinery, the company’s FY2025 results indicate a significant rebound.
- The Replacement Cost Operating Profit (RCOP) surged 83% to $429 million, signaling that the core business is stabilizing.
The market often overlooks the quiet accumulation phase of a cyclical recovery, but for Ampol Limited (ASX:ALD), the technical and fundamental signals are beginning to align in a way that suggests the tide has turned.
A Potential Turnaround Story
The recovery is underpinned by the Lytton refinery returning to consistent profitability, capturing higher margins of US$8.13 per barrel in early 2026. Beyond refining, the company is pivoting toward a high-margin Convenience Retail model, focusing on food and coffee sales rather than just fuel volume. The pending $1.1 billion acquisition of EG Australia remains a primary catalyst, as it would significantly expand Ampol's retail footprint and accelerate its "U-GO" unstaffed brand rollout.
Associated Risks
The turnaround is not without its hurdles, particularly regarding the slim net margins of 0.3% which leave the company sensitive to global oil price volatility. Additionally, the ACCC continues to scrutinize the EG Australia deal, with a final decision expected in June 2026. Investors should also monitor dividend sustainability, as current payouts are stretching free cash flow during this capital-intensive transition phase.
Technical Outlook
Mirroring the fundamental recovery, ALD's price action exhibits a developing inverse head and shoulders, with a confirmed breakout still pending.
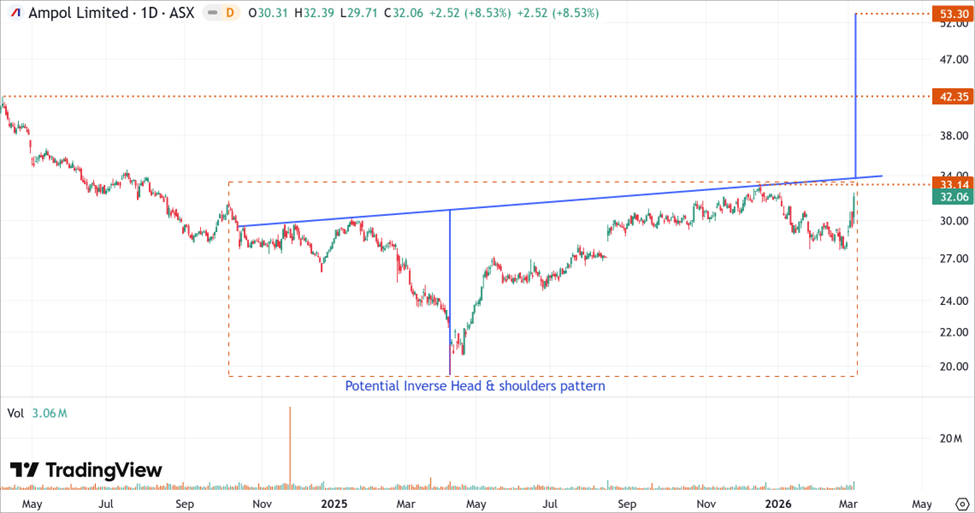
ALD’s Daily Price Chart (at the closing price of 05th March 2026). Powered by: tradingview.com
- On the daily chart, a "Potential Inverse Head & Shoulders" has been developing since late 2024, signaling a classic trend reversal.
- The neckline sits at $34.00; a decisive breakout above this level would complete the pattern and validate the fundamental turnaround story.
- Upon a successful breach of the neckline, the formation projects a long-term technical target of $53.30.
Bottom Line
Ampol presents a compelling turnaround case where improving operational reliability at Lytton meets a transformative retail expansion. While regulatory decisions and tight margins remain the primary "wait-and-see" factors, the confluence of an 83% jump in RCOP and a massive technical base suggests that the risk-reward profile is skewing to the upside for patient investors.


 Nov 12, 2026





 Please wait processing your request...