
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Company Overview
ALS Ltd is a global provider of testing, inspection, and certification services, operating across minerals, life sciences, environmental, and industrial testing segments. Headquartered in Brisbane, ALS runs over 450 laboratories in more than 65 countries, making it one of the largest and most geographically diversified testing companies in the world. The company's minerals testing division serves Mining companies globally, benefiting from increased exploration activity tied to the green energy metals boom. The life sciences and environmental divisions provide Diversification and growth in non-mining segments. ALS is a mission-critical service provider - its testing certifications are often legally required, creating sticky, Recurring Revenue.
Fundamental Insights
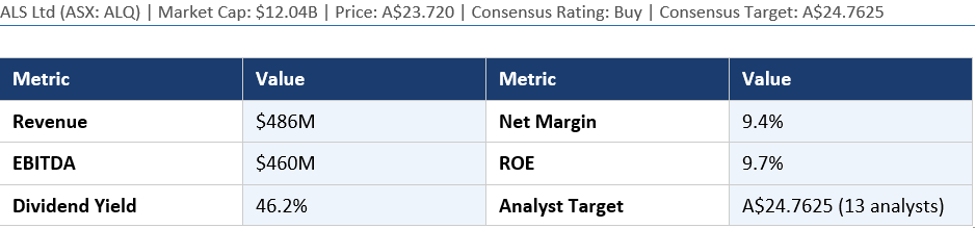
ALS delivers exceptional top-line momentum, with revenue growing 18.6% to $486 million and EBITDA surging 44.7% to $460 million - a standout growth print that reflects both Volume growth and Margin expansion. Net margin of 9.4% and revenue growth of 10.7% on an adjusted basis confirm broad-based strength. The company's ROE of 9.7% is modest but improving, and gross margin of 8.1% reflects the labour-intensive nature of laboratory services. The extraordinary headline Dividend Yield of 46.2% requires investor scrutiny - this level is almost certainly not sustainable on a recurring basis and may reflect special dividends or a one-time Capital return in the reporting period. EBITDA margin of 2.2% on an adjusted basis may reflect different segmental reporting.
Broker Views and Analyst Consensus
ALS has the equal-highest analyst coverage in this peer group alongside Macquarie, with 13 analysts unanimously rating it Buy. The consensus target of $24.76 implies 4.4% upside from the current $23.72. Despite the narrow headline upside, the breadth of broker conviction signals institutional confidence in the structural Earnings growth story. Key buy arguments centre on the global minerals exploration cycle driven by copper, gold, and lithium Demand, the scalable lab network, and ALS's pricing power in regulated testing markets. Analysts also highlight the life sciences growth optionality as a re-rating catalyst.
Technical Analysis
ALQ at $23.72 is within 4.4% of the consensus analyst target of $24.76, reflecting a market that has largely priced in the near-term fundamental upgrade cycle. The stock's extraordinary 378.4% historical return cements its Blue-Chip industrial status. Technically, $23.00-$23.20 represents key near-term support, while a break above $25.00 would open the path toward $27-$28. RSI is elevated but not extreme for a stock in a strong fundamental uptrend. Volume has been consistent, suggesting institutional buying rather than speculative flows.
Investor Action Points
ALS is a high-quality industrial compounder and a core holding for investors seeking global diversification through an ASX-listed company. At current prices, the entry point is reasonable but not deeply discounted versus broker targets. Investors should confirm the sustainability of the dividend yield by examining the company's cash generation and payout policy. The 44.7% EBITDA growth rate makes this a momentum play as well as a value story. Hold and initiate on pullbacks toward $22.50-$23.00 for optimal Risk-adjusted entry point could be one of the strategies.
Disclaimer: This article is for informational purposes only and does not constitute financial advice. Investors should conduct their own Due Diligence and consult a licensed financial adviser before making Investment decisions. Past performance is not indicative of future results.


 Nov 12, 2026





 Please wait processing your request...