
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
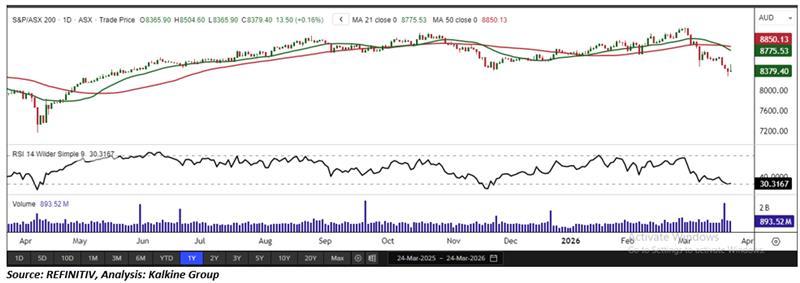
Index Update: The S&P/ASX 200 closed higher on Tuesday, gaining 13.50 points or 0.16% to finish at 8,379.40, after earlier touching a new 100-day low. Despite the daily gain, the index remains under pressure, down 2.73% over the past five sessions and 3.84% year to date. Sector performance was mixed, with more sectors declining than advancing. Materials led the market, rising 2.87% and rebounding from recent losses, although the sector is still down 5.55% over the past five days. The broader market showed weakness across several sectors. Financials posted the sharpest decline at -1.30%, followed by Information Technology (-1.56%), Health Care (-0.80%), and Energy (-0.42%). Consumer Discretionary (-0.18%) and Consumer Staples (-0.10%) also edged lower.On the positive side, Utilities rose 1.22%, while A-REITs gained 0.72% and Industrials added 0.38%, helping offset broader sectoral weakness.
Macro Update: The US–Israel conflict with Iran is sending shockwaves through the global economy, fuelling concerns of renewed inflationary pressure that could force policymakers to raise borrowing costs. A major disruption has emerged in the Strait of Hormuz, through which roughly one-fifth of the world’s oil and gas supply flows, effectively constraining global energy movement. Iran has warned it may target vessels attempting to pass without approval, heightening tensions. Oil markets have reacted sharply, with Brent crude surging to as high as USD 119.50 per barrel on March 9, its highest level since 2022.
Top Market Movers: Top gainers were Genesis Minerals Limited (ASX:GMD), rising AUD 0.370 or 6.915% to AUD 5.720, followed by PLS Group Limited (ASX:PLS), up AUD 0.280 or 6.572% to AUD 4.540, and Liontown Limited (ASX:LTR), gaining AUD 0.095 or 6.529% to AUD 1.550. Among losers, DroneShield Limited (ASX:DRO) fell AUD 0.260 or 6.789% to AUD 3.570, Guzman y Gomez Limited (ASX:GYG) declined AUD 0.840 or 4.859% to AUD 16.450, while National Australia Bank Limited (ASX:NAB) dropped AUD 1.990 or 4.448% to AUD 42.750.
Commodity Update: The U.S. dollar weakened at the start of the week, extending losses after President Donald Trump delayed a planned strike on Iran’s power grid, easing fears of a prolonged conflict. Gold declined 1.10% to USD 4,390.60, silver fell 2.73% to USD 67.42, and copper slipped 1.11% to USD 12,049.70. Meanwhile, Brent crude surged 4.18% to USD 99.92 as Iran denied ongoing talks with the U.S. despite deal optimism.
Our Stance: The S&P/ASX 200 posted a modest rebound, but underlying weakness persists as broader sector declines and recent losses highlight fragile sentiment. Strength in Materials offered some support, while Financials and Technology weighed on the index. Meanwhile, escalating tensions around the Strait of Hormuz and volatility in Brent crude are adding macro uncertainty, with inflation risks back in focus. Despite selective stock gains, the market outlook remains cautious, as geopolitical risks and commodity swings continue to cloud near-term direction and investor confidence.
In its latest session, the S&P/ASX 200 edged higher by a marginal 13.50 points, forming a small bullish candlestick. However, the decline in trading volume during this upward move reflects heightened investor caution and points to underlying weakness in near-term market sentiment. From a technical perspective, the index continues to trade below its 21-period Simple Moving Average (SMA) on the daily chart, which is acting as a key resistance level and capping upside attempts. Unless the index reclaims this barrier, bullish momentum is likely to remain constrained. On the downside, immediate support is seen near the 8,270 level, which will be crucial to hold in order to stabilise sentiment and limit the risk of a deeper correction.


 Nov 12, 2026





 Please wait processing your request...