
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
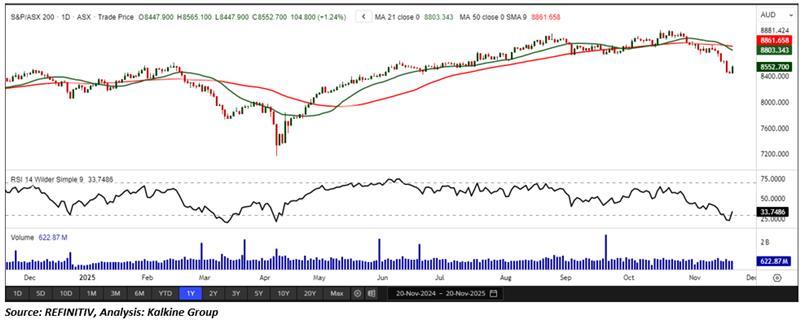
Index Update: The S&P/ASX 200 finished higher on Thursday, rising 104.80 points or 1.24% to close at 8,552.70, moving back above its 200-day moving average. Despite the latest rebound, the index remains down 2.29% over the past five sessions, though it is still up 4.82% year to date. Sector performance was broadly positive, with nine of eleven groups advancing. Materials led the market with a +2.45% gain, recovering from recent weakness that left the sector down 1.51% over the past week. Information Technology also posted a rise of +2.36%, while A-REITs, Financials, Consumer Discretionary, Industrials, Consumer Staples, Health Care, and Telecommunications Services all ended in the green. Utilities fell –1.27%, and Energy slipped –0.35%, marking the only two sectors that declined for the day.
Macro Update: Gold prices slipped on Thursday, pressured by a firmer dollar and fading expectations of a Federal Reserve rate cut in December, as investors awaited a delayed U.S. jobs report. Spot gold dipped 0.1% to USD 4,077.82 per ounce at 04:49 GMT, while U.S. gold futures for December delivery fell 0.2% to USD 4,076.50. The dollar index climbed to a more than two-week high, adding to the metal’s decline. As per Reuters, Fed minutes from October signalled caution over cutting rates, with market participants now assigning nearly a 33% probability of a December move, down from 49% a day earlier.
Top Market Movers: BLOCK, Inc. (ASX:XYZ) led the gainers on Thursday, rising AUD 9.650 or 10.902% to AUD 98.160. Liontown Resources (ASX:LTR) followed with a AUD 0.140 increase, up 9.556% to AUD 1.605, while Pinnacle Investment Management (ASX:PNI) advanced AUD 1.090 or 6.795% to AUD 17.130. On the downside, GQG Partners (ASX:GQG) fell 4.924%, DroneShield (ASX:DRO) slipped 4.061%, and Worley (ASX:WOR) declined 3.151%.
Commodity Update: The U.S. dollar held steady in early Asian trade on Thursday as investors awaited key payroll data and reassessed expectations of Fed rate cuts. Gold dipped 0.15% to USD 4,076.90, while silver rose 0.68% to USD 51.20 and copper edged up 0.23% to USD 10,782.05. Brent crude gained 0.30% to USD 63.71 following a sharp drop in U.S. inventories, amid reports of a potential new U.S.–Russia peace plan for Ukraine.
Our Stance: Thursday’s rebound in the S&P/ASX 200 signals improving sentiment, but the short-term trend remains uncertain given the index’s recent five-day decline and mixed macro signals. Sector breadth was encouraging, with leadership from Materials and Technology, yet caution persists as gold’s dip and a stronger dollar reflect shifting expectations around Fed policy. Market moves in top gainers and losers show selective risk-taking rather than broad conviction. Commodities offered a mixed picture, suggesting investors are waiting for clearer cues from U.S. payroll data and central bank signals before committing to a sustained direction.
In its latest session, the S&P/ASX 200 Index climbed 104.80 points to close at 8,552.70, supported by a bullish candlestick formation and strong trading volumes—both signaling sustained investor confidence. On the daily chart, the index continues to trade below its 50-period Simple Moving Average (SMA), which currently serves as a dynamic resistance level. A key support zone lies near 8,500, and holding above this area remains crucial for preserving the prevailing bullish structure. Sustained support at this level would enable the index to consolidate recent gains and reinforce confidence in the broader upward trajectory. From a weekly perspective, the index remains positioned above its 50-period SMA, further highlighting a constructive longer-term outlook. Overall, the technical setup points to the potential for continued upward momentum, provided near-term support levels remain intact.


 Nov 12, 2026





 Please wait processing your request...