
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
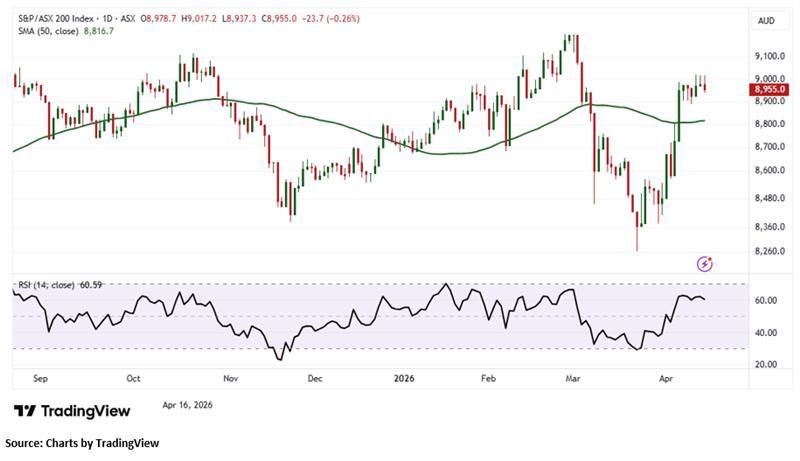
index Update: The S&P/ASX 200 ended Thursday’s session lower, declining 23.70 points or 0.26% to close at 8,955.00. Over the past five sessions, the benchmark index has remained broadly flat and currently sits 2.69% below its 52-week high. The move came amid continued reassessment of macro conditions, particularly following resilient domestic employment data that has kept the possibility of a May Interest Rate increase in focus.
Sector performance was mixed, with six of the eleven sectors finishing in negative territory. Information Technology emerged as the standout performer, rising 7.38% on the day and extending its five-day gain to 9.55%, indicating a rebound in the sector after recent declines.
Macro Update: Australia’s labour market showed relative stability in March, with the seasonally adjusted Unemployment rate holding steady at 4.3%, according to data released by the Australian Bureau of Statistics.
Employment increased modestly during the month, with 18,000 additional people entering the workforce, while the number of unemployed declined by 4,000. Despite these gains, the participation rate edged lower by 0.1 percentage points to 66.8%.
The expansion in employment was primarily driven by full-time roles, which rose by 53,000 positions. This was partially offset by a decline in part-time employment, which fell by 35,000. Full-time Job Growth was recorded across both genders, with male employment increasing by 29,000 and female employment by 24,000. Meanwhile, part-time employment declined for both males and females, down 19,000 and 16,000, respectively.
Top Market Movers: Among the top gainers, Life360 Inc. (ASX:360) rose to AUD 21.310, up AUD 2.360 (12.45%), while WiseTech Global Limited (ASX:WTC) gained AUD 4.940 (12.36%) to AUD 44.900. Zip Co Limited (ASX:ZIP) advanced AUD 0.210 (11.41%) to AUD 2.050. On the downside, Reece Limited (ASX:REH) fell AUD 0.730 (5.27%) to AUD 13.130, Newmont Corporation (ASX:NEM) declined AUD 8.370 (5.06%) to AUD 157.050, and James Hardie Industries plc (ASX:JHX) dropped AUD 1.250 (4.27%) to AUD 28.000.
Commodity Update: On Thursday, the U.S. dollar remained close to its weakest level since early March against major currencies as optimism over a possible peace agreement between the United States and Iran improved market sentiment and reduced Demand for safe-haven Assets. Gold rose 0.45% to USD 4,846.15 per ounce, silver climbed 1.09% to USD 80.50, and copper advanced 0.19% to USD 13,312.70. Meanwhile, Brent Crude slipped 0.09% to USD 94.83 per barrel.
Our Stance: The S&P/ASX 200 closed 0.26% lower at 8,955.00, remaining broadly flat over five sessions and 2.69% below its 52-week high, as investors weighed resilient labour data and Interest Rate expectations. Sector performance was mixed, with Information Technology rebounding strongly. Data from the Australian Bureau of Statistics showed Unemployment steady at 4.3%, with full-time Job Growth offsetting part-time declines. Market movers reflected this divergence, while commodities traded mixed amid softer safe-haven Demand. Overall, the session suggests cautious positioning, with markets balancing macro resilience against tightening policy risks in the near term.
The S&P/ASX 200 declined by 23.70 points in the latest session, forming a bearish candlestick that reflects mild profit booking. Despite this, the index continues to trade above its 21-period Simple Moving Average (SMA), which is acting as a key dynamic support and helping maintain the broader positive structure. Holding above this level is likely to support near-term stability and cushion downside risks. However, immediate support is seen near the 8,870.50 level. A decisive break below this zone could weaken sentiment and trigger a deeper corrective phase, potentially increasing Volatility and leading to more cautious investor positioning in the near term.


 Nov 12, 2026





 Please wait processing your request...