
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 slipped 19.30 points, or 0.22%, to close at 8,799.50 on Wednesday, marking a modest pullback. The benchmark remains 3.46% below its 52-week high, reflecting mixed investor sentiment. Despite the overall decline, six of eleven sectors advanced, led by Consumer Staples, which gained +1.05% for the day and +1.97% over the past week. Energy (+1.03%) and Materials (+0.86%) also posted solid gains, while Information Technology (-3.29%) and Consumer Discretionary (-1.30%) weighed heavily on the index.
Macro Update: The number of new investment housing loans surged 13.6% to 57,624 in the September quarter 2025, marking the highest level since March 2022, according to the Australian Bureau of Statistics (ABS). The increase—equivalent to 6,906 additional loans—reflects a 12.3% rise over the past year. The total value of new investment loans climbed 17.6% to AUD 39.8 billion, an increase of AUD 6.0 billion from the previous quarter, while the average loan size rose by AUD 11,686 to AUD 685,634. The ABS noted that falling borrowing costs and low rental vacancy rates have created favourable conditions for property investors, driving the overall value of new dwelling loans to a record high in September.
Top Market Movers: Mineral Resources Limited (ASX:MIN) led the gains on the ASX, climbing 9.19% to close at AUD 51.23. Liontown Resources Limited (ASX:LTR) advanced 6.05% to AUD 1.32, while Centuria Capital Group (ASX:CNI) rose 4.44% to AUD 2.35. On the downside, Life360 Inc. (ASX:360) fell 13.08% to AUD 39.81, Aristocrat Leisure Limited (ASX:ALL) slid 7.52%, and Zip Co Limited (ASX:ZIP) dropped 5.43%.
Commodity Update: The dollar slipped on Wednesday after weak U.S. private-sector jobs data heightened concerns about labor market health. Investors awaited the expected reopening of the U.S. government, which could trigger a flood of delayed economic reports. Gold rose 0.37% to USD 4,131.40 per ounce, silver gained 0.75% to USD 51.12, and copper inched up 0.02% to USD 10,834.20. Brent crude eased 0.20% to USD 65.04 amid hopes of a shutdown resolution.
Our Stance: The ASX200 slipped 0.22% to 8,799.50 on Wednesday, reflecting mild profit-taking after a steady week of trading. The index’s pullback appears more like a pause than weakness, with gains in Consumer Staples and Energy suggesting selective rotation amid cautious optimism. Rising investment housing loans, supported by cheaper borrowing and tight vacancies, highlight property sector resilience. Meanwhile, steady commodities and firm gold prices indicate lingering risk aversion. Overall, the market shows balance—investors are adjusting positions toward income and resource-linked stocks as they await upcoming macro signals. Sustained lending growth and sector diversity could help cushion the benchmark from broader global volatility in the near term.
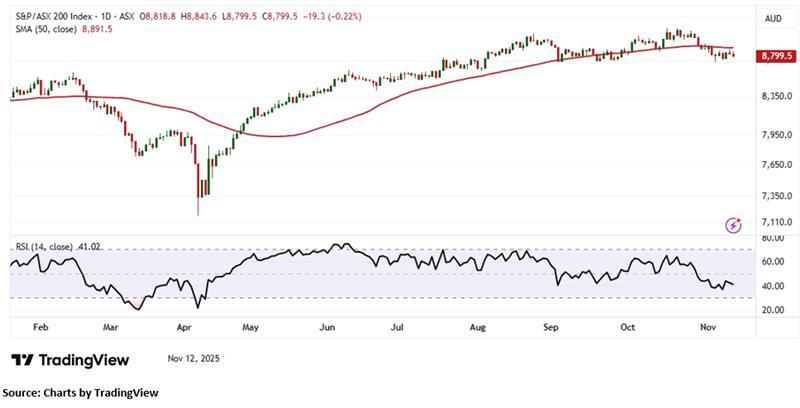
In its latest session, the S&P/ASX 200 Index declined by 19.30 points, forming a small bearish candlestick on rising trading volume—a combination that signals short-term investor caution and reinforces the prevailing bearish sentiment. Despite this modest pullback, the index continues to trade below its 50-period Simple Moving Average (SMA), which remains a zone of immediate resistance. On the daily chart, key support is identified near 8,740, and holding above this level could help the index stabilize recent gains and restore market confidence. From a broader weekly perspective, the index remains above its 21-period SMA, a constructive long-term signal that indicates the potential for sustained upward momentum once near-term selling pressure eases.


 Nov 12, 2026





 Please wait processing your request...