
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
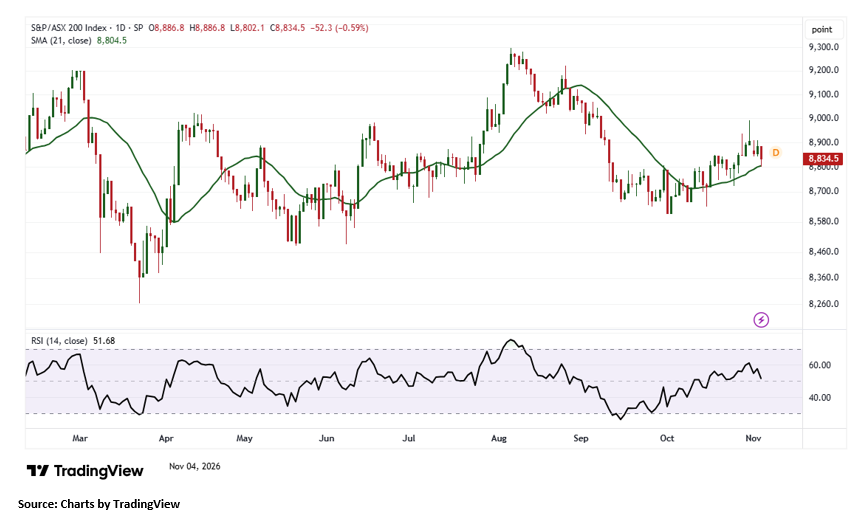
Index Update: The S&P/ASX 200 fell 52.30 points, or 0.59%, to 8,834.50 on Wednesday, moving below its 125-day moving average. Materials declined 1.46% and Industrials lost 1.25%, leading sector weakness. Utilities rose 1.17%, while Energy added 0.86%. Seven of the 11 sectors finished lower, reflecting broad market pressure. Global uncertainty surrounding US-Iran relations and weaker US futures also weighed on sentiment. Despite the session's decline, the benchmark remained virtually unchanged over the five trading sessions, while sitting 4.97% below its 52-week high.
Macro Update: Australian household spending rose 0.6% in September 2026, according to data released today by the Australian Bureau of Statistics, rebounding from a 0.1% decline in August. Higher transport, health and recreation expenditure supported the growth. Transport and health spending each increased 1.5%, while fuel spending climbed 5.4%.
Meanwhile, geopolitical uncertainty intensified after US forces struck Iran’s Qeshm Island, despite President Donald Trump playing down the risk of renewed conflict and signalling prospects for diplomacy. The developments keep investors focused on consumer resilience, oil prices and Middle East tensions amid broader global economic uncertainty.
Top Market Movers: Block, Inc. (ASX:XYZ) led the gainers, rising AUD 6.650, or 6.064%, to AUD 116.310. NEXTDC Limited (ASX:NXT) advanced AUD 0.260, or 4.146%, to AUD 6.530, while Viva Energy Group Limited (ASX:VEA) added AUD 0.110, or 4.074%, to AUD 2.810. Among decliners, 4DMedical Limited (ASX:4DX) fell AUD 0.260, or 10.789%, to AUD 2.150. Silex Systems Limited (ASX:SLX) dropped AUD 0.320, or 9.581%, to AUD 3.020, while Electro Optic Systems Holdings Limited (ASX:EOS) declined AUD 0.610, or 7.771%, to AUD 7.240.
Commodity Update: The US dollar declined against most major currencies as investors awaited US midterm election results and assessed their potential political implications. Gold edged down 0.01% to USD 3,939.70, while silver fell 1.23% to USD 49.15 and copper declined 1.06% to USD 13,383.70. Brent Crude oil slipped 0.25% to USD 103.34, with Market Participants monitoring election outcomes and their possible impact on Middle East peace talks, alongside an unexpected decline in US crude inventories.
Our Stance: The S&P/ASX 200 fell 0.59% to 8,834.50, with seven sectors lower and Materials and Industrials leading declines, although the index was little changed over five sessions. Australian household spending rose 0.6% in September, offering a positive signal on demand, while US strikes on Iran’s Qeshm Island kept geopolitical risks in focus. Gold was nearly flat, while silver, copper and Brent crude eased as markets assessed US election outcomes and Middle East developments. Market Breadth remained weak, with 4DMedical and Silex among the biggest fallers. Overall, mixed domestic data and external uncertainty suggest a cautious near-term outlook for Australian Equity investors.
From a technical perspective, the S&P/ASX 200 Index declined during the latest Trading session but continues to maintain a cautiously constructive near-term outlook. The index is holding above key support at 8,790.50, which remains crucial for preserving the broader bullish structure. Sustained trading above this level could stabilise market sentiment and support a recovery towards recent highs. Immediate resistance is positioned near 8,870.60, and a decisive breakout above this level could strengthen bullish momentum and open the way towards the next target of 8,920. Conversely, a sustained break below 8,790.50 could undermine the positive technical outlook and expose the index to further downside pressure.


 Nov 12, 2026





 Please wait processing your request...