
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
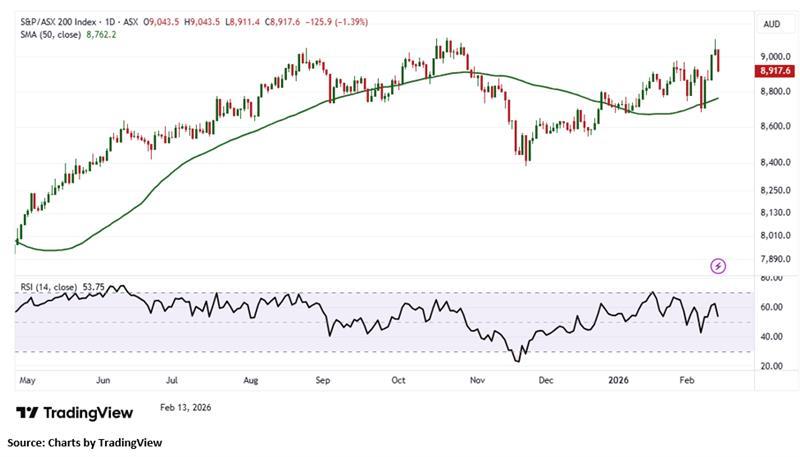
Index Update: The S&P/ASX 200 closed lower on Friday, falling 125.90 points or 1.39% to 8,917.60 after earlier setting a new 50-day high. Over the past five sessions, the benchmark index posted a gain of 2.40% and is currently 2.17% below its 52-week high.
Sector performance ended mixed, with nine of the eleven sectors finishing in the red alongside the broader index. Information Technology recorded the steepest decline on the session, down 5.06%, followed by Health Care, which fell 4.04%. Consumer Discretionary declined 2.36%, Materials slipped 2.02%, and Energy ended 2.00% lower. Industrials and Financials both eased 0.84%, while Telecommunications Services fell 0.75% and Consumer Staples edged down 0.41%.
Utilities was the sole outperformer, rising 3.38% on the day. The sector has gained 9.38% over the past five days, standing out against broader market weakness. A-REITs ended the session higher by 0.99%, while the remaining sectors closed lower in line with the broader market move.
Macro Update: World oil demand is now expected to rise more slowly in 2026, and supply growth is also set to decelerate, the International Energy Agency said on Thursday. Global supply fell to 106.6 million bpd in January, a 1.2 million bpd drop from December due to severe U.S. winter storms, an outage at Kazakhstan’s Tengiz field and constraints in Russia and Venezuela. Supply in 2026 is forecast to rise by 2.4 million bpd, down from 3.1 million in 2025. Tightening supply and U.S.–Iran tensions helped push oil prices higher in recent weeks, the IEA added.
Top Market Movers: Top gainers included AMP Limited (ASX:AMP), which rose to AUD 1.395, up AUD 0.115 or 8.984%, followed by GQG Partners Inc. (ASX:GQG) at AUD 1.735, gaining AUD 0.125 or 7.764%. Origin Energy Limited (ASX:ORG) advanced to AUD 12.080, up AUD 0.580 or 5.043%. On the downside, Austal Limited (ASX:ASB) slid to AUD 4.870, down AUD 1.440 or 22.821%, while Nick Scali Limited (ASX:NCK) dropped to AUD 18.480, losing AUD 5.310 or 22.321%, and Cochlear Limited (ASX:COH) fell to AUD 199.220, down AUD 46.420 or 18.898%.
Commodity Update: The Japanese yen headed for its strongest weekly performance in nearly 15 months, supported by confidence after Prime Minister Sanae Takaichi’s election victory eased fiscal concerns. In commodities, gold rose 1.12% to USD 5,004.30, silver gained 1.62% to USD 76.90, and copper added 0.75% to USD 12,985. Brent crude advanced 0.40% to USD 67.55 but remained on track for a second weekly decline amid easing Iran-related supply risks.
Our Stance: The S&P/ASX 200 closed lower on Friday after briefly reaching a new 50-day high. Despite recent gains, the index remains slightly below its 52-week peak. Sector performance was mixed, with most sectors finishing in the red. Information Technology and Healthcare were among the biggest decliners, while Utilities stood out as the only sector to post gains, continuing its upward trend. Macro updates highlighted slower expected growth in both global oil demand and supply, while geopolitical tensions, particularly between the U.S. and Iran, contributed to recent oil price increases. With global energy dynamics and geopolitical risks adding uncertainty, a selective and cautious approach appears appropriate.
In its latest session, the S&P/ASX 200 Index declined 125.90 points, forming a bearish candlestick on rising trading volume—a combination that highlights heightened investor caution and reinforces the prevailing short-term bearish tone. On the daily chart, the index continues to trade above its 50-period Simple Moving Average (SMA), which remains a key area of immediate support. Near-term support is positioned around 8,820, and holding above this level will be critical to stabilising recent price action and rebuilding short-term confidence. From a broader weekly perspective, the index remains above its 50-period SMA, a constructive longer-term signal that suggests the potential for renewed upside momentum once near-term selling pressure begins to ease.


 Nov 12, 2026





 Please wait processing your request...