
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: Australian equities retreated sharply on Wednesday, with the S&P/ASX 200 falling 105.80 points, or 1.18%, to close at 8,843.60, as a steep Earnings downgrade from Cochlear triggered broad risk aversion and pressured the healthcare sector. The benchmark has declined 1.50% over the past five sessions and remains 3.90% below its 52-week high, underscoring softer near-term sentiment.
Healthcare bore the brunt of the sell-off, falling 6.01% and emerging as the clear laggard. Financials also weighed on the market, down 2.26%, while Consumer Discretionary and Energy slipped 0.82% and 0.74%, respectively. Despite the broad weakness, sector performance was mixed rather than uniformly negative, with four of eleven sectors posting gains. Consumer Staples stood out as the defensive outperformer, rising 1.07% on the day and extending its five-day gain to 2.82%, suggesting selective rotation into lower-Volatility exposures amid heightened uncertainty. Information Technology also edged higher by 0.34%, while Materials posted modest gains.
Macro Update: Geopolitical tensions remained in focus after US President Donald Trump said he would extend the ceasefire with Iran until bilateral talks show further progress, while maintaining the blockade of Iranian ports until Tehran presents what he described as a “unified proposal.” The announcement suggested a temporary diplomatic pause, though the status of negotiations remained uncertain. US Vice-President JD Vance did not depart for Islamabad as expected, while Iran has yet to formally respond. Adding to the ambiguity, an adviser to Iran’s parliamentary speaker dismissed the extension as a tactical manoeuvre, warning it could be a precursor to renewed military pressure. In Islamabad, preparations reportedly remain in place for further talks, although expectations for a meeting this week have diminished, leaving markets alert to both diplomatic and escalation risks.
Top Market Movers: Treasury Wine Estates (ASX:TWE) rose 16.54% to AUD 4.72, leading the ASX gainers. New Hope Corporation (ASX:NHC) gained 5.47% to AUD 5.40, while Predictive Discovery (ASX:PDI) advanced 4.32% to AUD 0.965, rounding out the top three performers.
Cochlear (ASX:COH) fell 40.71% to AUD 99.58, the steepest decline on the index. Generation Development Group (ASX:GDG) dropped 22.61% to AUD 3.56, while Bank of Queensland (ASX:BOQ) declined 9.08% to AUD 6.61.
Commodity Update: The dollar steadied in early Asian trading on Wednesday as doubts persisted over U.S. President Donald Trump’s announcement of an indefinite extension to the Iran ceasefire, supporting safe-haven Demand and lifting the greenback to a one-week high. Gold climbed 1.15% to USD 4,773.05, while silver advanced 1.72% to USD 77.81. Copper edged up 0.12% to USD 13,242.50. Meanwhile, Brent Crude slipped 0.20% to USD 98.21 per barrel in Asian trade.
Our Stance: Australian equities weakened sharply as Cochlear’s Earnings downgrade drove a broad healthcare-led sell-off, dragging the ASX 200 lower and reinforcing cautious sentiment. Defensive rotation into Consumer Staples provided some offset, while gains in select miners and energy-linked names contrasted with sharp declines in healthcare and financials. Geopolitical uncertainty surrounding the Iran ceasefire extension and ongoing doubts over diplomatic progress added to a risk-sensitive backdrop, while firmer gold prices reflected safe-haven Demand. Commodity moves remained mixed, with oil easing modestly. Overall, markets may remain rangebound near term, with sentiment likely driven by Earnings credibility, defensive positioning, and geopolitical developments.
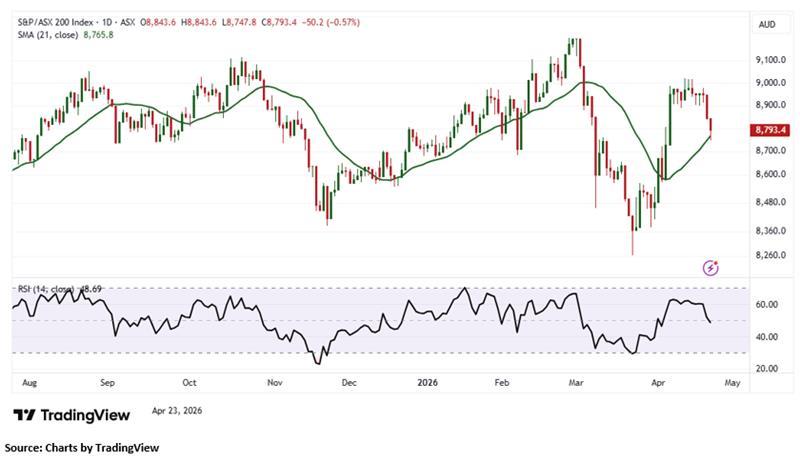
The S&P/ASX 200 declined by 50.20 points in the latest session, forming a bearish candlestick that signals weakening sentiment and rising selling pressure. Despite the pullback, the index continues to trade above its 21-period Simple Moving Average (SMA), which is acting as a key dynamic support and helping maintain the broader bullish structure. Holding above this level may provide near-term stability and limit immediate downside risks. However, immediate support is seen near 8,720.50. A decisive break below this level could weaken sentiment further, potentially triggering a deeper corrective phase and increasing short-term Volatility.


 Nov 12, 2026





 Please wait processing your request...