
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
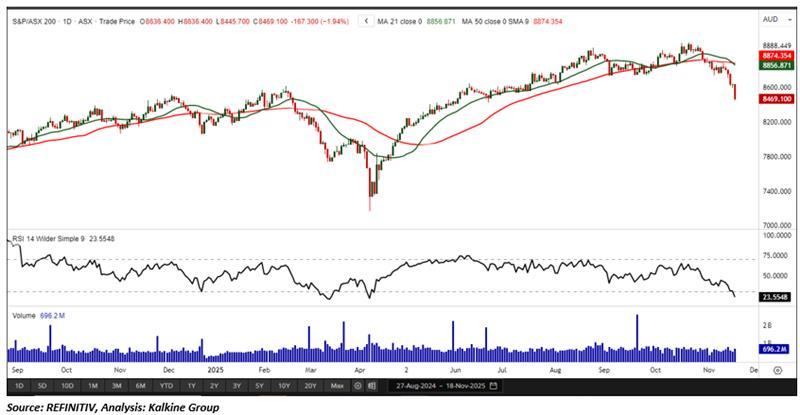
Index Update: The S&P/ASX 200 recorded a new 100-day low on Tuesday, dropping 167.30 points or 1.94% to 8,469.10. The index has lost 3.97% over the past five sessions, though it remains up 3.80% year-to-date. Sector performance was weak, with all the 11 sectors finishing in the red along with the index. Information technology led the declines with a drop of almost 6%. Technology shares - One Limited and Catapult Sports Ltd fell 17.20% and 11.72%, respectively. Market sentiment was weighed down by growing anxiety over chip giant Nvidia’s upcoming results and concerns that US interest rates may not fall soon.
Macro Update: According to media reports, the Reserve Bank of Australia (RBA) has indicated it would consider cutting interest rates only if there is a significant downturn in the labour market. This cautious stance reflects uncertainty about how current monetary policy settings are impacting the economy. While the RBA acknowledged that interest rates remain “a little restrictive,” it also suggested that this may no longer be the case, reducing the likelihood of further rate cuts in the near term.
Top Market Movers: The top gainers on the ASX 200 were James Hardie Industries (ASX:JHX), which surged 9.87% to AUD 27.94, followed by GQG Partners (ASX:GQG), up 3.47% to AUD 1.49, and Pilbara Minerals (ASX:PLS), gaining 3.28% to AUD 4.09. On the downside, Technology One Limited (ASX:TNE) plunged 17.21% to AUD 29.26, Catapult Sports (ASX:CAT) fell 11.72% to AUD 4.82, and Superloop Limited (ASX:SLC) declined 11.68% to AUD 2.42.
Commodity Update: Commodity Update: The yen weakened to a nine-month low in early Asian trade on Tuesday as fading expectations of a Fed rate cut next month boosted the dollar. Precious metals retreated, with gold down 1.32% to USD 4,020.40, silver slipping 2% to USD 49.68, and copper easing 0.43% to USD 10,733.10. Brent crude dipped 0.40% to USD 63.92 as supply concerns eased after Russian export loadings resumed.
Our Stance: The S&P/ASX 200 fell sharply by 1.94% to 8,469.10 on Tuesday, hitting a new 100-day low amid broad weakness across all 11 sectors. Information technology was the hardest hit, dropping nearly 6%, weighed down by steep losses in Technology One Limited and Catapult Sports Ltd. Market sentiment remains fragile, pressured by concerns over Nvidia’s upcoming earnings and uncertainty around the timing of US interest rate cuts. On the macro front, the Reserve Bank of Australia’s cautious tone, signaling rate cuts only if there is a significant labour market downturn, adds to the cautious environment. Commodity markets were also softer, with precious metals and Brent crude retreating amid easing supply concerns and a stronger US dollar. Taken together, persistent global tech headwinds, cautious monetary policy signals, and subdued commodity prices suggest investors should maintain a guarded outlook, especially in rate-sensitive and technology-exposed segments.
The S&P/ASX 200 Index came under sustained pressure, dropping 167.30 points and forming a bearish candlestick accompanied by rising trading volume—an indication of strengthening short-term selling momentum and the potential for further downside. The index remains positioned below its 21-period Simple Moving Average (SMA), which continues to act as a key overhead resistance zone. On the daily chart, the critical support level is situated near 8,400. Holding above this area could offer a base for a potential rebound; however, a decisive breakdown below it may accelerate bearish momentum and open the door to additional weakness. Momentum indicators align with this view, with the Relative Strength Index (RSI) reflecting neutral to slightly bearish conditions. If selling pressure persists and support levels fail to hold, the index may be vulnerable to an extended downward move in the near term.


 Nov 12, 2026





 Please wait processing your request...