
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed lower on Thursday, falling 38.60 points, or 0.43%, to 8,889.20, snapping a two-day winning streak. Over the past five sessions, the index has declined 0.43% and remains 2.48% below its 52-week high. Market breadth was mixed, with 101 decliners, 87 gainers, and 10 unchanged stocks. Despite the index fall, eight of 11 sectors ended higher. Consumer Discretionary led sector gains, rising 1.36% and advancing 0.90% over five days, as volatility persisted in resource stocks following a sharp drop in silver prices.
Macro Update: Australia’s goods trade balance strengthened in December, according to data released today by the Australian Bureau of Statistics. The seasonally adjusted balance on goods increased by AUD 776 million. Goods credits (exports) rose AUD 440 million, or 1.0%, driven by metal ores and minerals, while goods debits (imports) fell AUD 336 million, or 0.8%, led by other merchandise goods.
Separately, the Reserve Bank of Australia raised its cash rate to 3.85% from 3.6% this week, marking the first hike in over two years after annual inflation rose to 3.8%.
Top Market Movers: Among the top gainers of Thursday, Treasury Wine Estates (ASX:TWE) rose AUD 0.360 or 6.976% to AUD 5.520, followed by Amcor (ASX:AMC), which advanced AUD 4.340 or 6.645% to AUD 69.650. GQG Partners (ASX:GQG) climbed AUD 0.100, gaining 6.192% to close at AUD 1.715.
On the downside, Neuren Pharmaceuticals (ASX:NEU) fell AUD 1.430 or 9.775% to AUD 13.200, while NexGen Energy (ASX:NXG) declined AUD 1.670 or 9.176% to AUD 16.530. Paladin Energy (ASX:PDN) slipped AUD 1.220, down 8.984%, to AUD 12.360.
Commodity Update: The U.S. dollar steadied in early Asian trade as markets awaited interest rate decisions from the European Central Bank and the Bank of England, both widely expected to keep policy unchanged. Commodities weakened, with gold slipping 1.76% to USD 4,864.70, silver tumbling 9.56% to USD 76.33, and copper easing 1.35% to USD 12,885.50. Brent crude fell 1.40% to USD 68.47 after the U.S. and Iran agreed to hold talks in Oman, easing geopolitical supply concerns.
Our Stance: Thursday’s ASX 200 decline reflects a market grappling with crosscurrents rather than broad-based weakness. While resource-sector volatility, amplified by a sharp fall in silver prices, weighed on the index, gains across most sectors signal underlying resilience. Strength in consumer-facing stocks suggests selective risk appetite remains intact despite tighter financial conditions following the RBA’s rate hike. At the macro level, an improving trade balance offers support, though global commodity softness and policy uncertainty abroad continue to shape sentiment. Overall, the session points to a cautious, fragmented market, where sector rotation and external drivers are likely to dominate near-term moves.
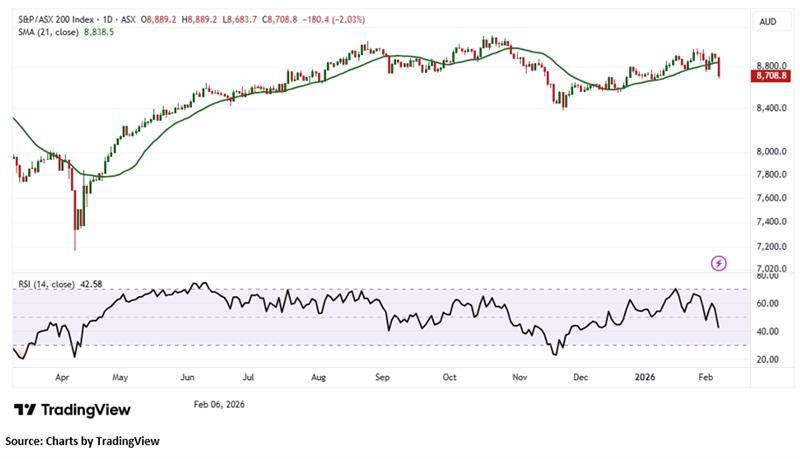
In its latest session, the S&P/ASX 200 Index declined sharply by 180.40 points, forming a bearish candlestick on rising trading volume, a combination that reflects heightened investor caution and reinforces the prevailing short-term bearish bias. On the daily chart, the index continues to trade below its 21-period Simple Moving Average, which remains an important near-term resistance level and is capping upside attempts. Immediate support is located near the 8,600 mark, and holding above this zone will be critical to stabilising price action and limiting further downside pressure. From a broader perspective, the index remains above its 50-period SMA on the weekly timeframe, preserving a constructive medium- to longer-term outlook. Once near-term selling pressure subsides, the index may regain traction and attempt to re-establish its broader upward trend.


 Nov 12, 2026





 Please wait processing your request...