
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: Australia’s benchmark index S&P/ASX 200 ended Friday’s session slightly lower, easing 12.60 points or 0.14% to close at 8,960.60. The pullback comes after a notable run, with the index still posting a 4.44% gain over the past five trading days and remaining just 2.63% below its 52-week high.
Despite the modest decline, the market has recorded its best weekly performance since October 2022. Investor sentiment, however, turned cautious ahead of upcoming US-Iran ceasefire talks, while ongoing concerns around the Strait of Hormuz blockade continue to linger without clear signs of resolution.
Sector performance was mixed, with eight of eleven sectors finishing in negative territory, reflecting uneven participation in the recent rally. Real estate stocks stood out as a relative bright spot, with the A-REIT sector advancing 0.93% on the day and extending its five-day gain to 5.03%.
Macro Update: As stated by Reuters, tensions resurfaced within the fragile U.S.–Iran ceasefire on Friday, just a day ahead of scheduled talks in Pakistan, as both sides traded accusations over violations in the Strait of Hormuz. Washington alleged Tehran had failed to honour commitments, while Iran pointed to ongoing Israeli strikes in Lebanon as a key obstacle. Shipping activity through the strait remains severely disrupted, with only limited vessels passing, raising concerns over prolonged pressure on global energy supplies.
Top Market Movers: Top movers reflected a mixed session, with gains led by Telix Pharmaceuticals Limited (ASX:TLX), rising to AUD 14.640 (+AUD 1.000, +7.33%), followed by Mesoblast Limited (ASX:MSB) at AUD 2.120 (+AUD 0.090, +4.43%) and AMP Limited (ASX:AMP) at AUD 1.365 (+AUD 0.055, +4.20%). On the downside, Orora Limited (ASX:ORA) fell to AUD 1.485 (-AUD 0.135, -8.33%), while Super Retail Group Limited (ASX:SUL) and Champion Iron Limited (ASX:CIA) also declined.
Commodity Update: On Friday, the U.S. dollar was set for its biggest weekly decline since January as global currencies strengthened on hopes that the Gulf ceasefire would hold and oil shipments would resume. However, caution remained ahead of key talks scheduled this weekend. Gold declined 0.96% to USD 4,771.30 per ounce, while silver dropped 1.11% to USD 75.58. Copper edged up 0.09% to USD 12,707.00. Brent crude rose 0.87% to USD 96.75 amid continued concerns over Saudi energy infrastructure and the Strait of Hormuz.
Our Stance: Australia’s S&P/ASX 200 eased 0.14% on Friday to 8,960.60, pausing after its best weekly gain since 2022, yet still advancing 4.44% over five sessions. Markets turned cautious ahead of US-Iran ceasefire talks, with tensions around the Strait of Hormuz continuing to disrupt energy flows. Sector breadth weakened despite resilience in A-REITs, while stock-level moves remained mixed. Commodities reflected uncertainty, with softer precious metals and firmer oil prices. Overall, while momentum remains intact, near-term direction appears increasingly tied to geopolitical clarity rather than domestic fundamentals.
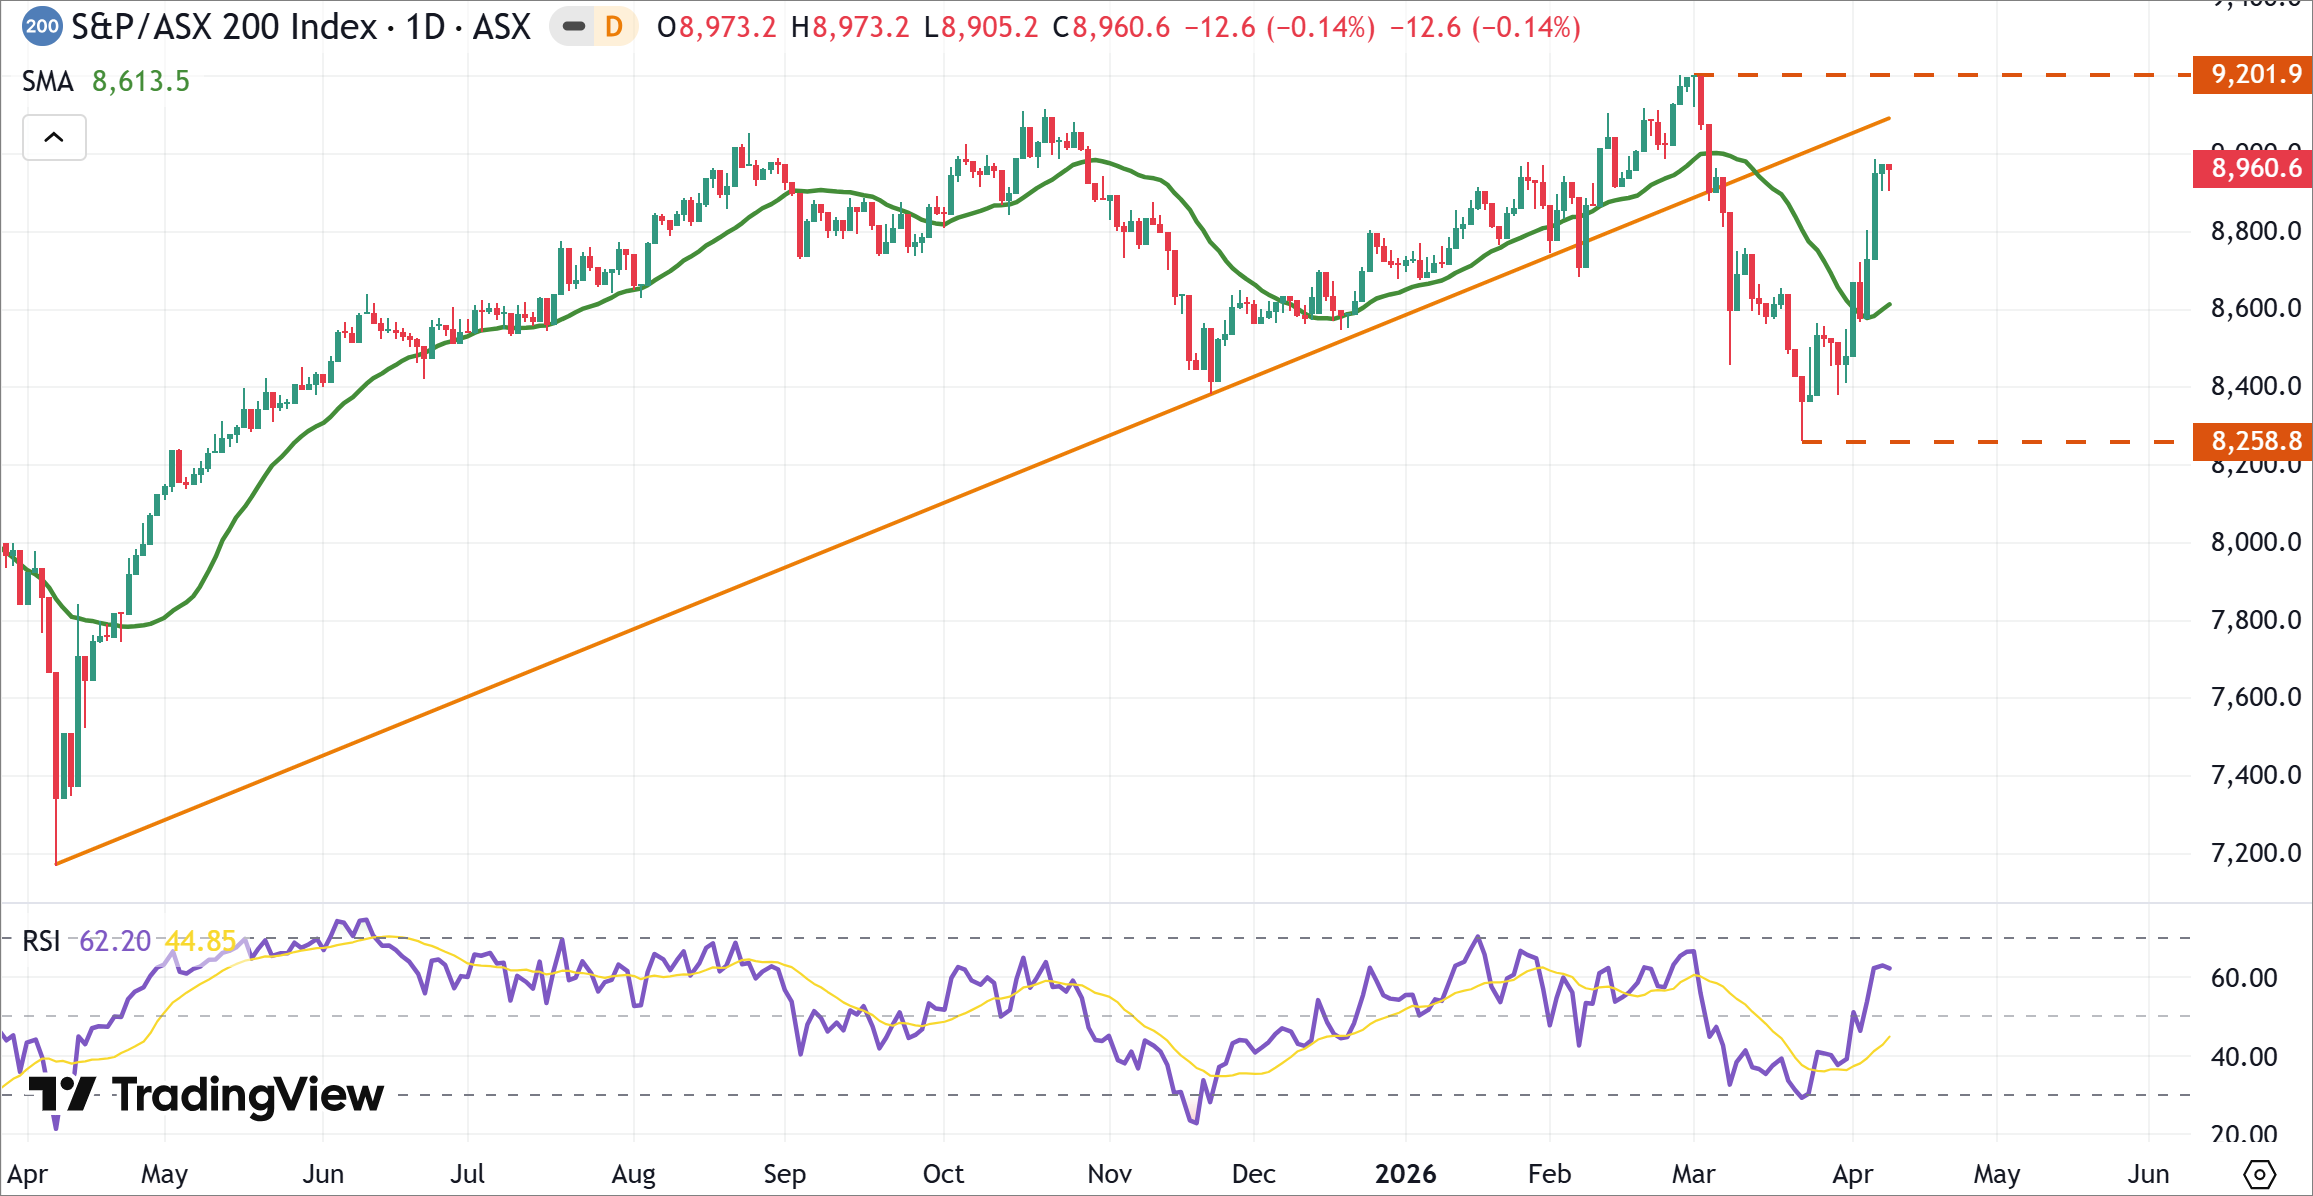
The S&P/ASX 200 edged lower by 12.6 points, or 0.14%, in the latest session, extending a sequence of sideways movements following its strong rebound from the recent low. Nonetheless, the formation of two consecutive candles with long lower shadows suggests that buying pressure remains firmly in place, supporting a positive short-term outlook. Furthermore, the 14-day Relative Strength Index (RSI) continues to hold above its midpoint, reinforcing this constructive view. That said, the broader technical setup still indicates a consolidation phase, with immediate support positioned around 9,202 points and near-term resistance located near 8,259 points.


 Nov 12, 2026





 Please wait processing your request...