
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
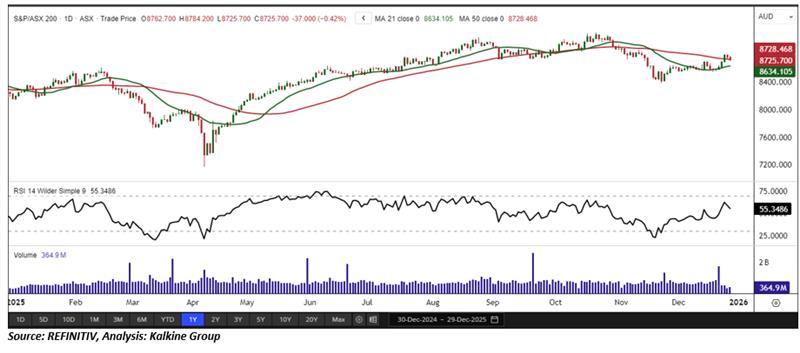
Index Update: The S&P/ASX 200 closed lower on Monday, falling 37.00 points, or 0.42%, to 8,725.70 and moving below its 50-day moving average. Over the past five sessions, the index has gained 1.21% and is currently 4.27% below its 52-week high. Market performance was mixed across sectors, with ten of the 11 sectors ending lower alongside the benchmark index. Weaker energy and technology stocks weighed on the market, outweighing gains among silver miners as silver prices continued to rise. Health Care was the best-performing sector, up 0.19% and rebounding from its recent decline, although it remains down 0.49% over the past five days.
Macro Update: Despite weaker consumer confidence and higher unemployment, third-quarter US economic growth exceeded expectations, with GDP expanding at a 4.3% annualised rate. Higher-than-forecast consumer spending was the primary contributor, supported by net exports. Inventory drawdowns during the quarter may aid fourth-quarter growth as demand remains firm, according to multiple media reports. Final sales to private domestic purchasers rose 3%, indicating a good underlying household and business demand entering the final quarter with momentum.
Top Market Movers: The top gainers of Monday included South32 Limited (ASX:S32), which rose to AUD 3.590, up AUD 0.080 (2.279%), followed by Block, Inc. (ASX:XYZ), climbing to AUD 98.680, up AUD 2.180 (2.259%), and Zip Co Limited (ASX:ZIP), which advanced to AUD 3.320, gaining AUD 0.070 (2.153%). On the downside, Netwealth Group Limited (ASX:NWL) fell to AUD 25.170, down AUD 1.720 (-6.397%), DroneShield Limited (ASX:DRO) declined to AUD 3.130, losing AUD 0.160 (-4.864%), while Helia Group Limited (ASX:HLI) slipped to AUD 5.530, down AUD 0.230 (-3.994%).
Commodity Update: The yen recovered modestly on Monday after last week’s sharp decline, as markets reassessed the timing of further BoJ rate hikes and potential intervention risks amid thin year-end trading. In commodities, gold slipped 0.34% to USD 4,537.20, silver rose 1.30% to USD 78.203, and copper surged 6.32% to USD 12,883.00. Brent crude climbed 0.90% to USD 60.78, supported by renewed Middle East supply concerns and elevated geopolitical risk premiums, although uncertainty around Russia–Ukraine peace negotiations continue to cap upside momentum.
Our Stance: Monday’s decline in the S&P/ASX 200 reflects a market recalibrating after recent gains, with the index slipping below its 50-day moving average amid broad-based sector weakness. While short-term sentiment was pressured by energy and technology stocks, resilience in Health Care and selective strength among silver miners point to underlying rotation rather than outright risk aversion. The macro backdrop remains supportive, with stronger-than-expected US GDP growth suggesting global demand is holding up despite softer confidence indicators. Commodity moves were mixed, highlighting crosscurrents from geopolitical risks and policy uncertainty. Overall, the session appears more corrective, with markets balancing economic momentum against valuation and policy-related caution heading into year-end.
In its latest session, the S&P/ASX 200 Index declined 37.00 points, forming a small bearish candlestick on rising trading volume a combination that signals increasing investor caution and reinforces the prevailing short-term bearish tone. On the daily chart, the index continues to trade below its 50-period Simple Moving Average (SMA), which remains a key zone of immediate resistance. Immediate support is located near the 8,600 level, and holding above this area will be critical for stabilising recent price action and restoring near-term confidence. From a broader weekly perspective, however, the index continues to trade above its 50-period SMA, a constructive long-term signal that suggests the potential for renewed upside momentum once short-term selling pressure begins to ease.


 Nov 12, 2026





 Please wait processing your request...