
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 ended Monday in negative territory, falling 32.70 points or 0.37% to close at 8,697.10. Over the past five sessions, the benchmark has declined 0.79%, while remaining largely flat on a year-to-date basis. Sector performance was mixed, with seven of the eleven sectors finishing lower in line with the broader index. Information Technology emerged as the top performer, rising 1.03% on the day and advancing 1.12% over the past five days. Australian equities faced pressure as investors remained cautious ahead of the Reserve Bank of Australia’s upcoming interest rate decision, with markets closely watching for signals on the future policy path.
Macro Update: According to media reports, Australia’s federal government could reduce its borrowing requirements by billions over the next two years if it adjusts the management of its nearly AUD 1 trillion debt portfolio, a shift that contrasts with the spending expansions seen in other economies on energy and defence. Ahead of next week’s budget, Commonwealth Bank of Australia indicated that the government’s debt agency, the Australian Office of Financial Management, is expected to raise around AUD 115 billion from bond markets in the upcoming financial year, compared with an estimated AUD 125 billion issued in the current year.
Top Market Movers: Top gainers included Life360 Inc. (ASX:360), which closed at AUD 21.230, up AUD 1.230 or 6.150%, followed by Imdex Limited (ASX:IMD), rising AUD 0.200 or 4.890% to AUD 4.290, and Droneshield Limited (ASX:DRO), which gained AUD 0.140 or 3.878% to finish at AUD 3.750. On the downside, The A2 Milk Company Limited (ASX:A2M) led losses, falling AUD 0.720 or 9.904% to AUD 6.550, while Liontown Limited (ASX:LTR) declined AUD 0.220 or 8.334% to AUD 2.420, and Lovisa Holdings Limited (ASX:LOV) dropped AUD 1.360 or 5.653% to close at AUD 22.700.
Commodity Update: The U.S. dollar steadied in Asian trade, while regional currencies stayed range-bound amid Middle East tensions and U.S. rate uncertainty. Gold fell 0.47% to USD 4,622.96, silver declined 0.35% to USD 76.165, and copper fell 0.35% to USD 12,968.73. Brent crude rose 0.11% to USD 108.28, supported by supply risks despite higher Organization of the Petroleum Exporting Countries output.
Our Stance: The S&P/ASX 200 drifted lower on Monday, slipping 0.37% to 8,697.10 as investors navigated a cautious start to the week. While losses across seven sectors weighed on sentiment, pockets of resilience emerged, with Information Technology posting modest gains. Beneath the surface, uncertainty remained the dominant theme, with markets positioning ahead of the Reserve Bank of Australia’s policy decision and watching closely for guidance on interest rates. At the same time, evolving fiscal signals around Australia’s debt management and softer commodity moves added to the subdued tone. Although selective stock strength provided some support, the broader mood suggests a market in wait-and-see mode, where clarity on policy and macro direction could dictate near-term momentum.
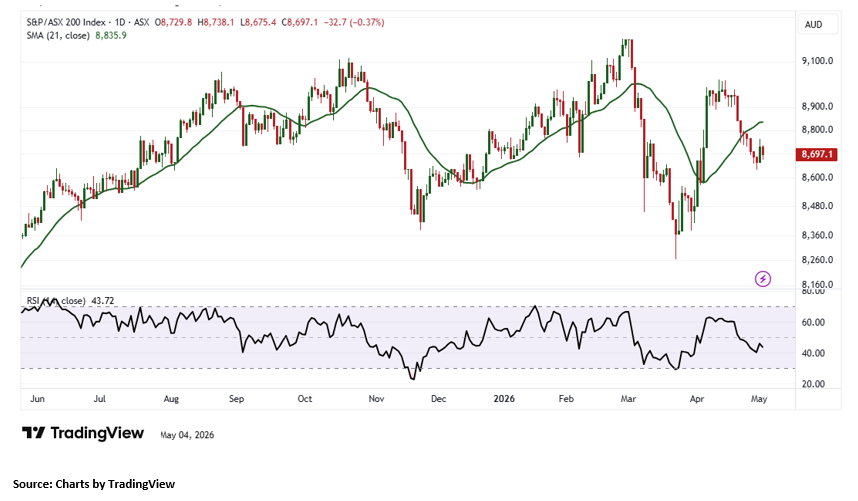
S&P/ASX 200 declined by 32.70 points in the latest session, forming a small bearish candlestick that signals softening sentiment and a gradual build-up in selling pressure. From a technical perspective, the index continues to trade below its 21-period Simple Moving Average (SMA), which is acting as a key dynamic resistance and reinforcing the near-term bearish bias. While the index is attempting to stabilise around current levels, immediate support is seen near 8,620.50. Holding above this level may help contain downside risks in the short term. However, a decisive break below this zone could further weaken sentiment, potentially triggering an extended corrective phase and elevating near-term volatility.


 Nov 12, 2026





 Please wait processing your request...