
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 ended Friday on a positive note, rising 105.30 points, or 1.23%, to close at 8,697.30, marking a fresh 20-day high. The market notched its longest winning streak since August, supported by firm gains in heavyweight mining stocks and sentiment buoyed by expectations of additional US interest rate cuts, a factor that continued to support risk appetite across sectors. Across the past five sessions, the benchmark index has climbed 0.73%, though it remains 4.58% below its 52-week high. Sector performance was broadly positive, with 8 of 11 sectors finishing higher. The materials sector led the gains, rising 2.03% on Friday and 2.75% over the past week, supported by strength in iron ore and gold-linked stocks.
Macro Update: The U.S. trade deficit fell to USD 52.8 billion in September, its lowest level in more than five years, as goods exports surged and imports rose modestly following a prolonged data blackout caused by a 43-day government shutdown. The improvement may support third-quarter GDP once updated figures arrive. Meanwhile, the Federal Reserve signalled a pause in its rate-cut cycle after three reductions this year, citing limited economic data, internal divisions on the outlook, and uncertainty ahead of a leadership transition.
Top Market Movers: Gains on the ASX were led by Greatland Resources Ltd (ASX:GGP), rising to AUD 9.440 after an AUD 0.850 gain, up 9.895%. Boss Energy Ltd (ASX:BOE) advanced to AUD 1.770, adding AUD 0.140 or 8.589%. Genesis Minerals Ltd (ASX:GMD) climbed to AUD 6.900 with an AUD 0.490 rise, up 7.644%. On the downside, Catapult Sports Ltd (ASX:CAT), Neuren Pharmaceuticals Ltd (ASX:NEU), and Austal Ltd (ASX:ASB) posted modest declines.
Commodity Update: The U.S. dollar is heading for its third consecutive weekly decline, pressured by expectations of rate cuts next year after the Federal Reserve pushed back against hawkish market bets, boosting the euro and sterling to their highest levels since October. Gold fell 0.20% to USD 4,304.25, silver dropped 0.88% to USD 63.98, and copper slipped 0.26% to USD 11,840.75. Brent crude rose 0.50% to USD 61.61 amid potential U.S. action on Venezuelan oil tankers.
Our Stance: The S&P/ASX 200 closed higher at 8,697.30, extending its longest winning streak since August, buoyed by strong performances in heavyweight mining stocks. Materials led sector gains, driven by iron ore and gold-linked equities, while broader risk appetite benefited from expectations of potential US interest rate cuts. Market momentum remains positive, with the benchmark rising over the past five sessions, though it is still below its 52-week high. In the US, a narrowing trade deficit and a pause signaled by the Federal Reserve in its rate-cut cycle provide a supportive backdrop for equities. Overall, the index’s recent climb indicates markets are responding to steadier external cues, though the outlook will depend on clearer global data, policy direction, and sustained commodity performance.
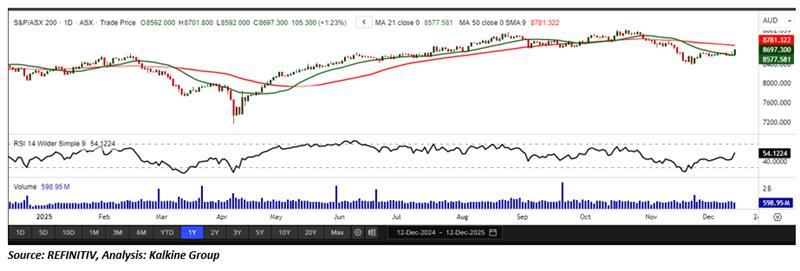
In its latest session, the S&P/ASX 200 Index advanced 105.30 points to close at 8,697.30, supported by a small bullish candlestick formation and strong trading volumes—both signaling sustained investor confidence. On the daily chart, the index continues to trade above its 21-period Simple Moving Average (SMA), which remains a key dynamic support level. A critical support zone near 8,600 continues to anchor the current bullish structure. Holding above this area is essential for preserving near-term strength. A successful defense of this level would allow the index to consolidate recent gains while reinforcing confidence in its broader upward trajectory. From a weekly standpoint, the index is trading comfortably above its 50-period SMA, underscoring a constructive longer-term outlook. Overall, the technical setup suggests the potential for continued upside momentum, provided near-term support levels hold firm.


 Nov 12, 2026





 Please wait processing your request...