
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Image Source : Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 closed higher on Wednesday, rising 21.80 points or 0.25% to finish at 8,918.00. The index has gained 1.03% over the past five sessions and now sits just 0.50% below its 52-week high. Sector performance was mixed, with seven of 11 sectors ending in positive territory. Consumer Discretionary led the gains, advancing +1.93% on the day and up +3.89% for the week. Other strong performers included A-REITs (+1.81%), Financials (+1.43%), and Utilities (+1.37%). On the downside, Materials weighed most heavily, slipping -2.32%, while Information Technology (-1.28%), Health Care (-1.23%), and Energy (-1.16%) also retreated.
Macro Update: Total wages and salaries paid by employers rose to AUD103,918 million in June 2025, an increase of 1.5% (AUD 1,535 million) from May 2025 and 5.9% (AUD 5,788 million) year-on-year from June 2024, according to the Australian Bureau of Statistics (ABS). On an annual basis, the 5.9% gain to June 2025 was largely in line with the 6.0% growth recorded to June 2024. For the 2024–25 financial year, total wages and salaries paid by employers reached AUD1,219 billion, up 5.9% from 2023–24 but below the 7.0% rise seen between 2022–23 and 2023–24. The ABS also noted that health care and social assistance remained the largest-paying sector, accounting for 14.6% of total wages and salaries in 2024–25.
Top Market Movers: HMC Capital Limited (ASX: HMC) led the gains on Wednesday, jumping 17.74% to AUD 3.85, followed by Centuria Capital Group (ASX: CNI), which surged 11.63% to AUD 2.40. The Lottery Corporation Limited (ASX: TLC) also advanced 6.99% to close at AUD 5.66. On the downside, James Hardie Industries Plc (ASX: JHX) slumped 27.83% to AUD 32.00, while Yancoal Australia Limited (ASX: YAL) fell 11.42% to AUD 5.51, and Clarity Pharmaceuticals Ltd (ASX: CU6) slid 11.31% to AUD 3.45.
Commodity Update: The U.S. dollar strengthened for a third straight session on Wednesday ahead of the Federal Reserve’s Jackson Hole symposium, where traders await policy cues. Gold eased 0.07% to USD 3,356.10, silver slipped 0.42% to USD 37.17, while copper inched up 0.02% to USD 9,699.15. Brent crude rose 0.21% to USD 65.93 amid resurfacing supply concerns, as prolonged Russia-Ukraine peace talks keep sanctions intact and raise risks of further restrictions.
Our Stance: The S&P/ASX 200 closed 21.80 points higher at 8,918.00, putting it just 0.50% below its 52-week high. Gains came from Consumer Discretionary, A-REITs, and Financials, while Materials and Technology weighed on the index. Wages rose 5.9% year-on-year in June, giving households steady income support, though growth has slowed compared to last year. Big stock moves, like HMC’s 17.7% jump and James Hardie’s 27.8% drop, show volatility is still high. With global markets waiting on signals from the U.S. Federal Reserve and commodities under pressure, the rally shows cautious optimism but also a need for selective investing.
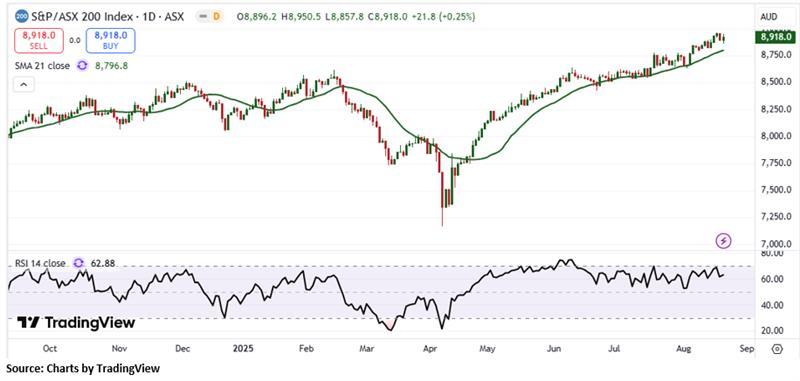
In its latest session, the S&P/ASX 200 Index gained 21.80 points to close at 8,918.00, supported by a bullish candlestick pattern and strong trading volumes clear signals of sustained investor confidence. On the daily chart, the index remains firmly above its 21-period Simple Moving Average (SMA), a dynamic support level that underpins the prevailing short-term bullish outlook. A key support zone is identified at 8,800.70, with sustained strength above this threshold vital to maintaining the integrity of the uptrend. On the upside, a decisive breakout above this support-turned-resistance level would serve as strong bullish confirmation, potentially unlocking further upward momentum and shifting market sentiment firmly in favor of the bulls. From a broader perspective, the index’s consistent position above the 21-period SMA on the weekly chart reinforces its resilient long-term bullish foundation.


 Nov 12, 2026





 Please wait processing your request...