
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
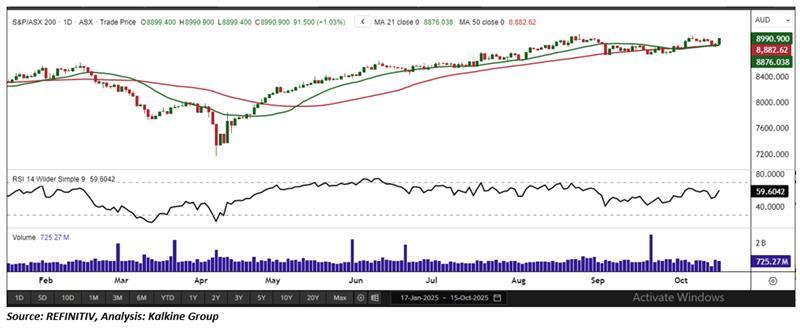
Index Update: The S&P/ASX 200 rose 91.50 points, or 1.03%, to close at 8,990.90 on Wednesday, marking its best session in nearly two weeks. The rally came as gold prices reached another record high and traders increased bets that the US Federal Reserve would deliver two additional interest rate cuts this year. Over the past five sessions, the index has gained 0.48% and now sits just 0.70% below its 52-week high. Ten of the eleven sectors finished higher, with health care leading the gains, up 2.07% for the day and 1.73% over the week.
Macro Update: According to Reserve Bank Chief Economist Sarah Hunter, underlying inflation was likely stronger than the RBA had anticipated last quarter, dampening expectations of further interest rate cuts. Meanwhile, US Federal Reserve Chair Jerome Powell indicated the central bank remains on track to lower interest rates at its meeting later this month, citing weakness in the labour market despite ongoing inflation concerns. Powell noted that the Fed is balancing two key risks: cutting rates too quickly could “leave the inflation job unfinished,” while moving too slowly could result in “painful losses in the employment market.”
Top Market Movers: Telix Pharmaceuticals Limited (ASX: TLX) led the gainers on Wednesday, climbing 16.30% to close at AUD 16.70. IperionX Limited (ASX: IPX) rose 10.98% to AUD 9.10, while Liontown Resources Limited (ASX: LTR) gained 9.26% to finish at AUD 1.18. On the downside, DroneShield Limited (ASX: DRO) fell 9.58% to AUD 5.10, GrainCorp Limited (ASX: GNC) dropped 4.23% to AUD 8.60, and Boss Energy Ltd (ASX: BOE) slipped 3.75% to AUD 1.93.
Commodity Update: The U.S. dollar weakened on Wednesday after Fed Chair Jerome Powell’s comments fueled expectations of an interest rate cut this month. Precious metals gained, with gold up 0.71% to USD 4,192.45, silver rising 1.07% to USD 51.15, and copper advancing 0.49% to USD 10,640.50. Brent crude slipped 0.19% to USD 62.27, extending losses amid the IEA’s supply surplus warning for 2026 and concerns over U.S.-China trade tensions impacting demand.
Our Stance: Equity sentiment remains constructive as easing inflation expectations and a dovish shift from major central banks support risk appetite. Strong gains in health care and materials highlight continued rotation toward defensive and commodity-linked sectors. However, the Reserve Bank’s cautious tone suggests limited scope for near-term domestic rate cuts, tempering the policy-driven optimism. Sustained strength in gold and a weaker US dollar point to ongoing demand for inflation hedges. While the near-term outlook favours moderate upside, valuations near record highs and lingering global growth uncertainties warrant a selective approach focused on earnings resilience and balance-sheet strength.
In its latest session, the S&P/ASX 200 Index gained 91.50 points, closing at 8,990.90, supported by a bullish candlestick and strong trading volumes clear signs of sustained investor confidence. On the daily chart, the index remains above its 21-period Simple Moving Average (SMA), which continues to act as dynamic support. A key support zone around 8,870 will be critical for maintaining the current uptrend. Holding this level could allow the index to consolidate recent gains and reinforce confidence in the broader upward trend. From a weekly perspective, the index also remains above its 21-period SMA, suggesting a constructive technical setup and the potential for sustained momentum over the longer term, provided near-term support levels hold firm.


 Nov 12, 2026





 Please wait processing your request...