
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 surged 149.30 points, or 1.74%, to close at 8,728.80 on Tuesday, marking a four-week high. Gains extended the five-day rise to 3.17%, while the index remains flat year to date. Investors rotated into previously pressured technology and mining stocks despite ongoing geopolitical tensions. All 11 sectors finished higher, led by information technology, which climbed 3.98% on the day and 6.44% over the week, signalling renewed risk appetite across the Australian equity market. Materials (+2.61%) and financials (+2.16%) also saw notable upward movement.
Macro Update: Multiple media reports indicate that US President Donald Trump has intensified rhetoric during the ongoing five-week US-Israeli conflict with Iran, issuing unusually explicit warnings. He outlined a potential large-scale strike scheduled for 20:00 Washington DC time on Tuesday, stating critical infrastructure such as bridges and power plants could be severely targeted. Trump warned that “very little is off-limits” unless Iran agrees to terms he deems acceptable, including ensuring free oil flow through the Strait of Hormuz. Iran has rejected both a ceasefire and the proposed conditions, presenting its own demands. With no agreement in sight, the situation places pressure on Trump’s credibility if deadlines are extended again.
Top Market Movers: Top gainers of Tuesday on the ASX were Guzman y Gomez Limited (ASX:GYG), rising AUD 2.820 to AUD 18.020 (+18.552%), followed by NEXTDC Limited (ASX:NXT), up AUD 1.340 to AUD 12.600 (+11.900%), and Bank of Queensland Limited (ASX:BOQ), gaining AUD 0.470 to AUD 7.270 (+6.911%). On the downside, Mesoblast Limited (ASX:MSB) fell AUD 0.145 to AUD 1.985 (-6.808%), Stockland (ASX:SGP) dropped AUD 0.140, and Sonic Healthcare Limited (ASX:SHL) declined AUD 0.500.
Commodity Update: On Tuesday, the U.S. dollar strengthened against major currencies after Iran rejected a ceasefire proposal and President Donald Trump intensified threats toward Tehran. Investor sentiment remained cautious amid fears of a wider Middle East conflict and an approaching diplomatic deadline. Gold slipped 0.26% to USD 4,672.05 per ounce, silver declined 0.27% to USD 72.61, while copper rose 0.68% to USD 12,422.00. Brent crude also gained 0.40% to USD 110.00.
Our Stance: The S&P/ASX 200’s sharp rise to a four-week high reflects renewed investor confidence, with strong rotation into technology and mining signalling improving risk appetite. Broad-based sector gains highlight supportive momentum, though year-to-date performance remains subdued. Ongoing geopolitical tensions, particularly escalating rhetoric surrounding the US-Iran conflict, continue to pose downside risks and could drive volatility across global markets. Commodity movements remain mixed, with energy prices firming on supply concerns while precious metals ease. Overall, market strength appears sentiment-driven, but sustainability will depend on geopolitical developments, macro stability, and continued earnings support across key sectors.
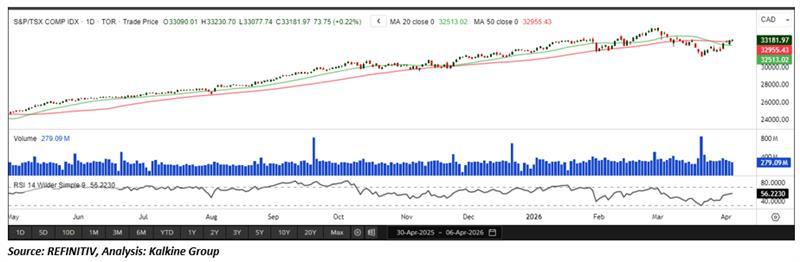
On Monday, the S&P/TSX Composite Index gained 73.75 points (0.22%) to close at 33,181.97. Despite the recent pullback, the broader market structure continues to reflect a phase of healthy consolidation rather than signaling a definitive trend reversal. From a technical standpoint, the index remains above its 21-period Simple Moving Average (SMA) on the daily chart, which is acting as a dynamic support level and helping to preserve the underlying positive bias. Momentum indicators, however, remain somewhat subdued, with the 14-period Relative Strength Index (RSI) hovering around 56.22. While still in positive territory, this suggests only moderate momentum and a lack of strong directional conviction. On the downside, immediate support is placed near 32,000. A break below this level could intensify consolidation pressures and potentially drag the index toward the 32,600 zone in the near term.


 Nov 12, 2026





 Please wait processing your request...