
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
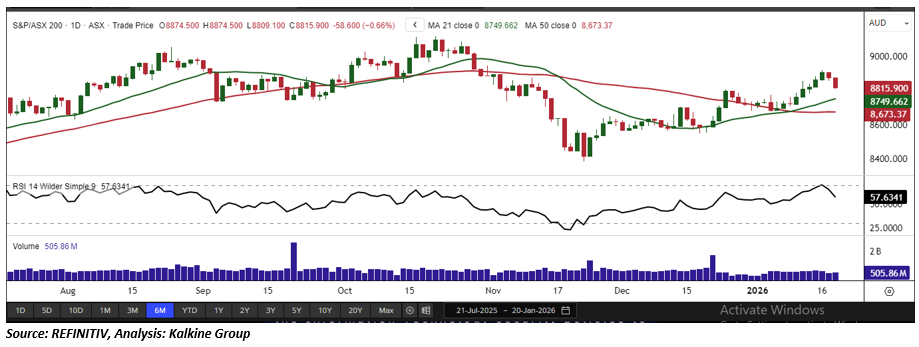
Index Update: The S&P/ASX 200 closed lower on Tuesday, falling 58.60 points, or 0.66%, to 8,815.90, marking a second consecutive session of declines. Over the past five trading days, the benchmark index is virtually unchanged, but it remains 3.28% below its 52-week high. Sector performance was mixed, with seven of the 11 sectors ending in negative territory alongside the broader market. Utilities emerged as the top-performing sector, rising 1.56% on the day and up 2.05% over the past week, while Financials and Materials weighed on the index. The Australian sharemarket retreated as risk sentiment was pressured by ongoing tariff-related comments from U.S. President Donald Trump, including renewed threats linked to Greenland, which continued to dampen global market appetite.
Macro Update: The International Monetary Fund modestly raised its global growth outlook again, citing easing U.S. tariff pressures and sustained investment in artificial intelligence. In its updated World Economic Outlook, the IMF forecast global GDP growth of 3.3% in 2026, up 0.2 percentage point from its October estimate, while 2025 growth is also seen at 3.3%, exceeding the prior forecast by 0.1 point. Growth in 2027 is projected at 3.2%, unchanged. IMF chief economist Pierre-Olivier Gourinchas said the global economy remains resilient, with activity recovering faster than expected from the trade disruptions of 2025.
Top Market Movers: Among top gainers, Bellevue Gold Limited (ASX:BGL) rose to AUD1.780, adding AUD0.085 or 5.01%, while DroneShield Limited (ASX:DRO) advanced to AUD4.740, up AUD0.190 or 4.18%. Xero Limited (ASX:XRO) climbed to AUD104.270, gaining AUD3.380 or 3.35%. On the downside, ARB Corporation Limited (ASX:ARB) fell to AUD28.420, down AUD3.890 or 12.04%, Lynas Rare Earths Limited (ASX:LYC) slipped 6.33% to AUD15.250, and Perenti Limited (ASX:PRN) declined 6.31% to AUD2.820.
Commodity Update: On Tuesday, the U.S. dollar stayed under pressure while U.S. Treasury yields climbed to their highest level in over four months, as renewed trade-war concerns weighed on risk sentiment and triggered selling in U.S. assets. Gold advanced 1.72% to USD 4,673.50 and silver gained 4.85% to USD 92.83, while copper slipped 0.72% to USD 12,885.20. Brent crude edged up 0.30% to USD 64.13, supported by stronger-than-expected economic growth data from China and ongoing focus on President Donald Trump’s tariff-related remarks.
Our Stance: The Australian sharemarket remained under pressure, with the S&P/ASX 200 extending losses amid mixed sector performance and ongoing global uncertainty tied to U.S. tariff rhetoric. While Utilities provided some support, weakness in Financials and Materials weighed on the index. Globally, the IMF’s upgraded growth outlook highlights resilience driven by easing trade pressures and continued AI investment, offering a constructive macro backdrop. However, near-term market sentiment is likely to stay cautious, with volatility persisting as investors balance improving global growth expectations against geopolitical and policy-related risks.
In the latest session, the S&P/ASX 200 Index declined by 58.60 points, forming a bearish candlestick on rising trading volumes. This price volume combination signals increasing investor caution and reinforces the prevailing short-term bearish bias. Technically, the index continues to trade above its 21-period Simple Moving Average (SMA), which is acting as an important area of immediate support. The key near-term support is located around the 8,740 level, and holding above this zone will be crucial for stabilising recent price action and restoring short-term market confidence. From a broader perspective, the weekly chart remains constructive, with the index holding above its 50-period SMA. This longer-term technical structure suggests that once near-term selling pressure subsides, the potential for renewed upside momentum remains intact.


 Nov 12, 2026





 Please wait processing your request...