
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
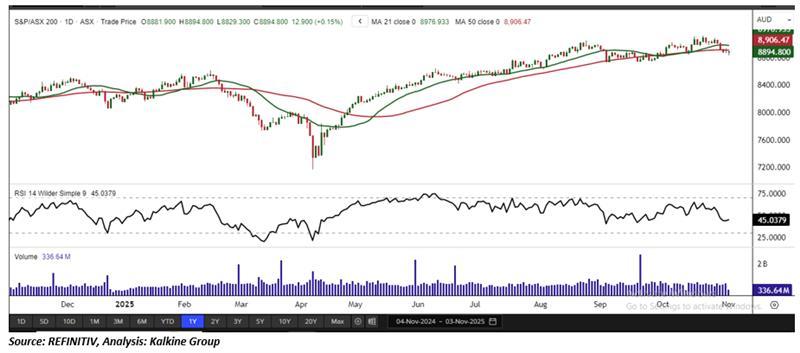
Index Update: The Australian sharemarket edged up on Monday, led by a sharp rally in the major banks. The S&P/ASX 200 closed up 12.90 points, or 0.15%, to 8,894.80 after setting a new 20-day low. The index has lost 1.78% over the last five days but remains 2.42% below its 52-week high. More sectors ended lower than higher, despite the overall gain in the S&P/ASX 200 Index. Information Technology was the best-performing sector, gaining 1.65% and rebounding from its recent decline. The sector, however, remains down 4.69% over the past five days.
Macro Update: Household spending in Australia edged up 0.2% in September, according to seasonally adjusted data released by the Australian Bureau of Statistics (ABS). The modest rise followed a flat result in August and a 0.4% increase in July. Non-discretionary spending drove the lift, with households spending more on food, health, and petrol, while discretionary categories were steady as gains in recreation and culture were offset by lower air travel and accommodation costs. On an annual basis, spending on miscellaneous goods and services rose 8.7%, and health spending climbed 8.1%. Services expenditure was up 7.2% from a year earlier, compared to a 3.4% rise in goods spending.
Meanwhile, the Producer Price Index for final demand (excluding exports) rose 1.0% in the September quarter and 3.5% over the past year.
Top Market Movers: Among the top gainers on Monday, Megaport Limited (ASX:MP1) rose 7.59% to close at AUD 17.71, followed by HMC Capital Limited (ASX:HMC), which advanced 4.84% to AUD 3.25. Catalyst Metals Limited (ASX:CYL) also gained 4.12% to AUD 7.07. On the downside, Lynas Rare Earths Limited (ASX:LYC) fell 8.07% to AUD 14.02, while Steadfast Group Limited (ASX:SDF) slipped 6.97% and Pilbara Minerals Limited (ASX:PLS) declined 5.15%.
Commodity Update: The U.S. dollar strengthened to a near three-month high on Monday ahead of key economic data that could influence the Federal Reserve’s policy outlook. Gold rose 0.38% to USD 4,011.50 per ounce, silver gained 0.66% to USD 48.48, while copper slipped 0.40% to USD 10,852.00. Brent crude climbed 0.73% to USD 65.24 after OPEC+ postponed planned production hikes for the first quarter of next year.
Our Stance: The Australian sharemarket’s modest rebound on Monday reflects cautious optimism amid mixed macro signals. Gains in major banks and IT stocks helped the S&P/ASX 200 edge higher despite broader sectoral weakness. Consumer data showing only a slight rise in September household spending underscores persistent cost pressures limiting discretionary activity. Meanwhile, the 1.0% quarterly rise in producer prices suggests ongoing input cost challenges. With commodities showing uneven momentum and the U.S. dollar firming, market sentiment remains tentative, balancing between improving financial sector performance and lingering inflationary risks that may weigh on short-term growth prospects.
In its latest session, the S&P/ASX 200 Index rose 12.90 points to close at 8,894.80, supported by a bullish candlestick formation and strong trading volumes—clear signs of sustained investor confidence. On the daily chart, however, the index remains below its 21-period Simple Moving Average (SMA), which continues to act as dynamic resistance. A key support zone lies near 8,800, and holding above this level is essential to preserve the current bullish structure. Maintaining this support could enable the index to consolidate recent gains and reinforce investor confidence in the broader uptrend. From a weekly perspective, the index continues to trade above its 21-period SMA, reflecting a constructive longer-term outlook and suggesting the potential for further upside, provided near-term support levels remain intact.


 Nov 12, 2026





 Please wait processing your request...