
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: Australian equities ended marginally higher on Wednesday, with the S&P/ASX 200 adding 7.90 points to close at 8,978.70. The benchmark index has risen 0.30% over the past five sessions and remains 2.44% below its 52-week high.
The market reached its strongest level since early March, initially supported by optimism around potential renewed peace talks between the United States and Iran. However, sentiment softened later in the session as banking stocks experienced broad-based selling pressure.
Sector performance was mixed, with more sectors finishing in negative territory despite the overall gain in the index. Information Technology emerged as the top performer, rising 2.24% and partially recovering from recent declines, although the sector remains down 4.73% over the past five days.
Macro Update: The International Monetary Fund (IMF) has lowered its 2026 global growth “reference forecast” to 3.1%, citing rising energy prices linked to the Middle East conflict. The Fund warned the global economy is already edging toward a weaker scenario of around 2.5% growth, with disruptions in the Strait of Hormuz adding to uncertainty.
IMF Chief Economist Pierre-Olivier Gourinchas cautioned that a prolonged or intensifying conflict could push the global economy close to Recession, particularly if oil prices exceed $110 per barrel through 2026–2027, complicating Inflation control.
The IMF outlined three potential paths—ranging from weaker to severe—depending on how the conflict evolves, while noting that Iran and several Gulf economies could face sharp GDP contractions if the situation worsens.
Top Market Movers: Among the top gainers, Evolution Mining Limited (ASX:EVN) rose to AUD14.45, up AUD1.26 (9.55%), followed by DroneShield Limited (ASX:DRO) at AUD3.72, gaining AUD0.31 (9.09%), and Mesoblast Limited (ASX:MSB) at AUD2.17, up AUD0.16 (7.96%). On the downside, Lynas Rare Earths Limited (ASX:LYC) fell to AUD20.56, down AUD1.51 (6.84%), Viva Energy Group Limited (ASX:VEA) slipped to AUD2.53, and Telix Pharmaceuticals Limited (ASX:TLX) declined to AUD14.80.
Commodity Update: The dollar remained largely flat on Wednesday as investors weighed the possibility that peace talks between the United States and Iran could resume, potentially easing Supply disruptions caused by the closure of the Strait of Hormuz. Risk appetite was also supported by a cooler-than-expected U.S. producer Inflation report. Gold slipped 0.18% to USD 4,842.15, while silver gained 0.50% to USD 79.96. Copper edged up 0.01% to USD 13,284.00, and Brent Crude advanced 0.51% to USD 95.41 per barrel.
Our Stance: Australian equities closed slightly higher, but underlying Market Breadth remained weak as banking stocks weighed on sentiment despite gains in technology. While easing geopolitical hopes briefly supported risk appetite, Volatility tied to Middle East developments continues to shape direction. The IMF’s downgraded global growth outlook and risks of elevated oil prices add to macro uncertainty. Commodity movements remain mixed, reflecting cautious positioning. Overall, the market appears to be balancing near-term optimism with growing external risks, suggesting a fragile upward bias rather than a sustained rally.
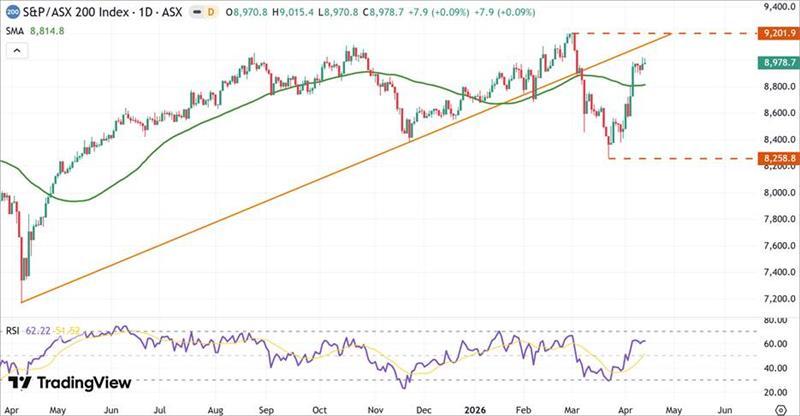
On Wednesday, the S&P/ASX 200 inched higher by 7.90 points, or 0.09%, to close at 34,102.36, maintaining its rebound from the recent trough. Moreover, the 14-period Relative Strength index (RSI) continues to hold above its midpoint, supporting a constructive short-term bias. Nevertheless, the broader technical setup still indicates a consolidation phase, as the index remains below the ascending Trendline originating from April 2025 as well as the record high reached in March 2026. Immediate support is seen around 8,259 points, while near-term resistance is capped near 9,202 points, outlining the current consolidation range.


 Nov 12, 2026





 Please wait processing your request...