
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The Australian sharemarket edged higher on Thursday, with the S&P/ASX 200 Index rising 16.00 points, or 0.18%, to close at 8,839.00, marking its highest level in 20 trading sessions. The benchmark remained largely unchanged over the past five sessions and finished 3.95% below its 52-week high. A stronger-than-expected Australian employment data reinforced expectations that the Reserve Bank of Australia could resume interest rate hikes. Sector performance remained mixed, with decliners outnumbering gainers despite the index finishing in positive territory. Materials emerged as the strongest performer, climbing 1.37% on the day and extending its five-day gain to 1.67%, while Energy (+0.98%), Utilities (+0.65%), A-REITs (+0.51%) and Financials (+0.29%) also closed higher. Information Technology led losses, falling 3.32%, followed by Consumer Discretionary (-1.52%), Health Care (-1.43%), Telecommunication Services (-1.15%), Consumer Staples (-0.53%) and Industrials (-0.46%).
Macro Update: Australia's seasonally adjusted unemployment rate held steady at 4.4% in June, according to the Australian Bureau of Statistics (ABS). Employment increased by 76,000, supported by a 47,000 rise in part-time jobs, while the number of unemployed people rose by 13,000. The participation rate climbed 0.3 percentage points to 67.0%. Meanwhile, the underemployment rate edged up to 6.5%, with people aged 55–64 recording the strongest annual increase in workforce participation. Trend employment rose 0.2%, while hours worked remained unchanged.
Top Market Movers: Generation Development Group (ASX:GDG) led the gains on the S&P/ASX 200, soaring 37.13% to close at AUD 4.580. Paladin Energy (ASX:PDN) followed with an 11.61% rise to AUD 10.190, while James Hardie Industries (ASX:JHX) advanced 6.14% to AUD 36.990. On the downside, WiseTech Global (ASX:WTC) fell 6.97% to AUD 31.480, Pro Medicus (ASX:PME) declined 6.53% to AUD 162.130, and Life360 (ASX:360) slipped 5.45% to finish at AUD 24.120.
Commodity Update: The U.S. dollar remained broadly stable as renewed tensions between the United States and Iran supported demand for safe-haven assets, while the Japanese yen stayed near a 40-year low amid continued policy divergence. Gold declined 0.56% to USD 4,129.40, silver slipped 0.32% to USD 60.10, while copper gained 0.30% to USD 13,848.20. Brent crude oil climbed 1.70% to USD 95.62, extending gains for a fifth consecutive session after attacks on Saudi oil tankers heightened concerns over potential supply disruptions in the Middle East.
Our Stance: The Australian sharemarket closed modestly higher on Thursday, but the session reflected growing caution beneath the surface. While the S&P/ASX 200 reached a 20-day high, gains were concentrated in materials and energy stocks as stronger-than-expected employment data fuelled expectations that the Reserve Bank of Australia may need to keep monetary policy tighter for longer. Commodity markets remained mixed, with firmer oil prices contrasting with weaker precious metals. Looking ahead, investors are likely to closely monitor upcoming inflation and economic data for further clues on the RBA's policy path, with interest rate expectations expected to remain a key driver of market sentiment.
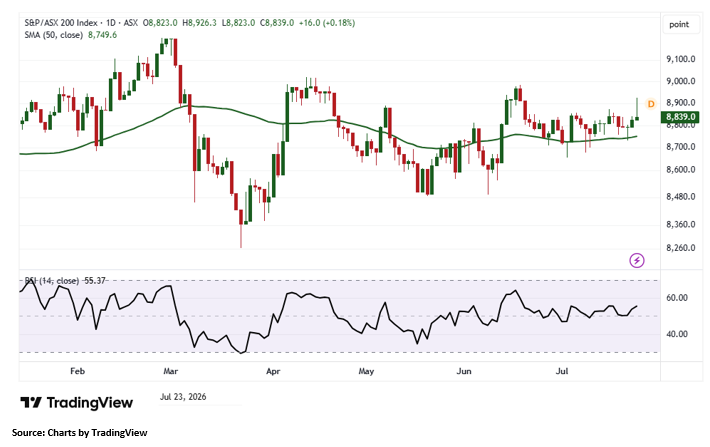
The S&P/ASX 200 gained 16.00 points in the latest trading session, forming a modest bullish candlestick that reflected cautious buying interest. The broader technical outlook remains constructive, with the index continuing to trade comfortably above its 50-day Simple Moving Average (SMA), reinforcing the prevailing medium-term uptrend. Immediate support is positioned near 8,760.70, and holding above this level would help maintain the bullish structure and keep the door open for further gains. A sustained rebound from support could lead to a retest of recent highs, while a decisive break below 8,760.70 may weaken near-term sentiment, increase selling pressure, and raise the likelihood of a deeper corrective pullback.


 Nov 12, 2026





 Please wait processing your request...