
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
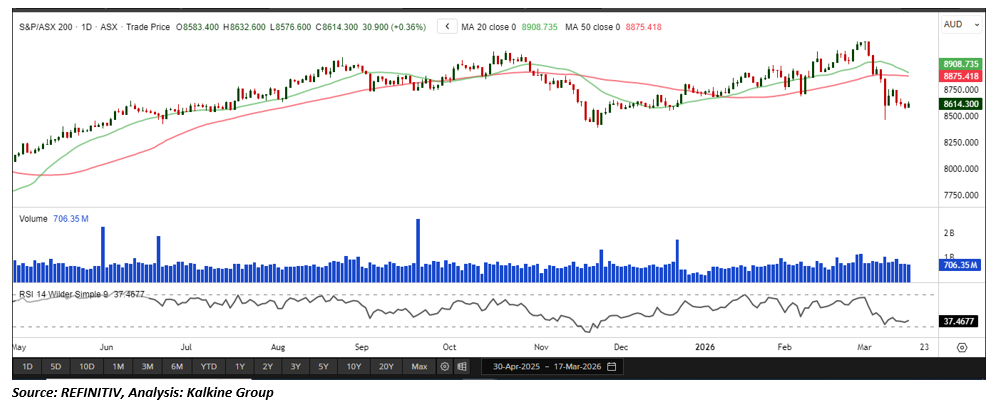
Index Update: The S&P/ASX 200 closed Tuesday up 30.90 points or 0.36% at 8,614.30 after the Reserve Bank of Australia raised the cash rate by 0.25 basis points in a split decision, indicating borrowing costs may not rise as aggressively as feared. The index was flat for most of the session before the announcement. Six of eleven sectors ended higher, led by materials up 1.00%, though the sector remains down 2.96% over five days. The index has fallen 0.90% over five days and 9.68% over 52 weeks.
Macro Update: The Reserve Bank of Australia raised interest rates, lifting the cash rate to 4.1% following a similar move in February, effectively reversing the relief from two cuts last year. The central bank indicated the possibility of further hikes, citing persistent inflation pressures driven by strong employment, resilient spending, and rising petrol prices linked to the war in Iran. Inflation, already at 3.8% before the conflict, is expected to remain elevated, with policymakers aiming to curb demand and limit cost pass-through to consumers.
Top Market Movers: Top gainers on the ASX were Pantoro Gold Limited (ASX:PNR), rising AUD 0.410 or 12.023% to AUD 3.820, followed by Ora Banda Mining Ltd (ASX:OBM), up AUD 0.125 or 9.090% to AUD 1.500, and Catalyst Metals Limited (ASX:CYL), gaining AUD 0.470 or 7.642% to AUD 6.620. On the downside, Temple & Webster Group Ltd (ASX:TPW) fell AUD 0.530 or 7.594% to AUD 6.450, New Hope Corporation Limited (ASX:NHC) declined AUD 0.340 or 6.416% to AUD 4.960, and Yancoal Australia Limited (ASX:YAL) dropped AUD 0.390 or 4.900% to AUD 7.570.
Commodity Update: The U.S. dollar traded in a narrow range on Tuesday as markets assessed ongoing geopolitical tensions involving Iran, while the Australian dollar edged lower ahead of a widely anticipated central bank rate decision. In commodities, gold rose 0.51% to USD 5,027.60, silver gained 0.68% to USD 81.22, and copper advanced 0.24% to USD 12,888.80. Brent crude climbed 2.10% to USD 102.28 amid persistent supply concerns.
Our Stance: The S&P/ASX 200’s modest gain reflects cautious investor positioning amid tightening monetary policy and persistent inflation risks. The Reserve Bank of Australia’s rate hike and signal of potential further increases point to a policy environment focused on controlling demand, even as external pressures such as rising fuel costs and geopolitical tensions add uncertainty. Sector performance, particularly in materials, suggests selective buying interest despite recent declines. Meanwhile, movements in commodities and currencies indicate continued sensitivity to global developments, implying that near-term market direction may remain influenced by both domestic policy actions and external macroeconomic factors.
The S&P/ASX 200 delivered a modestly positive performance in the latest session, gaining 30.90 points to close at 8,614.30, reflecting selective buying interest across key sectors. Despite this uptick, the broader technical structure remains somewhat cautious in the near term. The index continues to trade below its 21-period Simple Moving Average (SMA) on the daily chart, which is acting as a significant dynamic resistance level and capping immediate upside potential. Unless the index manages to reclaim and sustain above this technical barrier, upside momentum may remain limited over the short term. On the downside, immediate support is placed near the 8,520.50 level. Holding above this zone will be critical to stabilise market sentiment, while a decisive break below it could expose the index to further corrective pressure in the sessions ahead.


 Nov 12, 2026





 Please wait processing your request...