
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed lower on Friday, falling 73.10 points, or 0.81%, to 8,995.30 after hitting a new 52-week high earlier in the week. Over the past five days, the index has risen 0.41% but remains 1.26% below its yearly peak. Sector performance was mixed, with eight of the 11 sectors finishing in negative territory. Consumer staples led the gains, climbing 0.33% on the day and 0.16% over the week. The Australian share market eased as investors drove gold prices to record highs amid concerns over systemic stress in credit markets and ongoing tariff tensions between the US and China.
Macro Update: The U.S. budget deficit has narrowed by USD 41 billion to USD 1.775 trillion in the 2025 fiscal year, despite a USD 118 billion rise in revenues from President Donald Trump's tariffs, the Treasury Department reported on Thursday.
For the year ended September 30, which covers nearly nine months of Trump’s second term, the deficit compares with USD 1.817 trillion in fiscal 2024. This marks the first annual deficit decline since 2022, when the reduction in COVID-19 relief spending helped lower overall expenditures.
Meanwhile, economists at major financial firms estimated on Thursday that new applications for unemployment benefits in the U.S. declined last week, though weak hiring has kept many workers on the jobless rolls. They calculated that initial claims for state unemployment benefits fell to a seasonally adjusted 217,000 for the week ended October 11, down from 235,000 the previous week.
Top Market Movers: On Friday, Emerald Resources NL (ASX: EMR) led the gainers, closing at AUD 5.56, up 4.12%. Treasury Wine Estates (ASX: TWE) rose 3.67% to AUD 6.50, while Westgold Resources (ASX: WGX) gained 3.37% to close at AUD 5.83. On the downside, QBE Insurance (ASX: QBE) dropped 9.25% to AUD 19.52, DroneShield (ASX: DRO) fell 8.02% to AUD 4.59, and Life360 Inc. (ASX: 360) declined 7.98% to AUD 45.54.
Commodity Update: The U.S. dollar weakened on Friday amid rising global trade tensions and signs of economic softness, boosting expectations of further Federal Reserve rate cuts. The dollar index is heading for its steepest weekly decline in nearly three months as the U.S. government shutdown delays key data releases. Gold rose 1.57% to USD 4,372.49 per ounce, silver edged up 0.02% to USD 53.29, copper slipped 0.62% to USD 10,571.75, and Brent crude eased 0.13% to USD 60.98 per barrel.
Our Stance: Market sentiment remains cautious following a modest pullback in the S&P/ASX 200 after reaching a 52-week high. Gains in consumer staples and select resource stocks were outweighed by weakness in financials and technology. Elevated gold prices reflect persistent risk aversion amid global credit stress and renewed U.S.–China tariff concerns. In the U.S., a narrowing budget deficit and declining jobless claims signal gradual fiscal improvement, though labor market softness persists. Weaker dollar momentum and expectations of further Federal Reserve rate cuts continue to support precious metals. Overall, conditions suggest a near-term consolidation phase as investors reassess macroeconomic and geopolitical risks.
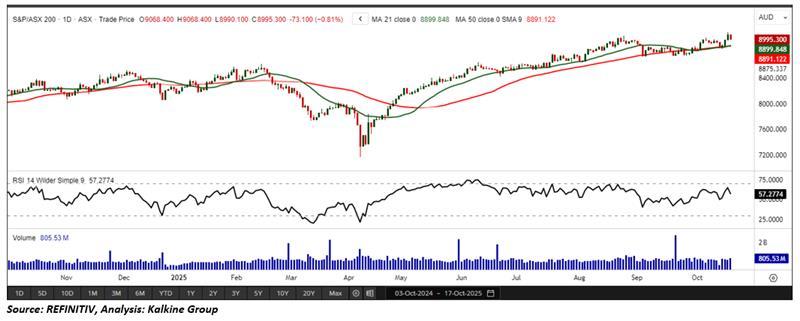
The S&P/ASX 200 Index fell 73.10 points in its latest session, forming a bearish candlestick pattern accompanied by increased trading volume. This combination signals short-term caution among investors and highlights a prevailing bearish bias. Nevertheless, the index continues to trade above its 21-period Simple Moving Average (SMA), which now serves as immediate support. On the daily chart, a key support level is seen around 8,990; maintaining levels above this threshold could help consolidate recent gains and restore confidence in the broader uptrend. On the weekly chart, the index also remains above the 21-period SMA, a constructive sign pointing to the potential for sustained momentum over the longer term.


 Nov 12, 2026





 Please wait processing your request...