
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
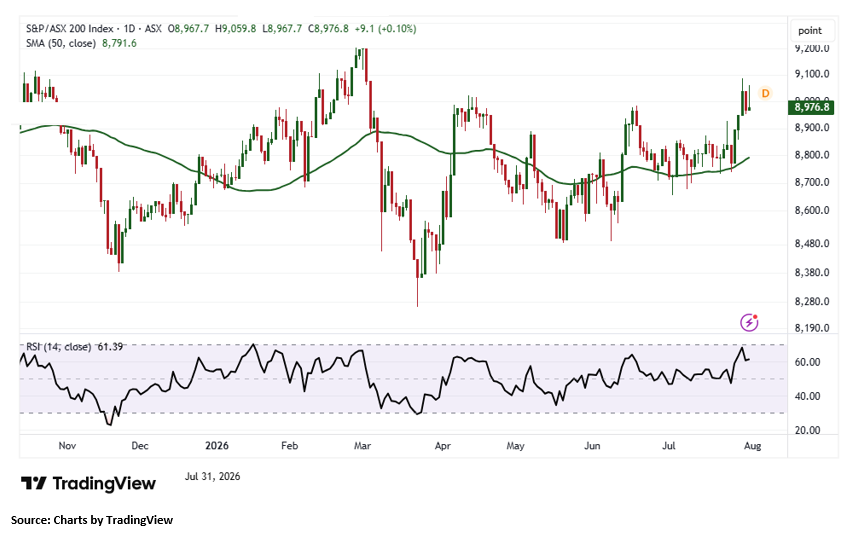
Index Update: The S&P/ASX 200 ended Friday modestly higher, adding 9.10 points, or 0.10%, to close at 8,976.80. The benchmark recovered part of the previous session’s decline as gains across Materials, Information Technology, Utilities and A-REITs outweighed broader sector weakness. Materials led the market with a 1.42% rise and extended its five-day gain to 1.97%. Health Care was the weakest sector, falling 1.84%, while Consumer Staples declined 1.26%. The ASX 200 gained 2.33% over five sessions, advanced 2.26% in July and remained 2.46% below its 52-week high.
Macro Update: According to data released by the Australian Bureau of Statistics (ABS), Australia’s Producer Price Index for final demand rose 1.3% in the June 2026 quarter and 3.6% over the year, marking the largest quarterly increase since September 2023. Higher energy costs, particularly for crude oil, petrol and diesel, drove the rise amid Strait of Hormuz disruptions and Middle East-related shipping delays. Manufacturing output prices increased 2.2%, led by petroleum and coal products, while building construction prices rose 1.4%. Road freight charges surged 15.5% due to higher fuel expenses, while rental demand remained another key contributor.
Top Market Movers: 4DMedical Limited (ASX:4DX) led the gains, rising 13.084% to AUD 3.630, followed by Megaport Limited (ASX:MP1), up 11.521% to AUD 18.100, and Silex Systems Limited (ASX:SLX), which advanced 10.287% to AUD 4.610. Among the decliners, Champion Iron Limited (ASX:CIA) fell 5.802% to AUD 3.410, Domino’s Pizza Enterprises Limited (ASX:DMP) dropped 5.207% to AUD 18.570, and DroneShield Limited (ASX:DRO) declined 4.238% to AUD 1.695.
Commodity Update: The Japanese yen weakened on Friday as investors continued to assess the impact of Japan's recent currency intervention while awaiting the Bank of Japan's upcoming policy decision for further direction. The U.S. dollar remained supported amid cautious market sentiment. Gold declined 0.44% to USD 4,082.00 per ounce, silver slipped 0.42% to USD 58.75 per ounce, and copper edged up 0.09% to USD 13,828.10 per metric ton. Brent crude oil rose 0.70% to USD 89.64 per barrel as renewed military clashes between the United States and Iran, along with widening regional tensions, intensified concerns over potential disruptions to Middle East oil supplies.
Our Stance: The ASX 200 closed slightly higher as strength in Materials and Technology helped offset weakness across several defensive sectors, indicating selective buying rather than broad-based market participation. Elevated producer price inflation, driven by higher energy and transport costs, suggests inflationary pressures remain present and could influence future monetary policy expectations. Meanwhile, ongoing geopolitical tensions in the Middle East continue to support oil prices and add uncertainty to the global outlook. Going forward, market direction is likely to depend on upcoming economic data, central bank developments, corporate earnings and commodity price trends, with investors expected to remain focused on sectors supported by resilient demand and favourable macroeconomic conditions.
The S&P/ASX 200 Index advanced 9.10 points in the latest trading session, forming a small bullish candlestick pattern that reflects renewed buying interest and improving investor sentiment. The index continues to maintain a constructive technical setup, with momentum indicators remaining supportive and suggesting that buyers are stepping in during market pullbacks, reinforcing the prevailing upward trend. From a technical perspective, immediate support is positioned near 8,900.70. As long as the index sustains above this key level, the broader bullish structure is expected to remain intact, increasing the likelihood of a retest of recent highs and continuation of the ongoing upward momentum. On the upside, a sustained breakout above the recent swing high would further strengthen the bullish outlook and potentially open the path for additional gains in the coming sessions.


 Nov 12, 2026





 Please wait processing your request...