
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Highlights
- Capstone Copper shares have gained approximately 63.65% over the past year amid stronger copper market sentiment.
- Q1 2026 adjusted EBITDA reached a record $329.1 million, marking the sixth consecutive quarter of record EBITDA generation.
- The company maintained full-year production guidance while advancing the Mantoverde Optimized and Santo Domingo projects.
Capstone Copper Corp. (ASX:CSC) has emerged as one of the stronger performers in the copper Mining sector over the past year, with its shares climbing nearly 63.65% annually as investors responded positively to improving copper prices, operational growth initiatives, and a series of record financial results. The company’s latest first-quarter 2026 performance reinforced that momentum, with Capstone reporting record adjusted EBITDA and adjusted Earnings Per Share despite operational disruptions earlier in the quarter.
The latest quarterly update has placed the company firmly on the radar of investors seeking exposure to the global copper market, especially as long-term Demand expectations remain tied to electrification, renewable energy infrastructure, and expanding industrial consumption. While broader Commodity markets continue to face geopolitical uncertainty and inflationary cost pressures, Capstone’s operational execution and growth pipeline are becoming increasingly central to the stock’s performance narrative.
Share Performance Reflects Strong Commodity Tailwinds
Capstone Copper’s share performance over the past 12 months has been closely linked to the rally in copper prices, which reached historically elevated levels during the first quarter of 2026. Copper has increasingly become a strategic industrial metal due to rising demand from electric vehicles, battery storage systems, grid modernization, and renewable energy installations.
The company’s stock has also benefited from improving investor confidence in diversified copper producers capable of scaling production while maintaining financial discipline. Capstone’s latest earnings report further strengthened that view as the company posted a significant turnaround in profitability compared with the same period last year.
The stock’s recent move higher followed the release of Q1 2026 results, where management highlighted its sixth consecutive quarter of record adjusted EBITDA. That consistency has helped position Capstone as a company transitioning from a development-heavy phase toward a stronger cash generation cycle.
Investors also appeared encouraged by the company’s ability to maintain annual guidance despite operational disruptions, including a 35-day strike at the Mantoverde operation during the quarter.
Record Earnings Reinforce Operational Momentum
Capstone Copper reported Net Income attributable to shareholders of $102.5 million for Q1 2026, compared with a net loss of $6.8 million in Q1 2025. Adjusted net income attributable to shareholders reached a record $94.8 million, while adjusted earnings per share climbed to $0.12.
The company’s adjusted EBITDA rose sharply to $329.1 million from $179.9 million a year earlier, primarily supported by stronger realized copper prices alongside higher gold and silver prices. The result marked another milestone in Capstone’s operational performance and highlighted the sensitivity of mining earnings to favorable commodity pricing conditions.
Although consolidated copper production declined year-over-year to 47,960 tonnes from 53,796 tonnes, the company was still able to offset lower production volumes through stronger realized pricing and improved Operating Cash Flow.
Operating cash flow before Working Capital changes increased to $217.9 million during the quarter, compared with $166.1 million in the prior-year period. That improvement further strengthened the company’s Balance Sheet and Liquidity profile.
Balance Sheet Improvements Add Financial Flexibility
One of the more notable developments during the quarter was Capstone’s decision to repay the remaining $30 million early deposit under its Gold Precious Metals Purchase Agreement with Wheaton Precious Metals.
The repayment eliminated associated liabilities and made the full $290 million commitment available for future development funding related to the Santo Domingo project. This move was viewed positively because it simplified future financing arrangements while reducing long-term obligations tied to the streaming agreement.
Net Debt declined to $737.5 million at the end of March 2026 from $780.1 million at the end of 2025. Meanwhile, total available liquidity exceeded $1 billion, supported by nearly $394 million in cash and substantial unused revolving Credit capacity.
The stronger liquidity position could become increasingly important as Capstone advances multiple growth initiatives simultaneously.
Growth Projects Remain Central to Long-Term Expectations
While recent share gains have largely been driven by copper prices and earnings growth, investor attention is increasingly shifting toward Capstone’s development pipeline and its ability to deliver incremental production growth over the coming years.
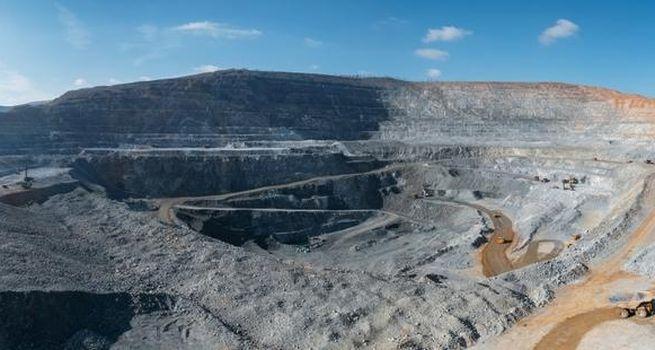
The Mantoverde Optimized Project remains one of the company’s most closely watched initiatives. Management confirmed that the project remains on schedule and within its estimated $176 million capital cost framework. Once completed, the project is expected to add approximately 20,000 tonnes of copper production annually along with additional gold output.
That expansion is particularly important because it represents a relatively capital-efficient brownfield development, allowing the company to Leverage existing infrastructure while increasing output capacity.
At the same time, Capstone continues advancing the Santo Domingo development project toward a future sanctioning decision. The project is viewed internally as a high-return growth opportunity and could materially strengthen the company’s future production profile if approved and developed according to plan.
Exploration efforts also remain focused on district-scale growth opportunities, suggesting that management continues to prioritize long-term resource expansion alongside near-term operational execution.
What Investors May Expect Ahead
Looking ahead, Capstone Copper’s share performance will likely remain heavily influenced by three major factors: copper price trends, operational consistency, and execution of its expansion projects.
Copper market fundamentals continue to appear supportive as Supply constraints persist across several producing regions globally. Many analysts expect structural copper demand growth to continue over the medium term due to the global energy transition and infrastructure modernization trends. If copper prices remain elevated, Capstone could continue benefiting from strong cash generation and improving profitability metrics.
However, operational reliability will remain critical. The strike-related disruption at Mantoverde highlighted the sensitivity of mining companies to labor challenges and production interruptions. Investors will likely monitor whether Capstone can maintain stable production levels across its operations during the remainder of 2026.
Cost Inflation also remains a Factor to watch. Management acknowledged ongoing pressure from higher diesel and sulphuric acid prices linked partly to geopolitical tensions in the Middle East. While the company has not reported inventory or operational disruptions so far, persistent inflationary pressures could weigh on margins if commodity prices moderate.
Still, Capstone’s unchanged 2026 production guidance of 200,000 to 230,000 tonnes of copper suggests management remains confident in operational recovery during the remaining quarters of the year.
Copper Sector Positioning Continues to Support Sentiment
Capstone Copper’s recent share appreciation also reflects broader investor appetite for copper-focused mining companies amid expectations of tighter future supply. Compared with diversified miners, pure-play and growth-oriented copper producers have attracted increasing market attention due to the strategic importance of the metal.
The company’s ability to generate record EBITDA while simultaneously funding future growth projects has strengthened its standing among mid-tier copper producers. Investors are increasingly evaluating companies not only on current production but also on future scalability and reserve growth potential.
Capstone’s ongoing expansion strategy, coupled with improving financial performance, positions the company as a notable participant in that evolving industry landscape.
Conclusion
Capstone Copper’s strong share performance over the past year has been supported by a combination of higher copper prices, improving operational execution, record earnings growth, and confidence in its long-term expansion pipeline. The company’s Q1 2026 results reinforced that momentum by delivering record adjusted EBITDA and stronger cash flow despite temporary production disruptions. Looking ahead, the company’s ability to maintain operational stability, manage inflationary pressures, and successfully execute projects such as Mantoverde Optimized and Santo Domingo will likely shape investor sentiment. As global copper demand trends continue to strengthen, Capstone remains closely positioned within one of the mining sector’s most strategically important commodity markets.


 Nov 13, 2026





 Please wait processing your request...