
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 rose 55.70 points or 0.64% to 8,716.60 on Friday, moving above its 20-day moving average. Nine sectors advanced, led by information technology at 2.23%, followed by consumer discretionary at 2.16%. Telecommunications services fell 0.57%, while utilities rose 1.75% during the session. The index added 0.40% over five days while remaining virtually unchanged year to date.
Macro Update: US-Iran peace efforts remain divided over uranium enrichment, reopening the Strait of Hormuz and the conflict’s impact on oil prices. According to reports, Donald Trump predicted a swift end to the war and lower crude prices, while Vice President JD Vance called for tangible reductions in Iran’s enrichment capability. Tehran proposed a seven-day plan to reopen the waterway, which Trump rejected before US officials presented a counterproposal. Restoring dependable commercial shipping remains central to easing energy Supply concerns.
Top Market Movers: Among the leading gainers on the ASX, Generation Development Group Limited (ASX:GDG) rose AUD 0.190 (7.307%) to AUD 2.790; West African Resources Limited (ASX:WAF) gained AUD 0.190 (5.428%) to AUD 3.690; and Lovisa Holdings Limited (ASX:LOV) advanced AUD 1.130 (5.035%) to AUD 23.570. Among the top three losers, Weebit Nano Ltd (ASX:WBT) fell AUD 0.350 (11.112%) to AUD 2.800; Sunrise Energy Metals Limited (ASX:SRL) declined AUD 2.130 (11.048%) to AUD 17.150; and Deep Yellow Limited (ASX:DYL) dropped AUD 0.075 (7.109%) to AUD 0.980.
Commodity Update: The US dollar weakened on Friday, while declining Treasury yields increased the appeal of precious metals amid persistent Inflation concerns linked to higher oil prices. Gold gained 1.00% to USD 4,198.50, silver advanced 1.59% to USD 60.35, and copper rose 0.85% to USD 14,456.80. Brent Crude oil declined 0.70% to USD 103.53 as Middle East supply concerns eased after Donald Trump said the US would not attack Iran before the elections, citing ongoing talks to end the conflict.
Our Stance: The S&P/ASX 200’s 0.64% gain reflects improving market sentiment, supported by advances across nine sectors and renewed interest in technology and consumer discretionary stocks. However, geopolitical uncertainty surrounding US-Iran negotiations and potential disruptions to energy supplies could sustain market volatility. Rising precious metal prices indicate continued Demand for defensive assets, while elevated Crude Oil prices pose inflationary risks. Despite the index moving above its 20-day moving average, limited year-to-date gains suggest a cautious market environment. Near-term market direction may depend on developments in Middle East diplomacy, Commodity price movements, inflation expectations and broader global economic conditions.
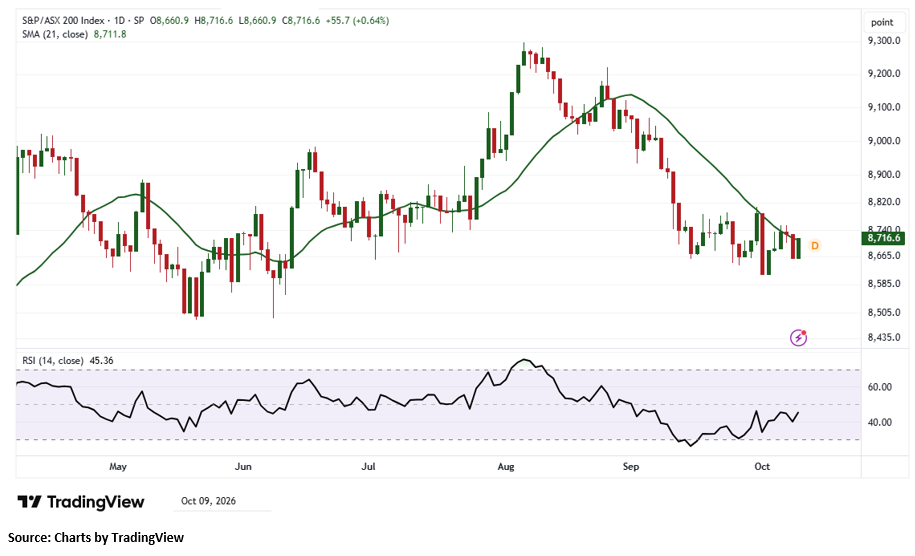
On the technical front, the S&P/ASX 200 Index advanced in the latest trading session, maintaining a constructive near-term outlook despite the recent pullback. The index continues to hold above key support at 8,670.50, which remains critical to preserving the prevailing bullish structure. Sustained trading above this level could support a recovery toward recent highs, while a decisive breakdown may increase downside risks. On the upside, a breakout above the immediate resistance near 8,750.60 could strengthen bullish momentum and open the way for further gains toward the next target of 8,800.


 Nov 12, 2026





 Please wait processing your request...