
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed higher on Thursday, rising 28.70 points, or 0.32%, to 9,043.50, marking a new 50-day high. Over the past five days, the index gained 1.74% and remains 0.79% below its 52-week high. The index is up 3.24% over the past month. Sector performance was mixed, with more sectors ending lower than higher despite the index gain. Utilities led the market, up 2.89% on the day and 3.86% over the past five days. It was followed by Financials (+2.56%), with smaller advances in Materials (+1.13%) and Consumer Staples (+0.79%). Information Technology (-6.19%) and Health Care (-5.45%) were the weakest performers. Consumer Discretionary (-2.13%), A-REITs (-1.96%), Telecommunication Services (-1.54%), Industrials (-0.87%), and Energy (-0.18%) also declined.
Macro Update: The US labour market showed a firmer start to the year, with employers adding 130,000 jobs in January, above expectations. The unemployment rate edged down to 4.3%, while wage growth exceeded projections. Markets shifted Federal Reserve rate-cut expectations to July. However, revisions trimmed total 2025 payroll growth to 181,000, marking the weakest annual pace since the pandemic. While the data eased some concerns around labour demand, analysts cautioned that seasonal factors may have flattered January figures, with other surveys still signalling softness in hiring momentum.
Top Market Movers: Top gainers of Thursday were ANZ Group Holdings (ASX:ANZ), climbing to AUD 40.350, up AUD 3.150 (8.467%), Commonwealth Bank of Australia (ASX:CBA), rising to AUD 178.740, up AUD 9.180 (5.414%), and Northern Star Resources (ASX:NST), ending at AUD 29.390, up AUD 1.130 (3.998%). Top decliners were Temple & Webster (ASX:TPW), falling to AUD 7.640, down AUD 3.700 (32.628%), AMP (ASX:AMP), slipping to AUD 1.280, down AUD 0.465 (26.648%), and Pro Medicus (ASX:PME), closing at AUD 129.000, down AUD 40.470 (23.881%).
Commodity Update: The U.S. dollar edged higher against most major currencies, supported by stronger-than-expected jobs data that tempered near-term rate cut expectations ahead of Friday’s inflation report. Gold slipped 0.22% to USD 5,086.60, while silver declined 0.60% to USD 83.44. Copper was steady, up 0.01% at USD 13,247.00. Brent crude gained 0.40% to USD 69.64 amid ongoing U.S.–Iran tensions, though rising U.S. inventories capped further upside.
Our Stance: The S&P/ASX 200 ended Thursday higher, rising 28.70 points to 9,043.50, a new 50-day high, with gains of 1.74% over five days and 3.24% over the past month. Sector performance was mixed, with Utilities and Financials leading, while Information Technology and Health Care lagged. Offshore, US jobs data surprised to the upside, easing immediate growth concerns but pushing rate-cut expectations to July. Market leadership was narrow, with banks and miners outperforming, while select consumer and healthcare names saw sharp declines. Commodity moves were modest, reflecting cautious positioning ahead of inflation data. Overall, near-term momentum remains supported, but uneven sector breadth and macro uncertainty warrant selective positioning and disciplined risk management.
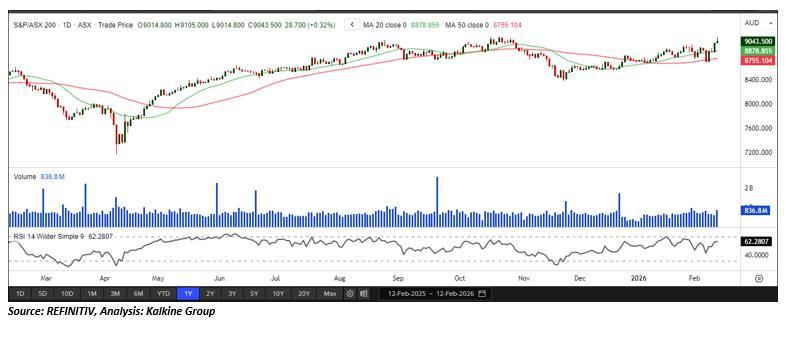
In the latest session, the S&P/ASX 200 Index advanced 28.70 points to close at 9,043.50, forming a bullish candlestick on elevated trading volumes—an indication of strong investor confidence and healthy market participation. On the daily chart, the index continues to trade comfortably above its 21-period SMA, which is acting as key dynamic support and reinforcing the short-term uptrend. Immediate support is seen near 8,960.70, and holding above this level would help preserve the bullish structure while allowing for consolidation or further upside. A decisive break below this support could introduce short-term volatility. On the weekly chart, the index remains well above its 21-period SMA, highlighting a robust medium- to long-term trend and confirming that the broader market bias remains positive despite near-term fluctuations.


 Nov 12, 2026





 Please wait processing your request...