
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 closed higher on Thursday, rising 87.70 points or 1.00% to 8,826.50 after recently touching a 20-day low. Despite today’s rebound, the index remains 1.71% lower over the past five sessions and is trading 2.52% below its 52-week high. Gains were broad-based, with 9 of 11 sectors finishing in positive territory. The Financial sector led the advance, up 1.71%, recovering from recent weakness but still down 1.99% over five days. Consumer Discretionary (+1.39%) and Information Technology (+1.28%) also contributed to the upside.
Macro Update: Household spending in Australia rose 0.5% in July 2025, according to seasonally adjusted data released by the Australian Bureau of Statistics (ABS). This follows increases of 0.3% in June and 1.0% in May, reflecting steady consumer activity. The seasonally adjusted balance on goods climbed by AUD 1.94 billion, with goods credits (exports) up AUD 1.45 billion (3.3%), driven mainly by non-rural goods. Goods debits (imports) fell AUD 490 million (1.3%), largely due to lower non-monetary gold imports. On a year-on-year basis, household spending rose 5.1% compared to July 2024.
Top Market Movers: IRESS Limited (ASX: IRE) led the gainers, rising AUD 0.59 (6.97%) to close at AUD 9.05, followed by Deep Yellow Limited (ASX: DYL) up 6.35% and Boss Energy Ltd (ASX: BOE) up 5.76%. On the downside, Megaport Limited (ASX: MP1) dropped AUD 0.95 (6.34%), while Bellevue Gold Limited (ASX: BGL) and HMC Capital Limited (ASX: HMC) fell 3.85% and 3.68% respectively.
Commodity Update: The U.S. dollar eased Thursday amid bond market jitters and weak labour data, bolstering expectations of a Fed rate cut this month. Commodities traded lower, with gold down 1.06% at USD 3,597.30, silver off 1.82% at USD 41.29, and copper easing to USD 9,932.70. Brent crude slipped 0.40% to USD 67.35, pressured by reports of a potential OPEC+ output hike and rising U.S. oil inventories, raising concerns over softer fuel demand.
Our Stance: The S&P/ASX 200 has rebounded 1.0% to 8,826.50 after hitting a 20-day low, with Financials, Consumer Discretionary, and IT leading broad-based gains. Despite the bounce, the index remains 1.71% lower over five sessions and 2.52% below its 52-week high, suggesting a cautious market tone. Macro data shows household spending rising 0.5% in July, supported by higher exports and lower gold imports, reflecting resilient demand. However, softer commodities, especially gold and oil, hint at weaker global sentiment. The index’s recovery can be viewed as a short-term relief rally, with further upside contingent on improving risk appetite and clarity on U.S. Fed policy.
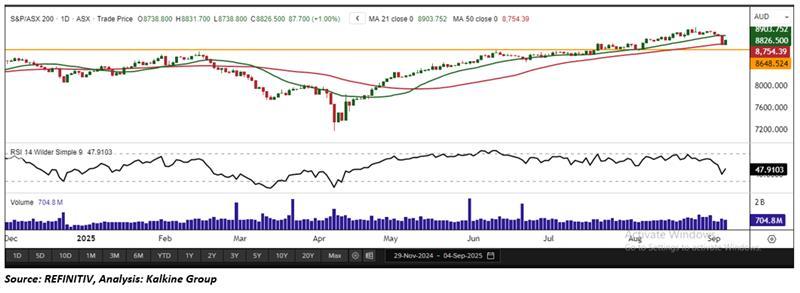
In its latest session, the S&P/ASX 200 Index advanced 87.80 points to close at 8,826.50, underpinned by a bullish candlestick formation coupled with strong trading volumes clear signals of sustained investor confidence. The index continues to hold firmly above its 21-period Simple Moving Average (SMA) on the daily chart, a dynamic support level that reinforces the prevailing positive short-term outlook. A critical support zone is established at 8,670.70. Maintaining levels above this area will be essential in protecting the integrity of the uptrend. On the upside, a decisive breakout above this support-turned-resistance level could be viewed as a strong bullish confirmation, potentially unlocking further upward momentum and shifting broader market sentiment decisively in favor of the bulls. From a wider perspective, the index’s sustained position above the 21-period SMA on the weekly chart highlights its resilient long-term bullish foundation.


 Nov 12, 2026





 Please wait processing your request...