
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
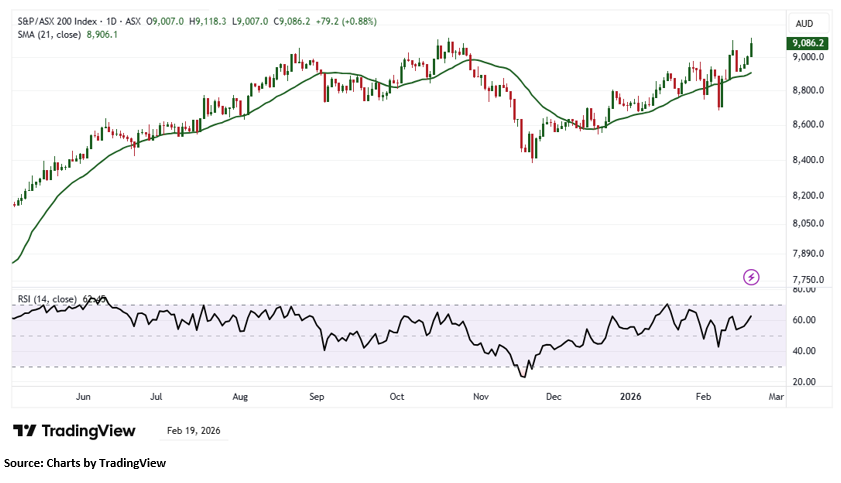
Index Update: The S&P/ASX 200 closed up on Thursday, rising 79.20 points or 0.88% to 9,086.20, marking a new 100-day high. Over the past five days, the index has climbed 0.47%, currently sitting just 0.35% below its 52-week peak. Eight of the 11 sectors finished in positive territory. Energy led the charge with a strong gain of +3.80%, also up +2.09% over the last five days. Telecommunications Services (+2.25%) and Health Care (+1.73%) also contributed to the broad-based advance, while Consumer Discretionary (-2.99%) and A-REITs (-2.46%) were the main laggards.Other notable movers included Financials (+1.44%), Information Technology (+1.39%), and Materials (+1.33%), reflecting steady buying across key sectors.
Macro Update: The Australian Bureau of Statistics (ABS) reported the seasonally adjusted unemployment rate remained steady at 4.1 per cent in January. Employment increased by 18,000, driven by a 50,000 rise in full-time positions, partially offset by a 33,000 fall in part-time work. The participation rate fell to 66.7 per cent, 0.6 points below the January 2025 record. Underemployment rose 0.2 points to 5.9 per cent, while overall underutilisation climbed to 10.0 per cent. The Wage Price Index grew 0.8 per cent quarterly and 3.4 per cent annually, reflecting steady wage growth consistent with the September 2025 quarter.
Top Market Movers: The ASX saw notable movements today with HUB24 Limited (ASX:HUB) leading gains, climbing to AUD 98.45, up AUD 12.21 (14.16%), followed by Sonic Healthcare Limited (ASX:SHL) at AUD 23.34, up AUD 2.10 (9.89%), and Karoon Energy Ltd (ASX:KAR) rising to AUD 1.685, up AUD 0.15 (9.77%). On the downside, Zip Co Limited (ASX:ZIP) fell sharply to AUD 1.85, down AUD 0.97 (-34.40%), while Lovisa Holdings Limited (ASX:LOV) and Medibank Private Limited (ASX:MPL) dropped AUD 3.97 (-12.80%) and AUD 0.27 (-5.64%) respectively.
Commodity Update: The U.S. dollar edged higher on Thursday after minutes from the Federal Reserve indicated policymakers remain cautious, keeping the possibility of further rate action on the table. Sterling weakened as data pointed to moderating UK inflation. In commodities, gold declined 0.42% to USD 4,988.30, silver fell 0.69% to USD 77.06, and copper slipped 0.45% to USD 12,871.60. Brent crude eased 0.20% to USD 70.23, consolidating after the previous session’s sharp 4% surge.
Our Stance: The S&P/ASX 200 climbed to a new 100-day high, rising 0.88% to 9,086.20, with broad-based gains across most sectors. Over the past five days, the index added 0.47% and remains just 0.35% below its 52-week peak. Positive momentum was driven by energy, telecommunications, and health care, while consumer discretionary and real estate sectors lagged. On the macro front, employment rose by 18,000, keeping the unemployment rate steady at 4.1%, and wage growth remained consistent at 3.4% annually. Commodity markets saw mild declines, with gold, silver, copper, and crude oil easing slightly. Overall, the market momentum appears stable, supported by resilient economic data, but volatility may persist.
The S&P/ASX 200 advanced 79.20 points to finish at 9,086.20, forming a bullish candlestick on strong volume, underscoring firm investor confidence and healthy participation. On the daily chart, the index continues to trade comfortably above its 21-period SMA, which acts as dynamic support and sustains the short-term uptrend. Immediate support is positioned near 9,000.80; holding above this threshold would preserve the constructive structure and support further upside or consolidation. However, a clear break below could introduce short-term volatility. On the weekly timeframe, the index remains well above its 21-period SMA, reinforcing a solid medium- to long-term bullish trend.


 Nov 12, 2026





 Please wait processing your request...