
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: Australian shares closed lower on Thursday, with the S&Amp;P/ASX 200 falling 99.60 points, or 1.13%, to 8,686.10 as weakness in Mining stocks weighed on sentiment. Materials led sector losses, declining 3.19%, after iron ore prices fell to a two-month low amid rising shipments from Guinea’s Simandou mine. Telecommunications Services (-2.21%) and Information Technology (-1.87%) also underperformed.
Investor caution was further heightened by renewed US-Iran clashes, raising concerns over the fragile Middle East ceasefire. Despite the broader sell-off, defensive sectors attracted buyers, with Utilities leading gains at 1.33%, followed by Consumer Staples (+1.03%) and Health Care (+0.78%). The benchmark index remains up 1.08% over the past five trading sessions.
Macro Update: Australian residential Mortgage balances continued to grow in the March 2026 quarter, while stronger exports boosted the nation's Trade Surplus in April, according to the latest data from the Australian Bureau of Statistics (ABS).
Total residential mortgages increased by AUD 7.1 billion, or 4.4%, to AUD 168.8 billion during the March quarter. Domestic issuance of asset-backed long-term Debt securities also rose by AUD 9.0 billion, or 4.5%, to AUD 206.6 billion. Meanwhile, total Assets held by Australian securitisers increased by AUD 7.5 billion, or 3.4%, to AUD 228.9 billion.
Separately, Australia's seasonally adjusted trade balance improved by AUD 2.8 billion in April. Goods exports rose AUD 3.18 billion, or 7.2%, driven primarily by higher exports of metal ores and minerals. Imports increased by AUD 365 million, or 0.8%, largely due to higher purchases of fuels and lubricants.
Top Market Movers: Treasury Wine Estates Limited (ASX:TWE) led the gains on Thursday, rising AUD 0.54, or 13.11%, to close at AUD 4.66. Telix Pharmaceuticals Limited (ASX:TLX) advanced AUD 0.69, or 5.66%, to AUD 12.89, while Ampol Limited (ASX:ALD) gained AUD 1.42, or 4.06%, to finish at AUD 36.38.
Among the laggards, Vulcan Energy Resources Limited (ASX:VUL) fell AUD 0.33, or 8.59%, to AUD 3.51. Pantoro Gold Limited (ASX:PNR) declined AUD 0.25, or 8.20%, to AUD 2.80, while Paladin Energy Ltd (ASX:PDN) dropped AUD 0.97, or 8.19%, to close at AUD 10.88.
Commodity Update: Global commodity and currency markets remained focused on escalating Middle East tensions, supporting safe-haven Demand and keeping the U.S. dollar near a two-month high. Gold advanced 0.77% to USD 4,502.90, while silver gained 0.17% to USD 73.82. Copper edged lower by 0.06% to USD 13,788.90 amid cautious sentiment. Brent Crude declined 0.70% to USD 97.16, snapping a three-session rally as traders booked profits despite ongoing geopolitical risks and signs of tightening U.S. crude inventories. Risk appetite remained subdued across broader financial markets.
Our Stance: The Australian market faced a broad risk-off session, with weakness in mining stocks and softer iron ore prices outweighing encouraging domestic economic indicators. While the S&P/ASX 200 retreated 1.13%, the latest Australian Bureau of Statistics data showed continued growth in residential mortgages, securitisation activity and a stronger trade balance driven by higher exports, highlighting underlying resilience in parts of the economy. Investor sentiment was nevertheless impacted by renewed geopolitical tensions in the Middle East, which supported safe-haven assets such as gold and kept risk appetite subdued. The outperformance of Utilities, Consumer Staples and Health Care suggests investors rotated toward defensive sectors amid heightened uncertainty. Going forward, commodity price movements, global geopolitical developments and the sustainability of export growth are likely to remain key drivers of market direction.
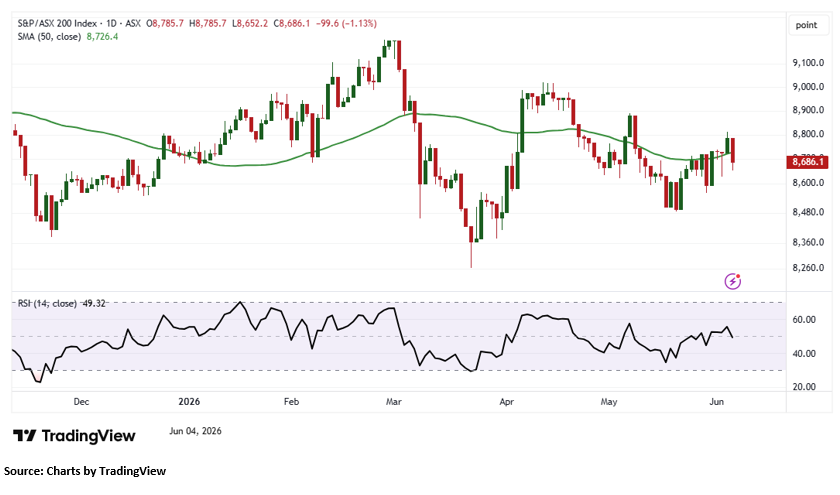
The S&P/ASX 200 declined by 99.60 points in the latest Trading session, forming a bearish candlestick pattern that reflects weakening short-term market sentiment. From a technical perspective, the index continues to trade below its 21-day Simple Moving Average (SMA), which remains an important dynamic resistance level and is limiting near-term upside momentum. Immediate support is located around the 8,600.00 level, and holding above this area could help stabilize sentiment and preserve the broader market structure. Conversely, a decisive break below 8,600.00 may weaken the current technical outlook, potentially triggering a deeper corrective phase and increasing near-term market Volatility. Overall, the index remains vulnerable to further downside pressure while trading below its 21-day SMA, although sustained support above 8,600.00 could provide a foundation for a potential recovery.


 Nov 12, 2026





 Please wait processing your request...