
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: The ASX 200 finished Thursday’s session higher, rising 125.10 points or 1.47% to close at 8,621.70 after earlier touching a new 20-day low. Despite the strong daily gain, the benchmark index remained largely flat over the past five trading sessions and is down 1.06% since the start of the year. Australian equities recorded their strongest one-day advance in six weeks as softer-than-expected labour market data increased expectations that the Reserve Bank of Australia may avoid further Interest Rate hikes. Eight of the index’s 11 sectors closed in positive territory, with the Materials sector leading gains, climbing 2.56% after recent weakness. However, the sector remains down 5.31% over the past five days.
Macro Update: Australia’s labour market weakened in April, with the seasonally adjusted Unemployment rate rising to 4.5%, according to the Australian Bureau of Statistics (ABS). Employment declined by 19,000 people during the month, while unemployment increased by 33,000. The number of unemployed Australians seeking full-time work rose by 11,000, while those looking for part-time roles increased by 22,000. Both full-time and part-time employment also recorded declines.
Meanwhile, a new UNCTAD report highlighted that the global economy remained resilient entering 2026, supported by trade and AI-driven Investment, but warned geopolitical tensions and rising costs could slow global growth to 2.6% in 2026.
Top Market Movers: Top gainers on the ASX included Guzman y Gomez Limited (ASX:GYG), which surged 13.00% to AUD 18.080, followed by IGO Limited (ASX:IGO), up 7.464% to AUD 9.070, and Judo Capital Holdings Limited (ASX:JDO), which gained 6.463% to AUD 1.400. On the losing side, Predictive Discovery Limited (ASX:PDI) fell 4.606% to AUD 0.725, while REA Group Ltd (ASX:REA) declined 3.666% to AUD 158.470. Yancoal Australia Limited (ASX:YAL) also weakened, dropping 3.449% to AUD 6.720.
Commodity Update: The U.S. dollar reversed lower on Thursday as improving risk sentiment reduced safe-haven Demand after President Donald Trump said Washington was in the “final stages” of peace talks with Iran. Trump also stated the U.S. was prepared to strike Iran if no agreement was reached, although he indicated willingness to delay further military action amid ongoing negotiations with Tehran. Gold declined 0.23% to USD 4,535.20 per ounce, silver fell 0.79% to USD 75.60, copper slipped 0.13% to USD 13,615.90, while Brent Crude gained 0.50% to USD 105.53 per barrel.
Our Stance: The S&P/ASX 200 rebounded notably on Thursday, rising 1.47% to 8,621.70 as weaker-than-expected Australian labour market data fuelled expectations that the Reserve Bank of Australia may keep rates steady. Gains were broad-based, with eight of 11 sectors finishing higher and Materials leading the advance despite remaining lower over the past week. Market sentiment was also supported by easing safe-haven demand after progress in U.S.-Iran peace discussions improved risk appetite. However, softer employment figures, slowing global growth forecasts from UNCTAD, and ongoing geopolitical uncertainties continue to highlight a cautious macro backdrop, suggesting investors may remain selective despite the market’s near-term rebound momentum.
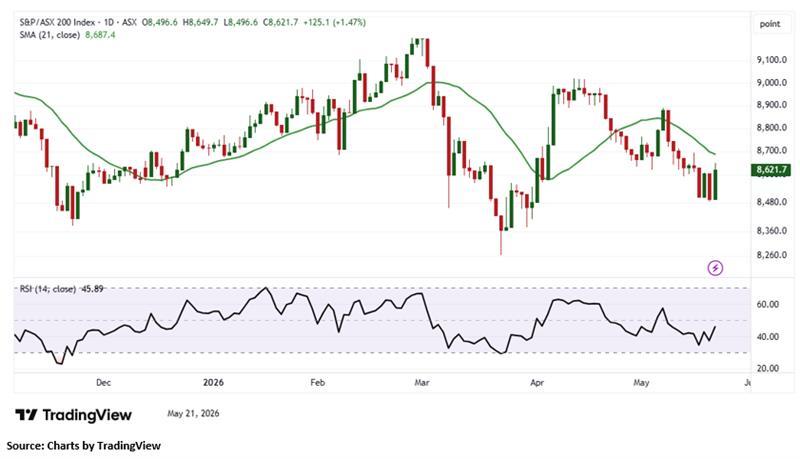
The S&P/ASX 200 Index advanced 125.10 points in the latest session, forming a bullish candlestick pattern that reflects renewed buying interest and improving short-term market sentiment. Despite the strong rebound, the index continues to trade below its 21-day Simple Moving Average (SMA), which remains a key dynamic resistance level and could continue to cap near-term upside momentum. From a technical perspective, immediate support is positioned near the 8,530 level. Holding above this zone would help preserve the broader short-term upward structure and support further stabilization in market sentiment. However, a decisive move below the 8,500 mark could weaken the current technical setup, increasing the likelihood of a deeper corrective phase accompanied by heightened Volatility and a more cautious near-term outlook.


 Nov 12, 2026





 Please wait processing your request...