
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Image Source : Krish Capital Pty Ltd
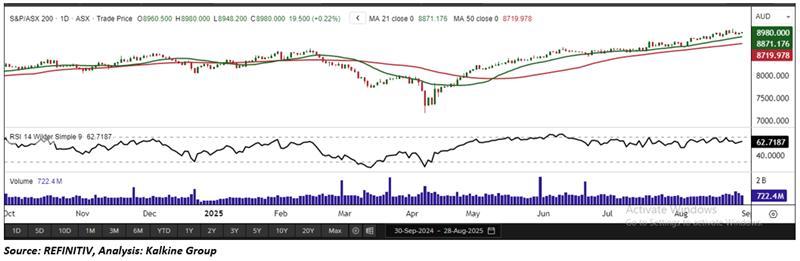
Index Update: The S&P/ASX 200 closed higher on Thursday, adding 19.50 points or 0.22% to finish at 8,980.00. Despite the gain, the index is down 0.43% over the past five sessions and remains 0.82% below its 52-week peak. Six of eleven sectors advanced, led by Financials, which climbed 1.10% and is up 0.08% over five days. A-REITs (+0.99%), Industrials (+0.89%), and Consumer Staples (+0.88%) also supported the gains. In contrast, Energy (-2.39%) and Health Care (-1.72%) weighed on the market, with Information Technology (-1.05%) and Materials (-0.54%) also weaker.
Macro Update: Private new capital expenditure (capex) edged up 0.2% in the June quarter 2025 and was 1.7% higher than a year earlier, seasonally adjusted, according to Australian Bureau of Statistics (ABS) data. Non-mining investment rose 0.9%, offsetting a 1.4% decline in mining. By asset type, equipment, plant, and machinery increased 0.3%, while buildings and structures lifted 0.2%. Forward-looking Estimate 3 for 2025–26 came in at AUD 174.8bn, 12.0% higher than Estimate 2, highlighting stronger planned investment momentum.
Top Market Movers: IDP Education Limited (ASX: IEL) led the gains, surging 29.74% to AUD 5.89, followed by Lifestyle Communities Limited (ASX: LIC), up 14.92% at AUD 5.93, and Eagers Automotive Limited (ASX: APE), which advanced 12.02% to AUD 25.26. On the downside, Telix Pharmaceuticals Limited (ASX: TLX) slumped 18.75% to AUD 14.95, Nine Entertainment Co. Holdings Limited (ASX: NEC) dropped 12.23% to AUD 1.62, while Ramsay Health Care Limited (ASX: RHC) declined 10.50% to AUD 34.09.
Commodity Update: The dollar slipped Thursday as traders priced in a possible Fed rate cut next month after New York Fed chief John Williams hinted at easing, while President Trump’s push to oust Fed Governor Lisa Cook added pressure. Gold rose 0.34% to USD 3,444.82, silver 0.49% to USD 38.883, and copper 0.38% to USD 9,800.05. Brent crude fell 0.33% to USD 66.99, weighed by softer U.S. fuel demand outlook and tariff-driven supply concerns.
Our Stance: The ASX 200’s modest rebound to 8,980 masks deeper cross-currents: financials and real estate drove gains, while energy and health care dragged, underscoring investors’ cautious sector rotation. Encouragingly, ABS data shows business capex edging higher with strong forward estimates, suggesting confidence in future investment despite mining weakness. Yet, sharp stock-specific swings—from IDP Education’s surge to Telix Pharmaceuticals’ slump—reveal a market increasingly driven by micro-catalysts rather than broad momentum. Globally, softer commodities and Fed rate cut bets highlight macro uncertainty.
In the latest session, the S&P/ASX 200 Index gained 19.50 points to close at 8,980.00, forming a small bullish candlestick pattern that reflects continued buying interest. The index remains positioned above its 21-period Simple Moving Average (SMA) on the daily chart, reinforcing short-term bullish sentiment. On a broader view, the index is also holding above the 21-period SMA on the weekly chart, providing a robust technical foundation for potential long-term gains. Looking ahead, a critical level to monitor is resistance at 9,054.20. A decisive breakout above this threshold could signal a meaningful upward shift, strengthening the prevailing uptrend and reinforcing a positive market outlook. Sustaining momentum beyond this level would open the door to further advances and bolster investor confidence in the near term.


 Nov 12, 2026





 Please wait processing your request...