
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
index Update: The S&P/ASX 200 closed Monday lower, slipping 31.00 points, or 0.33%, to 9,232.60 as the market retreated from near-record levels. Despite the benchmark’s decline, seven of 11 sectors finished higher, led by Telecommunications Services, which gained 1.70%, followed by Health Care and Materials. Financials fell 2.27%, weighing heavily on the index. Arena REIT and Westpac Banking Corporation were among the biggest decliners. The ASX 200 remains 2.36% higher over five sessions and just 0.69% below its 52-week high, with attention now turning to Tuesday’s Reserve Bank of Australia interest-rate decision and the developing Earnings season.
Macro Update: In Australia, attention is turning to Tuesday’s Reserve Bank decision. Following better-than-expected Inflation data, most economists expect the RBA to leave interest rates unchanged. However, resilient household spending and continued price pressure in domestically driven parts of the CPI have kept the risk of further tightening alive, with a small minority of economists still seeing the possibility of a rate increase.
Meanwhile, U.S. President Donald Trump said Washington is adopting a lower-key stance towards Iran, with the administration currently relying on economic pressure rather than signalling another major military offensive. Trump said the U.S. is only “semi-negotiating” with Tehran as talks involving Iran, Oman and Washington over reopening the Strait of Hormuz remain stalled. Iran is seeking measures including an end to the U.S. naval blockade and the Withdrawal of American forces from around the country.
Top Market Movers: CAR Group Limited (ASX:CAR) led the gainers, rising 9.92% to AUD 29.70. Minerals 260 Limited (ASX:MI6) advanced 7.24% to AUD 0.815, while SEEK Limited (ASX:SEK) gained 6.87% to close at AUD 16.48. Arena REIT (ASX:ARF) led the decliners, falling 21.95% to AUD 2.56. Westpac Banking Corporation (ASX:WBC) dropped 5.88% to AUD 35.70, while Codan Limited (ASX:CDA) declined 4.73% to AUD 39.12.
Commodity Update: The U.S. dollar remained near a two-month low against major currencies as markets focused on upcoming inflation data for signals on the Federal Reserve’s interest-rate outlook. Gold declined 0.47% to USD 4,370.40, while silver edged 0.04% higher to USD 63.52 and copper gained 0.18% to USD 14,062.00. Brent Crude oil advanced 1.10% to USD 84.45, supported by continued uncertainty surrounding the Strait of Hormuz reopening and renewed geopolitical tensions following reported attacks on Saudi energy infrastructure.
Our Stance: The ASX 200 slipped 0.33% to 9,232.60 on Monday, with weakness in Financials offsetting gains across seven sectors. CAR Group, Minerals 260 and SEEK led the gainers, while Arena REIT, Westpac and Codan declined. Attention now shifts to Tuesday’s RBA decision, where most economists expect rates to remain unchanged despite lingering domestic inflation pressures. Global sentiment is also being shaped by developments around Iran and the Strait of Hormuz, while Brent crude remains elevated. Near-record index levels leave the market sensitive to any surprise from the RBA, earnings updates or geopolitical developments.
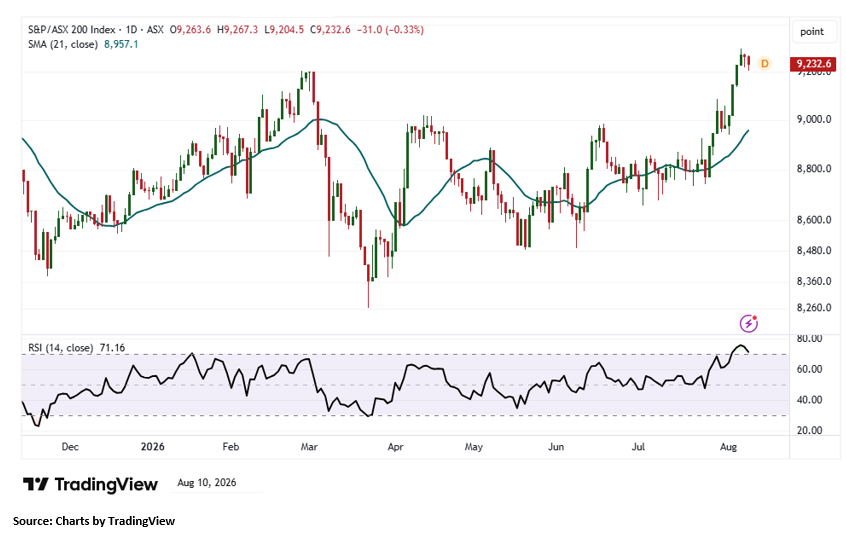
The S&P/ASX 200 Index declined 31.00 points in the latest Trading session , forming a bearish candlestick pattern. Despite the pullback, the index continues to maintain a constructive technical structure, with momentum indicators remaining supportive and suggesting that buyers are stepping in on market dips, reinforcing the prevailing uptrend. From a technical perspective, immediate support is positioned near 9,150.60. As long as the index sustains above this key support zone, the broader bullish outlook remains intact, increasing the likelihood of further upside and a potential retest of recent highs. A decisive breakout above the recent swing high near 9,150.60 would further strengthen the bullish setup and potentially pave the way towards the next resistance level around 9,340.50 in the upcoming sessions.


 Nov 12, 2026





 Please wait processing your request...