
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Image Source : Krish Capital Pty Ltd
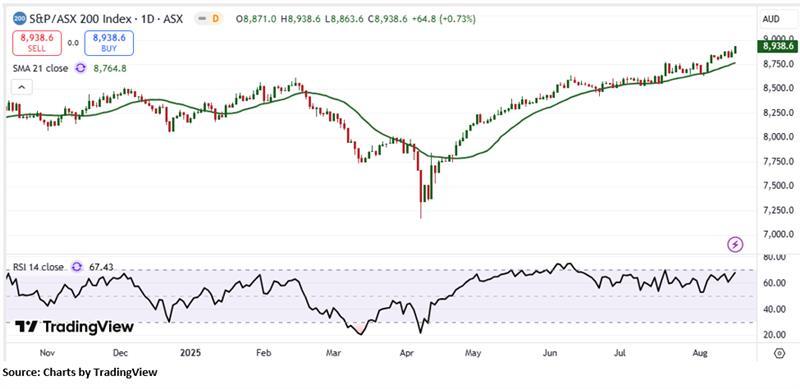
Index Update: The S&P/ASX 200 closed higher on Friday, adding 64.80 points or 0.73% to finish at 8,938.60, marking a new 100-day high and its fifth consecutive record close. Over the past five sessions, the index has gained 1.49% and remains at its 52-week peak. Gains were driven by optimism around further Reserve Bank easing following steady July jobs data and the recent rate cut. Nine of the eleven sectors ended in positive territory, with the Energy sector recording a rise of 1.14% on the day and 0.69% for the week.
Macro Update: China’s retail sales and industrial production grew at a slower pace than expected in July, official data showed on Friday, highlighting ongoing trade pressures and subdued consumer spending. Retail sales, a key indicator of domestic demand, rose 3.7% YoY, according to the National Bureau of Statistics.
In Australia, July labour force data from the Australian Bureau of Statistics showed that the unemployment rate was steady at 4.2%, while the participation rate edged higher to 67.1%. In July 2025, employment rose to 14,659,300, with the employment-to-population ratio unchanged at 64.2%. The underemployment rate held at 5.9%, and monthly hours worked climbed to 1,988 million.
Top Market Movers: Ampol Limited (ASX: ALD) led the ASX 200 gains on Friday, jumping 7.68% to close at AUD 29.15. IDP Education Ltd (ASX: IEL) followed with a 5.79% rise to AUD 4.57, while Liontown Resources Ltd (ASX: LTR) advanced 5.63% to finish at AUD 0.845. On the downside, Temple & Webster Group Ltd (ASX: TPW) tumbled 11.71% to AUD 25.03, Amcor Plc (ASX: AMC) slid 9.70% to AUD 13.60, and Corporate Travel Management Ltd (ASX: CTD) fell 5.64% to AUD 15.57.
Commodity Update: The dollar held steady on Friday after stronger-than-expected U.S. inflation data led traders to scale back expectations for a rate cut from the Federal Reserve. Gold rose 0.22% to USD 3,392.20, silver inched up 0.01% to USD 38.07, and copper gained 0.22% to USD 9,788.00. Brent crude slipped 0.10% to USD 66.79 after prior gains, with focus on the upcoming U.S.-Russia meeting and its potential impact on global supply.
Our Stance: The ASX 200’s continued upward momentum on Friday, marked by its fifth consecutive record close, reflecting investor confidence supported by stable domestic labour market conditions and expectations of further Reserve Bank easing. However, weaker-than-expected Chinese retail sales and industrial output underscored ongoing global demand risks. In commodities, gold and copper posted modest gains, while Brent crude eased slightly after prior strength. Overall, the near-term outlook remains cautiously optimistic, underpinned by domestic economic resilience and accommodative policy settings, though external headwinds from China could temper upside momentum.
In its latest session, the S&P/ASX 200 Index advanced 61.80 points to close at 8,935.60, with gains supported by a bullish candlestick formation and strong trading volumes, clear signs of sustained investor confidence and active participation from market buyers. From a technical perspective, the index is trading comfortably above its 21-period Simple Moving Average (SMA) on the daily chart, reinforcing a constructive near-term outlook and indicating that the prevailing trend remains intact. The key short-term support sits at 8,840.50, a level that has held firm in recent sessions. A decisive breakout above this zone, especially if accompanied by rising volume, could mark a significant bullish development, potentially shifting market sentiment further toward risk-on positioning and opening the path for the next leg higher. On the weekly chart, the index’s position well above its 21-period SMA adds another layer of strength to the picture, underscoring a robust longer-term bullish foundation.


 Nov 12, 2026





 Please wait processing your request...