
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed higher on Tuesday, rising 20.80 points or 0.25% to 8,481.80. Over the past five sessions, the index has advanced 1.22%, although it remains down 2.67% year to date. Market breadth was positive, with eight of the eleven sectors finishing in the green, reflecting a broadly supportive session. Information Technology led the gains, climbing 2.98% and emerging as the top-performing sector, indicating a rebound following recent weakness. Despite the strong daily performance, the sector remains down 2.63% over the past five days.
Telecommunications Services and A-REITs also recorded notable gains, rising 0.85% and 0.76%, respectively, while Consumer Discretionary advanced 0.51%. On the downside, Energy was the weakest performer, declining 1.15%, making it the largest drag on the market. Consumer Staples and Utilities also ended lower, falling 0.56% and 0.53%, respectively.
Macro Update: The Reserve Bank of Australia (RBA) has released its Conclusions Paper outlining final decisions by the Payments System Board (PSB) following its review of merchant card payment costs and surcharging. Key reforms include removing surcharges on eftpos, Mastercard, and Visa cards, lowering interchange fee caps, and improving fee transparency. The changes aim to enhance competition, reduce business costs, and simplify payments for consumers. Most measures will take effect from 1 October 2026, with additional reforms from 1 April 2027. The RBA will also consult on broader payment system regulation, including mobile wallets and buy-now-pay-later services, in mid-2026.
Top Market Movers: Top gainers on the ASX included Resolute Mining (ASX:RSG), rising to AUD 1.395, up AUD 0.110 (8.56%), followed by IDP Education (ASX:IEL), gaining AUD 0.290 (7.69%) to AUD 4.060, and Generation Development Group (ASX:GDG), up AUD 0.290 (7.42%) to AUD 4.200. Among decliners, Sims (ASX:SGM) fell AUD 1.450 (7.49%) to AUD 17.900, Whitehaven Coal (ASX:WHC) dropped AUD 0.590 (6.00%) to AUD 9.250, and Yancoal Australia (ASX:YAL) declined AUD 0.410 (4.71%) to AUD 8.290.
Commodity Update: The U.S. dollar strengthened on Monday, reaching its highest level since May 2025 as investors continued to favour the currency amid escalating conflict in the Middle East. The stronger dollar was accompanied by gains in precious metals, with gold rising 0.79% to USD 4,593.50 and silver advancing 2.42% to USD 72.35, while copper edged 0.01% higher to USD 12,208.40. Brent crude, however, fell 1.09% to USD 106.24, capping a volatile month shaped by inflation and slower growth concerns.
Our Stance: The S&P/ASX 200 closed higher, supported by broad-based sector gains, with technology leading a rebound despite recent weakness. Strength in telecommunications and real estate added to positive market breadth, while declines in energy and defensives capped upside. Macro developments from the Reserve Bank of Australia signal a shift toward greater efficiency and transparency in payments, potentially easing cost pressures. Meanwhile, a stronger US dollar and mixed commodity trends reflect ongoing global uncertainty. Overall, the market appears cautiously optimistic, with improving sentiment but still facing macro and sector-specific headwinds.
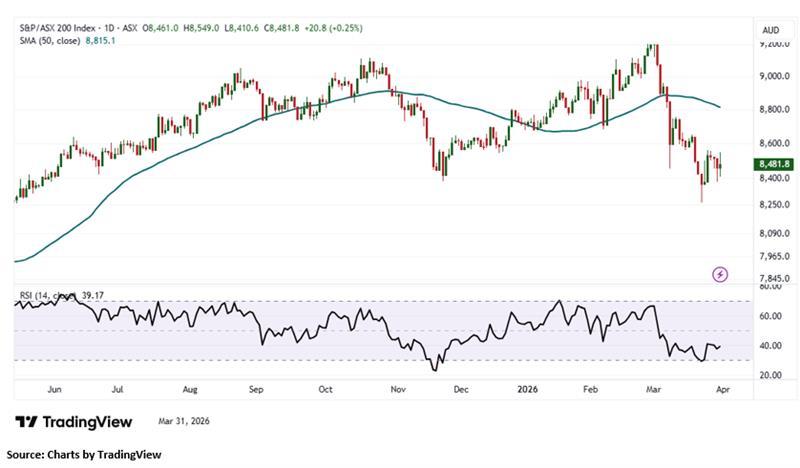
The S&P/ASX 200 edged higher by 20.80 points in its latest session, forming a small bullish candlestick that reflects modest buying interest. However, the broader technical structure remains cautious. The index continues to trade below its 50-period Simple Moving Average (SMA) on the daily chart, which is acting as a key resistance level and limiting further upside momentum. Unless a sustained breakout above this level occurs, the near-term outlook is likely to remain constrained. On the downside, immediate support is placed near 8,440, a critical level that must hold to stabilise market sentiment and avoid a deeper corrective phase.


 Nov 12, 2026





 Please wait processing your request...