
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The Australian sharemarket closed lower on Tuesday, with the S&P/ASX 200 slipping 46.10 points, or 0.52%, to finish at 8,803.50. The benchmark has now lost 1.09% over the past five sessions and sits 2.77% below its 52-week high.
Sectors ended mixed, with eight of eleven closing in negative territory. Information Technology led gains, rising 0.41% on the day and 0.36% over the past five sessions, while Energy was the worst performer, falling 0.99% as Woodside and Santos extended losses for a second consecutive day following OPEC+’s agreement to boost output from October.
The local index also diverged from Wall Street’s upbeat tone, where the Dow Jones gained 0.2% to 45,514 points, the S&P 500 advanced 0.2% to 6,495 points, and the Nasdaq added 0.5% to close at a record 21,798 points.
Macro Update: Australian business turnover rose 2.9% in July, the highest gain since May 2022, according to the data shared by the Australian Bureau of Statistics (ABS). Growth was recorded across all industries, led by a 15.8% jump in the electricity, gas, water and waste division on surging wholesale energy prices, pushing the sector to a new record high.
The value of residential dwellings increased by 1.9% in the June quarter to AUD 11.6 trillion. ABS data showed rises across all states, though annual growth slowed to 5.1% from 8.9% a year earlier, pointing to a cooling property market.
Meanwhile, China’s National Bureau of Statistics will release August CPI and PPI figures tomorrow at 11:30am AEST, offering fresh signals on inflation trends.
Top Market Movers: IDP Education Ltd (ASX: IEL) led the gains on Tuesday, rising 4.52% to close at AUD 5.55, followed by Vault Minerals Ltd (ASX: VAU) up 4.17% at AUD 0.63 and Imdex Ltd (ASX: IMD) climbing 3.58% to AUD 3.18. On the downside, Polynovo Ltd (ASX: PNV) fell 5.78% to AUD 1.39, HMC Capital Ltd (ASX: HMC) slipped 4.85% to AUD 3.53, and Premier Investments Ltd (ASX: PMV) dropped 3.41% to AUD 22.12.
Commodity Update: The dollar slipped to a nearly seven-week low on Tuesday as markets awaited U.S. data revisions that may reveal deeper labour market weakness, strengthening the case for sharper Federal Reserve rate cuts. Commodities advanced, with gold up 0.28% at USD 3,687.50, silver rising 0.25% to USD 42.00, and copper gaining 0.30% at USD 9,952.60. Brent crude added 0.20% to USD 66.17, supported by limited OPEC+ output hikes and renewed sanctions concerns on Russia.
Our Stance: The Australian sharemarket extended losses on Tuesday, with the S&P/ASX 200 closing at 8,803.50, as weakness in Energy offset modest strength in Information Technology. Despite Wall Street’s upbeat lead, local sentiment remained cautious, weighed by OPEC+’s planned supply boost and ongoing sectoral headwinds. Macro signals were mixed: business turnover surged 2.9% in July, the strongest since May 2022, while housing values rose but showed slowing annual growth, pointing to cooling property momentum. Commodity markets were firmer, aided by a softer U.S. dollar, though equities failed to capitalize. With China’s inflation data due tomorrow and global rate expectations in flux, investors are likely to tread carefully, balancing external macro shifts against domestic growth signals.
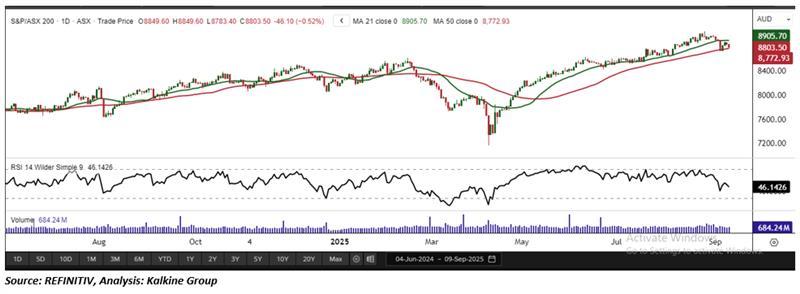
The S&P/ASX 200 Index came under pressure, sliding 46.10 points and forming a bearish candlestick on rising volume a sign of increasing short-term selling momentum and the potential for further downside. The index is currently trading below its 21-period Simple Moving Average (SMA), which has now turned into an important resistance level. On the daily chart, support around 8,700 remains critical; holding above this zone could provide a base for a potential rebound. However, a decisive breakdown would expose the index to deeper losses in the near term. From a broader perspective, the weekly chart remains more constructive. The index continues to trade above its 50-period SMA, underscoring the resilience of the long-term uptrend. While near-term volatility is expected to persist, the outlook remains bullish over the longer horizon as long as key support levels are preserved.


 Nov 12, 2026





 Please wait processing your request...