
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 closed higher on Tuesday, 3 November 2026, gaining 30.30 points, or 0.34%, to settle at 8,886.80, as shares rallied towards the close following the RBA’s Interest Rate hike decision. The benchmark advanced 0.41% over five sessions and remained 4.41% below its 52-week high. Seven of the 11 sectors finished in positive territory, led by A-REIT, which climbed 2.85% on the day and 4.08% over five sessions. Consumer Discretionary gained 1.87%, while Telecommunications Services rose 1.72%. Energy was the weakest sector, declining 3.45%.
Macro Update: The Reserve Bank of Australia (RBA) increased the cash rate by 25 basis points to 4.85% on 3 November 2026, marking its fifth rate hike this year. The decision followed a divided vote, with six board members supporting the increase and three favouring unchanged rates at 4.60%. The Central Bank highlighted persistent inflationary pressures, elevated energy prices and domestic capacity constraints. With Inflation expected to remain above target for longer, the RBA reaffirmed its commitment to price stability while signalling that future Monetary Policy decisions would depend on evolving economic conditions and risks.
Top Market Movers: Netwealth Group Limited (ASX:NWL) led the gainers, rising 6.911%, or AUD 1.260, to AUD 19.490, followed by Qantas Airways Limited (ASX:QAN), which advanced 6.363% to AUD 9.360. Barrenjoey Group Limited (ASX:BJY) gained 6.140% to AUD 8.470. Among the decliners, Amp Limited (ASX:AMP) fell 9.362% to AUD 2.130, while Smartgroup Corporation Ltd (ASX:SIQ) dropped 7.974% to AUD 11.080. 4DMedical Limited (ASX:4DX) declined 7.308%, or AUD 0.190, to close at AUD 2.410, completing the three largest declines among the listed stocks.
Commodity Update: The US dollar fluctuated alongside oil prices amid hopes of a diplomatic breakthrough between the US and Iran, while the Australian dollar remained steady ahead of the Reserve Bank of Australia's policy decision. Gold declined 0.41% to USD 3,953.10, silver fell 1.60% to USD 50.08, and copper decreased 1.41% to USD 14,171.10. Brent Crude slipped 0.30% to USD 105.40 after the previous session's sharp decline, as reported US strikes on Iran's Qeshm Island renewed concerns over Middle East Supply disruptions.
Our Stance: The S&P/ASX 200 ended Tuesday 0.34% higher at 8,886.80, reflecting resilient investor sentiment despite the RBA’s 25-basis-point rate hike to 4.85%. Gains across seven sectors, particularly A-REIT and Consumer Discretionary, supported the benchmark, while Energy remained under pressure. Netwealth Group and Qantas Airways led advances, contrasting with sharp declines in AMP and Smartgroup. Meanwhile, weaker gold, silver, copper and oil prices highlighted broader Commodity market uncertainty. The late-session recovery suggests investors remain selectively optimistic, although persistent inflation, tighter monetary policy and geopolitical tensions could limit near-term upside and keep market Volatility elevated in coming sessions.
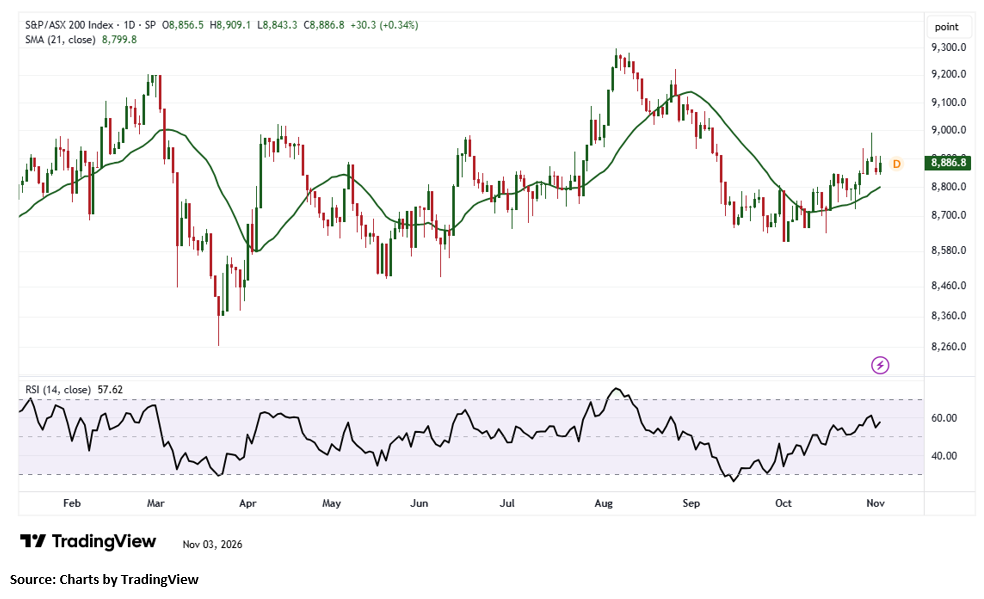
From a technical perspective, the S&P/ASX 200 index posted gains in the latest trading session, indicating signs of stabilisation following the recent pullback. The index continues to hold above key support at 8,850.60, which remains critical to maintaining its broader technical structure. Sustained trading above this level could improve investor sentiment and support a recovery towards recent highs. On the upside, immediate resistance is positioned near 8,920.50, and a decisive breakout above this level could strengthen bullish momentum and pave the way for a further advance towards 9,000. Conversely, a sustained break below 8,850.60 could undermine the recovery attempt and expose the index to renewed selling pressure.


 Nov 12, 2026





 Please wait processing your request...