
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: The S&P/ASX 200 Index closed higher on Monday, rising 36.60 points or 0.41% to finish at 9,031.90, supported by a positive lead from Wall Street and broad gains across the Australian sharemarket. Nine out of eleven sectors ended in positive territory, with Financials leading the advance by gaining 1.48% for the day and 0.93% over the past five sessions. This strong sector performance helped drive the overall market higher alongside substantial contributions from Information Technology, Industrials, A-REITs, and several other sectors. At the same time, Materials and Health Care posted modest declines.
Macro Update: After a week of talks marked by persistent trade spats and intensifying geopolitical distrust, the world's finance chiefs found themselves awaiting the outcome of a potential summit between US President Donald Trump and Chinese President Xi Jinping. In Washington, the mood during the annual World Bank and International Monetary Fund meetings was tempered by relief that Trump’s tariffs had not caused a deeper slowdown but also worry about future escalation. Policymakers harboured hope that the two leaders would meet at the end of the month, recognizing that the global economic outlook now hinges on the US-China relationship. This pivotal moment arrived against a backdrop of harsh rhetoric, as both Washington and Beijing flexed their influence with export controls, America targeting advanced technologies and China leveraging its rare earths supply, highlighting their dominance in crucial industries.
Top Market Movers: Lynas Rare Earths (ASX:LYC) led the gainers on the ASX with a closing price of AUD 20.510, up 6.60%. Generation Development Group (ASX:GDG) followed, ending at AUD 7.120, up 4.40%, while Zip Co (ASX:ZIP) rose to AUD 4.610, up 4.30%. On the losing side, Deep Yellow (ASX:DYL) plunged 18.75% to AUD 1.885, Bapcor (ASX:BAP) dropped 17.67% to AUD 2.610, and Emerald Resources (ASX:EMR) fell 9.35% to AUD 5.040.
Commodity Update: The U.S. dollar steadied on Monday as easing trade tensions between Beijing and Washington and reduced concerns over U.S. regional banks lifted risk appetite. Gold gained 1.27% to USD 4,268.70 per ounce, silver rose 1.30% to USD 50.28, and copper advanced 1.09% to USD 10,709.95. However, Brent crude slipped 0.40% to USD 61.05 per barrel amid persistent worries over a global supply glut and softer energy demand.
Our Stance: The Australian sharemarket began the week on a firmer note, buoyed by global optimism and a strong performance in Financials, which helped the S&P/ASX 200 Index close higher at 9,031.90. Gains across IT, Industrials, and A-REITs underscored broad market participation, offsetting mild weakness in Materials and Health Care. Investor sentiment was lifted by easing trade tensions and renewed risk appetite, even as global policymakers awaited clarity from a potential Trump–Xi summit. Commodity markets mirrored the cautious optimism, with precious and base metals rising while crude oil softened, suggesting a measured but constructive tone for near-term market direction.
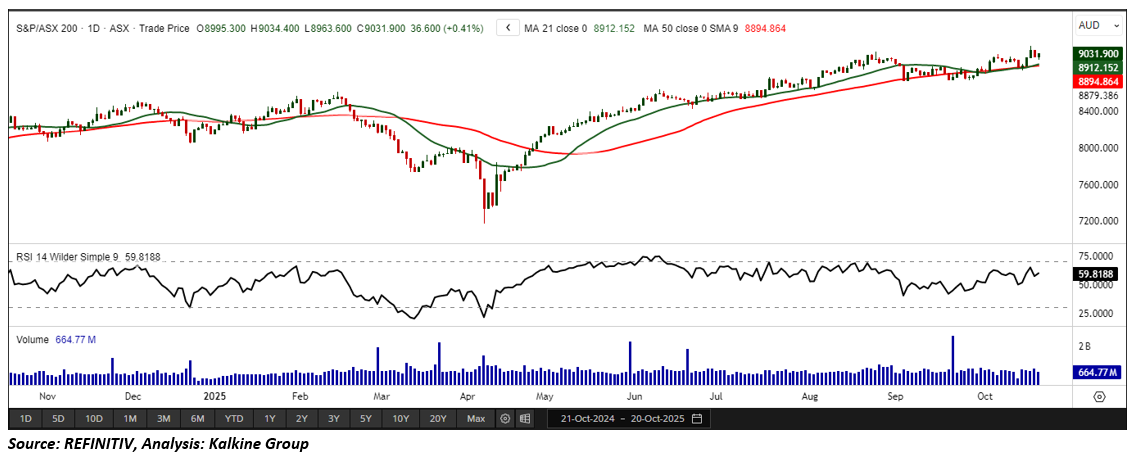
In its latest session, the S&P/ASX 200 Index gained 36.60 points to close at 9,031.90, forming a bullish candlestick supported by strong trading volumes clear signs of continued investor confidence. On the daily chart, the index remains above its 50-period Simple Moving Average (SMA), which continues to act as dynamic support. A key support zone lies near 8,920.50, and maintaining levels above this threshold is crucial to sustaining the prevailing uptrend. Holding this support may allow the index to consolidate recent gains and reinforce confidence in the broader upward trajectory. From a weekly perspective, the index also remains above its 21-period SMA, a constructive technical setup that indicates potential for sustained momentum over the longer term, provided near-term support levels hold firm.


 Nov 12, 2026





 Please wait processing your request...