
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Index Update: Australian shares rose on Thursday, supported by notable gains in technology and health stocks, offsetting mixed signals from Wall Street amid a profit-taking session. The S&P/ASX 200 closed up 25.20 points or 0.29% at 8,720.80. Over the past five days, the index has been largely flat and sits 4.33% below its 52-week high. Ten of the 11 sectors ended higher, with Information Technology leading, climbing 1.72% and recovering from recent losses. Over the past five days, the sector has been down 0.54%.
Macro Update: According to the latest Australian Bureau of Statistics (ABS) data, the seasonally adjusted goods balance fell AUD 1,417mn in November. Exports declined AUD 1,353mn (‑2.9%), mainly due to lower shipments of metal ores and minerals, while imports edged up AUD 63mn (0.2%), driven by processed industrial supplies n.e.s. Meanwhile, the Consumer Price Index (CPI) increased 3.4% year-on-year to November 2025. Key contributors to annual inflation included Housing (+5.2%), Food and non-alcoholic beverages (+3.3%), and Transport (+2.7%), according to data released yesterday.
Top Market Movers: On the ASX, Mesoblast Limited (ASX:MSB) led gains, rising AUD 0.22 to AUD 2.95, up 8.06%, followed by Zip Co Limited (ASX:ZIP) at AUD 3.42 (+7.21%) and Austal Limited (ASX:ASB) at AUD 7.80 (+5.55%). On the downside, Ansell Limited (ASX:ANN) fell AUD 2.22 to AUD 33.36 (-6.24%), Capricorn Metals Ltd (ASX:CMM) dropped AUD 0.86 to AUD 13.98 (-5.80%), and Lynas Rare Earths Limited (ASX:LYC) slipped AUD 0.82 to AUD 14.24 (-5.45%).
Commodity Update: The U.S. dollar traded steadily on Thursday as investors assessed fresh economic data pointing to a fragile U.S. growth outlook ahead of Friday’s key jobs report, while elevated geopolitical tensions capped risk appetite. In commodities, gold slipped 0.25% to USD 4,452.20, silver gained 0.22% to USD 77.77, and copper eased 0.02% to USD 12,889.00. Brent crude rose 0.60% to USD 60.34, rebounding on a larger-than-expected U.S. crude inventory draw and ongoing focus on Venezuela developments.
Our Stance: Australian equities finished higher on Thursday, with the S&P/ASX 200 climbing 25.20 points or 0.29% to 8,720.80, as strength in technology and health sectors helped offset weaker cues from Wall Street after profit‑taking weighed on U.S. markets. Ten of the 11 sectors ended in positive territory, with Information Technology notably rebounding, although it has lagged over the past week. Latest data show goods exports contracted sharply in November, while imports rose modestly, and CPI inflation held at 3.4% annually, led by housing, food and transport pressures. Commodity markets remain mixed, with precious metals supported amid global uncertainties and energy prices fluctuating. The market’s resilience in the face of mixed macro prints suggests investors are selectively rotating into growth-oriented pockets, but lingering inflation and trade headwinds warrant a cautious stance.
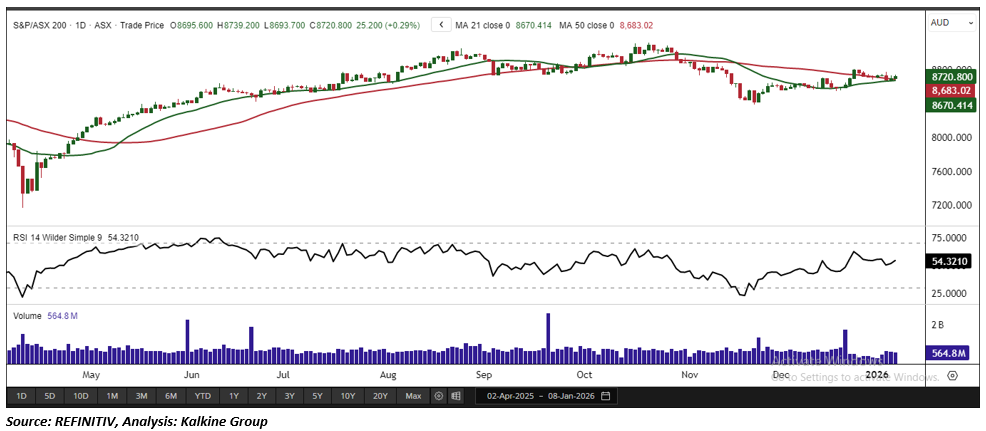
In its latest session, the S&P/ASX 200 Index gained 25.20 points to close at 8,720.80, forming a small bullish candlestick supported by strong trading volumes signals of sustained investor confidence. On the daily chart, the index continues to trade above its 21-period Simple Moving Average (SMA), which remains a key dynamic support and reinforces the prevailing short-term uptrend. The support zone near 8,640 remains critical in maintaining the current bullish structure, and holding above this level is essential for preserving near-term strength. A successful defense of this area would enable the index to consolidate recent gains while reinforcing its broader upward momentum. From a weekly perspective, the index is trading comfortably above its 50-period SMA, highlighting a constructive longer-term technical outlook. Overall, the setup suggests further upside potential, provided key support levels remain intact.


 Nov 12, 2026





 Please wait processing your request...