
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
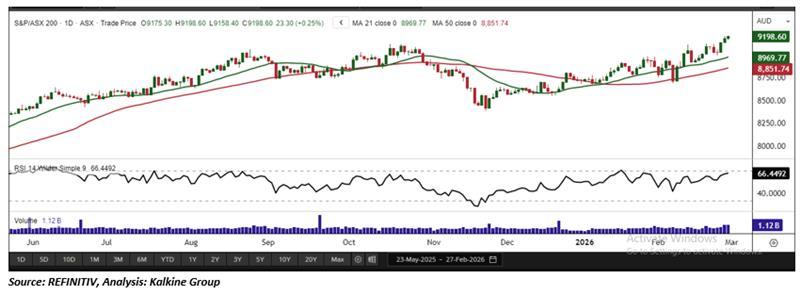
Index Update: The S&P/ASX 200 closed higher on Friday, rising 23.30 points or 0.25% to 9,198.60 and marking a new 52-week high. Over the past five days, the index has advanced 1.29% and now sits just 0.05% below its peak level. The Australian sharemarket also recorded its biggest monthly rise in 10 months, capping a volatile reporting season that concluded with the sharp fall in Coles shares.
Seven of the 11 sectors finished in positive territory. Utilities led the gains, climbing 1.41% and rebounding from its recent decline, although the sector remains down 1.10% over the past week. Telecommunications services rose 1.28%, materials added 1.00%, energy increased 0.94%, industrials gained 0.64%, and A-REITs edged up 0.43%. Health care posted a modest 0.10% rise.
On the downside, consumer staples fell 2.69%, making it the worst-performing sector as selling pressure weighed on consumer stocks. Information technology slipped 0.32%, financials eased 0.24%, and consumer discretionary was marginally lower by 0.05%.
Macro Update: U.S. Treasury yields fell as investors awaited wholesale inflation data and assessed economic conditions. The 10-year yield eased to 4.01%, the 30-year to 4.666%, and the 2-year to 3.438%. Initial jobless claims rose to 212,000 but stayed below forecasts. Strong January payrolls and resilient labour data continued to shape expectations for the Fed and bond market direction.
Top Market Movers: Top gainers were Block, Inc. (ASX:XYZ), up AUD 20.500 or 27.834% to AUD 94.150, Lynas Rare Earths Limited (ASX:LYC), rising AUD 1.740 or 10.092% to AUD 18.980, and Iluka Resources Limited (ASX:ILU), gaining AUD 0.560 or 9.046% to AUD 6.750. Biggest decliners were Harvey Norman Holdings Limited (ASX:HVN), down AUD 0.570 or 9.005% to AUD 5.760, Mesoblast Limited (ASX:MSB), and Coles Group Limited (ASX:COL).
Commodity Update: China’s central bank acted to moderate the yuan’s recent strength by removing foreign exchange risk reserves on select forward contracts, a step that may support dollar demand. Gold edged up 0.10% to USD 5,199.60, while silver climbed 3.24% to USD 89.78 and copper gained 0.36% to USD 13,347.30. Brent crude slipped 0.40% to USD 70.48 amid extended U.S.–Iran nuclear talks and rising Venezuelan oil sales.
Our Stance: The S&P/ASX 200 closed at a fresh 52-week high, capping its highest monthly gain in 10 months as most sectors advanced, led by utilities, while weakness in consumer staples limited broader upside. U.S. Treasury yields eased on softer-than-expected jobless claims, reinforcing expectations that resilient labour conditions will continue to guide policy outlook. Commodities were mixed, with strength in precious and base metals contrasting with softer oil amid geopolitical supply developments and China’s currency move supporting the dollar. Overall, the backdrop remains constructive for equities, though sector rotation and macro sensitivity suggest momentum may stay selective rather than broad-based in the near term.
In the latest session, the S&P/ASX 200 rose 47.00 points to close at 9,198.60, forming a strong bullish candlestick on elevated volumes, reflecting solid investor confidence and active market participation. Technically, the index remains comfortably above its 50-period Simple Moving Average on the daily chart, reinforcing the prevailing short-term uptrend. Immediate support is positioned near 9,190; sustained trade above this level would help maintain the constructive structure and open the door for further upside. Conversely, a break below this zone may introduce short-term volatility. On the weekly timeframe, the index continues to hold well above its 50-period SMA, underscoring a firm medium- to long-term trend and confirming that the broader market bias remains positive despite near-term fluctuations.


 Nov 12, 2026





 Please wait processing your request...