
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
Source: Krish Capital Pty Ltd
Index Update: The S&P/ASX 200 ended Friday with a modest gain of 14.70 points, or 0.17%, closing at 8,787.70. Despite the daily rise, the index has remained almost flat over the past week and is currently 2.95% below its 52-week high, reflecting cautious sentiment amid mixed sector performances. More sectors ended red than green, despite the gain in the S&P/ASX 200 Index. Materials led the charge, surging 0.90% on Friday and posting a notable 5.91% gain over the week. However, most other sectors lagged, with health care and utilities declining the most, dragging on broader market strength.
Macro Update: US President Donald Trump has announced a sweeping new tariff package, including 100% duties on branded pharmaceuticals and 25% levies on heavy-duty trucks, to take effect next week. The move, unveiled on Truth Social, gives drugmakers five days to begin building U.S. plants or face the penalties. The latest measures, framed as protecting national security and manufacturing, triggered urgent reviews in Australia, where billion-dollar drug exports are at risk.
Top Market Movers: On the ASX today, IperionX Limited (ASX:IPX) led the gainers, rising to AUD 7.70, up 6.06%. Tabcorp Holdings (ASX:TAH) advanced 4.62% to AUD 1.02, while Iluka Resources (ASX:ILU) gained 4.10% to close at AUD 6.60. Among the laggards, Megaport (ASX:MP1) fell 5.08% to AUD 15.87, HUB24 (ASX:HUB) dropped 4.19% to AUD 98.94, and Mesoblast (ASX:MSB) slipped 3.62% to AUD 2.40.
Commodity Update: The dollar held firm Friday after upbeat U.S. data reduced expectations of further Fed easing this year. Gold slipped 0.02% to USD3,770.50, while silver eased 0.19% to USD45.03. Copper gained 0.17% to USD10,281.05. Brent crude rose 0.20% to USD69.57, set for its sharpest weekly advance since early June, as Ukraine’s strikes on Russia’s energy assets prompted Moscow to curb fuel exports and signal potential crude output cuts.
Our Stance: The S&P/ASX 200 closed modestly higher, but broader market sentiment remains subdued amid global trade tensions and mixed sector performance. Materials outperformed, but losses in health care and utilities weighed on overall gains. Heightened geopolitical risk follows the U.S. administration’s aggressive tariff package, placing Australian pharmaceutical exports under immediate threat. Market participants are reacting cautiously, with rotation evident in key sectors. Commodity movements remained muted, though Brent crude's weekly surge highlights growing supply-side risks. Currency stability reflects reduced bets on U.S. rate cuts, adding pressure to rate-sensitive equities. Uncertainty over global trade policy remains a central overhang for near-term equity positioning.
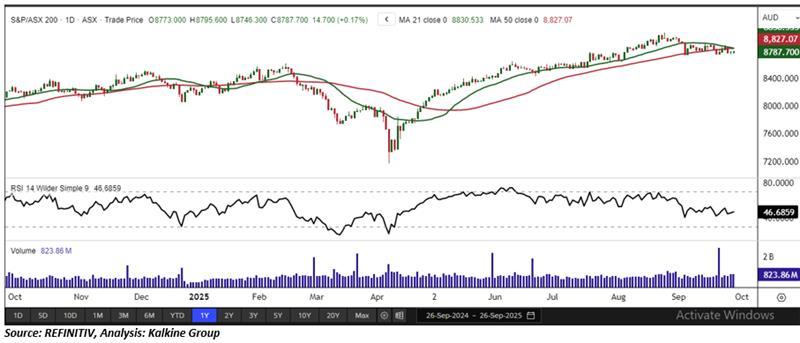
In its latest session, the S&P/ASX 200 Index advanced 14.70 points to close at 8,787.70, supported by a bullish candlestick formation and strong trading volumes clear signs of sustained investor confidence. On the daily chart, however, the index remains below its 21-period Simple Moving Average (SMA), which continues to act as dynamic resistance and maintain a short-term negative bias. A key support zone lies near 8,700, and holding above this level is essential to preserving the current uptrend structure. On the upside, a decisive break above the 21-SMA would provide strong bullish confirmation, potentially unlocking further upward momentum and shifting sentiment in favour of the bulls. From a broader perspective, the index’s sustained position above the 50-period SMA on the weekly chart highlights a resilient long-term bullish foundation, reinforcing underlying strength across multiple timeframes.


 Nov 12, 2026





 Please wait processing your request...