
 CA
 NZ
 UK
 US
 IND

 AU

 Share
 X (Formerly Twitter)
 Whatsapp
 Facebook
 LinkedIn
 Telegram
 Email This Article
 Copy Link
 Summarize with AI
 Chat GPT
 Perplexity
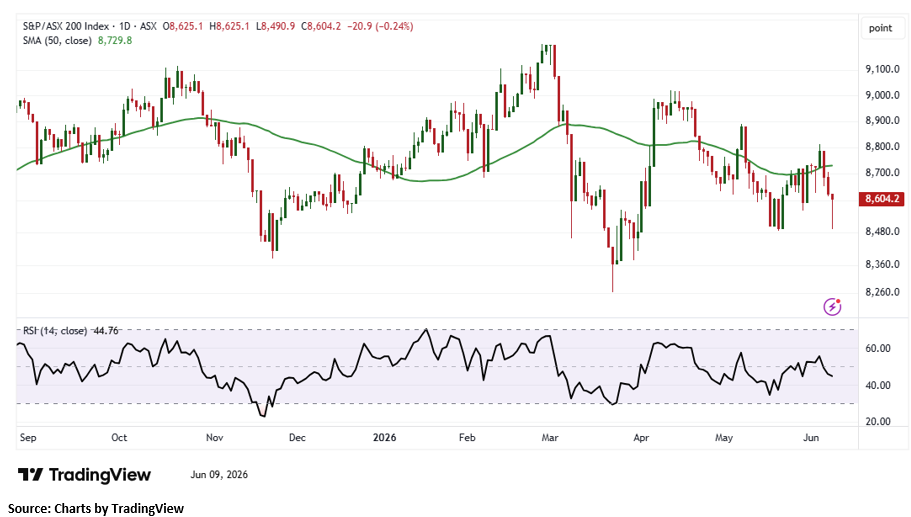
Index Update: The Australian sharemarket edged lower on Tuesday, with the S&P/ASX 200 slipping 20.90 points, or 0.24%, to close at 8,604.20. The decline came despite improving sentiment as Middle East tensions eased, and global technology stocks recovered from last week’s sell-off linked to concerns over potential US Federal Reserve rate hikes. Market breadth remained relatively positive, with seven of the 11 sectors finishing higher. There were gains across Telecommunications Services (+1.71%), Consumer Staples (+1.49%), Consumer Discretionary (+1.36%) and Health Care (+1.32%), while Materials weighed heavily on the index with a 2.32% decline. The benchmark has fallen 1.38% over the past five trading sessions and is down 1.26% year to date.
Macro Update: Australia’s residential property market continued to grow in the March quarter of 2026, with the total value of residential dwellings increasing by $315.9 billion, or 2.5%, to $12.8 trillion, according to the Australian Bureau of Statistics. Annual dwelling values were up 11.9%, with Western Australia and Queensland recording the strongest quarterly price gains, while Victoria was the only state to post a decline.
Meanwhile, investors are awaiting US labour market data, with nonfarm payrolls expected to rise by 85,000 in May, down from 115,000 previously. The unemployment rate is forecast to remain at 4.3%, while cryptocurrency markets edged higher on expectations of no immediate Federal Reserve rate hike.
Top Market Movers: Among the top gainers today, Zip Co Limited (ASX: ZIP) climbed 5.88% to AUD 2.52, gaining AUD 0.14 during the session. IDP Education Limited (ASX: IEL) advanced 5.26% to AUD 2.10, up AUD 0.105, while Temple & Webster Group Ltd (ASX: TPW) rose 5.15% to AUD 4.90, adding AUD 0.24. On the downside, Emerald Resources NL (ASX: EMR) led the losses, falling 9.03% to AUD 5.34. Paladin Energy Ltd (ASX: PDN) declined 8.78% to AUD 10.08, while Deep Yellow Limited (ASX: DYL) dropped 7.62% to AUD 1.455.
Commodity Update: The U.S. dollar remained slightly weaker as investors assessed easing tensions between Iran and Israel after both sides paused hostilities following diplomatic efforts led by U.S. President Donald Trump. The softer dollar provided some support to commodity markets, although price action remained mixed. Gold slipped 0.08% to USD 4,359.80 per ounce, while silver declined 1.21% to USD 67.75 and copper eased 0.22% to USD 13,585.30 per tonne. Brent crude fell 0.68% to USD 93.62 per barrel as concerns over immediate supply disruptions in the Middle East moderated.
Our Stance: The ASX 200 ended Tuesday modestly lower, slipping 0.24% as weakness in materials stocks outweighed gains across most sectors, despite improving global sentiment following easing Middle East tensions and a rebound in technology shares. Broader market participation remained constructive, with seven of 11 sectors advancing. Meanwhile, Australia's residential property market continued to expand, with dwelling values reaching AUD 12.8 trillion in the March quarter. Investors are also closely watching upcoming US jobs data, with softer payroll expectations fuelling hopes that the Federal Reserve may refrain from further rate hikes. While commodity prices were mixed, the overall backdrop suggests markets remain highly sensitive to macroeconomic and policy developments.
The S&P/ASX 200 declined by 20.90 points in the latest trading session, forming a bearish candlestick pattern that reflects weakening near-term sentiment and growing selling pressure. From a technical perspective, the index continues to trade below its 50-day Simple Moving Average (SMA), which remains a significant dynamic resistance level and is limiting upside momentum. Immediate support is located around the 8,600 level, and holding above this area could help stabilise market sentiment and maintain the broader trading structure. However, a decisive break below 8,500.50 would weaken the technical outlook, increasing the risk of a deeper corrective decline and heightened volatility. While the index remains vulnerable below its key moving averages, sustained support above 8,500.50 may provide a foundation for a recovery in the coming sessions.


 Nov 12, 2026





 Please wait processing your request...